Wealth
Smart Money Habits for High Performers: How to Build Lasting Wealth in California


To build wealth in California, you must have two main principles in mind: to maximize your income and to optimize your costs. While many people focus on ways to increase their income, few realize that to achieve financial freedom, you must also reduce your costs. These two principles are equally important.
To build wealth in California, you need to understand two things: First, how to make more money, and second, how to cut costs to the bone to free up as much money as possible from your overhead. True financial freedom is not just about making money.
As with saving money, reducing expenses requires just as much attention as increasing income to succeed in California.
We often forget that simple truth when we’re chasing the next big win.
Understanding the True Cost of Overhead
When we talk about performance and success, we tend to focus on ways to increase your revenue, close deals, and advance your career. But there are also subtle financial leaks in our everyday lives: the money leaving our accounts every month in the form of recurring bills. Just as you want to make sure that you are getting the most from your investments, you also want to make sure that you are getting the most from your money. By understanding and managing your monthly expenses, you can increase your financial runway and accelerate your investment speed.
Think of your fixed personal costs. Just because you are living in a major metropolitan area in California does not mean that you have to pay the high price for the necessities of life. This is why I always recommend that people audit their monthly recurring expenses, especially fixed services, to find ways to reduce them. This will free up some liquid capital for you to invest in assets that will help you build wealth.
Before you know it, that extra cost can add up quickly.
By freeing up liquid capital to invest in a variety of assets, and to fund your personal growth and development, as well as to fund your new entrepreneurial venture, you will be able to use the money that you would have otherwise spent on fixed overhead expenses to increase your cash flow and to create wealth and value for yourself and for others. That is the point.
Auditing Monthly Expenses Without Sacrificing Quality of Life
High-performance financial management of your income for investing, saving, and spending does not need to involve sacrificing your quality of life to keep your spending to a minimum. This smart approach to your money involves looking for intelligent ways to spend it to increase your returns on investment in every way.
Now, it is time to make sure that you are having the highest quality of life by evaluating major recurring personal categories, Fixed Baseline Services, Essential Utilities and Services, and Transportation and Mobility Costs to have high-performance financial management.
Fixed Baseline Services: Are you paying too much for long-term subscriptions and service agreements? Compare what you are currently paying to market rates for similar services.
Essential Utilities and Services: Review current usage metrics for all basic services and relate them to the plans’ current pricing. Ensure there are no excess charges for services that are not actively used.
Transportation and Mobility Costs: The cost of owning and operating a vehicle in California for driving from place to place continues to rise. Not only does the cost of owning and maintaining a vehicle to reach destinations increase (higher purchase prices, higher operating costs, including fuel, and higher costs for vehicle maintenance and repair), but the time it takes to get places is also increasing (longer commutes). Of course, the cost of insurance to protect against accidents or other damage to vehicles, people, or property continues to increase as well. The cost of the cheapest car insurance in California allows for necessary protection while keeping essential monthly costs to a minimum.
However, by simply going through these categories annually or biannually, you can maintain healthy cash flow and keep essential monthly expenses as low and lean as possible, all without compromising your protection. In essence, by working smart with what you currently have, you can most definitely save on the needed recurring overheads, while making sure that you have a sufficient amount of financial resources left over for a more meaningful use (such as in growing your career or in running a successful business).
Turning Monthly Savings Into Exponential Personal Growth
Each saved dollar on recurring expenses can now be invested elsewhere. In terms of building a career or running a business, excess cash flow provides the flexibility needed for optimal operation.
There are several powerful advantages to lowering your monthly living baseline.
Increased Financial Runway: It’s the basis for your professional development and your business: Saving on fixed expenses leads to higher cash flow, which in turn leads to a longer financial runway and greater financial scope for professional risks.
Accelerated Investment Speed: This saved capital can be put towards investments immediately, such as index funds, real estate, or funding a business to grow quickly.
Improved Decision Quality: Operating with a financial cushion prevents reactive decisions driven by short-term money pressures.
What would your career or business look like with an extra 6 months of runway?
Maybe it means taking that leap you’ve been postponing.
Building Sustainable Systems for Long-Term Financial Management
Sustainable wealth is created by systems, not by sporadic instances of frugality. Just as a business creates systems to manage its operations, so too should a person create systems to manage their personal capital.
Once set up, they can continue to protect your downside in the background.
Plan a financial review every few months. Treat it with the utmost seriousness and hold it in the same esteem as a business review or client meeting. Review all major policy rates, cancel any services you are not using, and then review the monthly cash flow to identify any unnecessary costs.
A systematic approach to personal capital management can provide the means to grow your career or business and ultimately achieve long-term independence.







Key Takeaways
- Debt relief is a broad term, not one product or outcome.
- A lower monthly payment can still lead to a higher total cost.
- Compare interest, fees, repayment length, credit effects, and legal risks.
- Be cautious of guaranteed savings, instant forgiveness, or pressure to enroll immediately.
- Written comparisons can make a stressful financial choice easier to evaluate.
Debt relief can refer to several very different approaches, from making a repayment plan on your own to working with a credit counselor, taking out a consolidation loan, pursuing a settlement, or seeking bankruptcy advice. The right choice depends on the type of debt, income, household budget, and how far behind the accounts are.
Before responding to an offer or scheduling a sales call, carefully compare providers and their stated services. For example, researching businesses such as Symple Lending is only one part of due diligence. You should also review written terms, fees, possible credit effects, and what happens if the proposed plan does not work as expected.
Why A Careful Comparison Matters
It is easy to focus on the payment quoted in an advertisement, especially when money is tight. But a smaller payment may result from a longer loan term, added fees, or more interest paid over time. One person may benefit from a lower-rate repayment option, while another may need budget counseling, hardship assistance, or legal guidance. No single route fits every household.
Start With A Clear Picture Of Your Debt
Gather the same facts for every account before comparing offers: creditor name, current balance, interest rate, minimum payment, due date, account status, whether the debt is secured or unsecured, and any collection notices or court papers. This gives you a consistent starting point and helps a counselor, lender, or attorney understand the situation accurately.
Digital tools can organize balances and spending, but artificial intelligence should not replace careful review of a contract or a conversation with a qualified person when the decision could affect your finances for years.
Compare The Main Debt Relief Paths
Direct Repayment
With steady income and manageable payments, you may be able to repay debts independently through a budget. The debt avalanche prioritizes higher-interest balances, while the debt snowball prioritizes smaller balances for quicker account closures.
Creditor Hardship Programs
Contacting a creditor directly may uncover a temporary payment arrangement, rate change, or other hardship option. Ask whether interest, fees, account status, or credit reporting will change, and get the terms in writing.
Debt Consolidation Loans
Consolidation replaces multiple debts with one new loan. Compare the annual percentage rate, loan term, origination fees, monthly payment, and total repayment amount. A lower payment is not automatically a lower-cost loan.
Debt Management Plans
Nonprofit credit counseling agencies may help create a budget and coordinate payments to participating creditors. These plans generally focus on repaying debt in full over time. Ask about setup charges, monthly fees, account restrictions, and the expected program length.
Debt Settlement
Settlement attempts to resolve eligible debts for less than the full balance. It can involve missed payments, additional charges, collection activity, lawsuits, credit damage, and possible tax consequences when debt is forgiven. Results are not guaranteed, and not every creditor or debt will be included.
Bankruptcy
Bankruptcy is a legal process that may be appropriate for severe financial hardship. Eligibility, cost, timing, and the effect on property and debts depend on individual circumstances, so qualified legal advice is important before making a decision.
Look Beyond The Monthly Payment
Use the same comparison points for every option:
- Direct repayment usually limited to existing interest and payments, but progress may be slow.
- Consolidation may include loan fees and interest across the new loan term.
- Debt management may include setup or monthly plan fees, in addition to creditor payments.
- Settlement may include program fees, savings deposits, and costs associated with unresolved accounts.
- Bankruptcy may involve court, attorney, and required-course costs.
Total cost = principal + interest + fees + penalties + related legal or tax costs.
Review Credit And Legal Effects
Missed payments, account closures, and new credit applications can affect credit reports and scores. Collection contacts may continue during some programs, and court papers should never be ignored. The risks of debt settlement include the possibility that fees and unresolved balances can erase expected savings.
Spot Warning Signs Before Signing Up
Slow down if a provider guarantees every debt will be settled, promises a fixed savings amount, asks for payment before delivering the promised service, refuses to provide written terms, claims access to a secret government program, or pressures you to sign during the first call. The FTC warns that upfront fees and guaranteed debt relief are common signs of a scam.
Questions To Ask Any Provider
- Which debts can the program handle?
- What fees apply, and when are they charged?
- What happens if a creditor will not participate?
- Will accounts be closed or payments change?
- Could collection activity or lawsuits continue?
- How long could the process take?
- Who controls money set aside for future payments?
- Can every promise be provided in writing before enrollment?
A Simple Decision Process
- List each debt and build a basic budget after essential expenses.
- Contact creditors early to ask about hardship options.
- Compare at least three realistic paths, including direct repayment when possible.
- Calculate full costs, not just the monthly payment.
- Review written terms, cancellation policies, and provider information.
- Pause before signing and ask questions until the tradeoffs are clear.
Conclusion
A sound debt relief decision starts with clear numbers and realistic expectations. The best option is not always the fastest one or the one with the lowest monthly payment. It is the approach that fits your debt, income, credit goals, and ability to follow through.
Your posts are live, visitors are arriving, and traffic is growing. Now it’s time to turn that attention into income.
Learning how to monetize a website starts with choosing a method that matches your audience, traffic volume, and content.
Get the Basics in Place First
Before adding ads or affiliate links, make sure your website has:
- A clear niche and relevant audience
- Original, useful content
- Fast-loading, mobile-friendly pages
- Privacy policy, About, and Contact pages
- Google Analytics and Search Console
Some monetization programs require minimum traffic levels, but others accept smaller sites. Adsterra, for example, has no minimum traffic requirement for publishers.
Ways to Monetize a Website
Website owners can earn revenue through several methods. Most start with one and add others as their traffic grows.
Ad Networks
Ad networks let publishers earn revenue by displaying ads. After registering and adding ad code, the network serves ads from advertisers without requiring publishers to negotiate individual deals.
Adsterra offers several formats:
- Popunder: Opens a separate tab or window without occupying page space.
- Social Bar: Interactive ads suited to desktop and mobile traffic.
- Native Banners: Ads with customizable colors and fonts.
- Banners: Standard display ads in different sizes.
- Smartlink: A monetization link for websites and supported social traffic sources.
Publishers track performance through eCPM, which measures revenue per 1,000 ad impressions. Earnings depend on traffic quality, GEO, ad format, and advertiser demand. Traffic that performs well for advertisers may generate higher eCPM.
Affiliate Marketing
Affiliate marketing pays publishers commissions when visitors complete qualifying actions through tracked links. Product reviews, comparisons, and guides can attract interested readers. Choose relevant products and clearly disclose affiliate relationships.
Sponsored Content and Newsletters
Brands may pay website owners to publish sponsored articles or promotional placements. Newsletters can also earn revenue through sponsorships, advertising, or subscriptions.
A media kit showing traffic statistics and audience details can help attract potential sponsors.
Matching the Method to Your Site
Different methods suit different traffic levels. These are general suggestions, not fixed requirements.
|
Site Stage |
Monthly Views |
Suggested Methods |
|
Small |
Under 10K |
Ad networks, affiliate links |
|
Growing |
10K–100K |
Ad networks, sponsored posts, newsletters |
|
Established |
100K+ |
Ad networks, memberships, direct ad sales |
Once you know how to monetize a website with one method, consider adding another. For example, a blog can combine display advertising with affiliate links and occasional sponsored articles.
Small Tweaks That Add Up
Test different ad formats and placements to see what works for your audience. Start with one ad network to make performance easier to measure, and avoid excessive ads that interfere with reading.
Monitor impressions, eCPM, and total revenue regularly. Compare results across GEOs, formats, and traffic sources.
Adsterra pays publishers twice a month, with minimum payouts starting at $5 for eligible payment methods. Other methods have higher thresholds.
Some publishers report daily earnings of $50 to $800 or more, but results vary with traffic volume, quality, GEO, and format.
FAQ
How many views do I need before I can monetize a website?
There’s no universal minimum. Some programs require established traffic, while Adsterra accepts publishers without a minimum traffic threshold.
Can I monetize a website without selling anything?
Yes. Display ads, sponsored content, and newsletters can generate income without managing physical products or inventory.
How often do publishers get paid?
Adsterra processes payments twice a month. Minimum payouts start at $5 for eligible methods, while other methods have higher thresholds.
Should I use more than one ad network at once?
Start with one to track performance more easily. You can add others later if their policies and ad implementations are compatible.
Key Highlights
- A Tesla with a novated lease can reduce your taxable income through salary packaging and make lease payments easier to budget.
- Eligible electric vehicle models may qualify for an FBT exemption, which can improve your overall cost.
- Most lease packages can include running costs like charging, insurance, maintenance, and roadside assistance.
- Your employer, you, and a lease provider all play a role in setting up the lease agreement.
- The right fit depends on your financial situation, lease term, and the purchase price of the Tesla model.
- A novated lease calculator helps you estimate monthly payments before you commit.
Introduction
Considering a Tesla with a novated lease but unsure about affordability? You are not alone. The purchase price of a Tesla is an important factor to consider when assessing affordability. A novated lease lets you pay through your salary, potentially improving cash flow and tax benefits. The key question: Is it better for your finances than buying outright?
Understanding Tesla Novated Lease Options in Australia
In a novated lease in Australia, you choose a Tesla with a novated lease and sign an agreement with a lease provider for a fixed term. Instead of paying the full price upfront, you make lease payments over time through salary packaging, and it’s important to consider interest rates associated with the lease.
This can make electric cars more affordable. Eligible EVs may also receive tax benefits, making novated leasing more attractive compared to many petrol cars. Here’s how it works:
What Is a Novated Lease and How Does It Work for Teslas?
A novated lease is a three-way agreement between you, your employer, and a lease provider. You choose a Tesla model, and it’s financed over a set term—usually one to five years.
Your employer typically deducts the novated lease costs through salary packaging, which may include both pre-tax and after-tax contributions for the vehicle and eligible running costs. This setup can lower your taxable income and reduce your tax bill, which in turn affects the tax you pay each pay cycle.
The Role of Salary Sacrifice in Novated Leasing
Salary packaging is central to novated leasing. Instead of paying vehicle costs from your after-tax income, your employer deducts lease payments from your pre-tax salary, lowering your taxable income.
This can help if you’re managing a tight budget—fixed deductions make expenses predictable and simplify planning. For some households, this frees up money for other needs.
Eligibility Criteria for a Tesla Novated Lease
Not every worker or vehicle setup will qualify in the same way, so it is smart to check the basics early. A lease provider will usually look at your employment setup, the lease agreement terms, and whether salary packaging is available through your employer to access the latest technology.
Your financial situation also matters because you need to support the lease term and ongoing deductions, especially at the time of writing. If you are comparing novated lease offers for a Tesla model, focus on eligibility before you get too far into pricing.
Requirements for Employees and Employers
To use salary packaging, your employer must support payroll deductions; otherwise, a novated lease isn’t possible. You should also be comfortable with the lease terms and ensure your income can cover regular pre-tax deductions.
Approval depends on factors such as your employer’s salary-packaging arrangements, the lease terms, and your ability to meet the required repayments. In reality, it depends on whether your employer can handle the setup and if your finances can sustain fixed deductions, which can affect your income tax obligations.
Can You Lease Used Teslas with a Novated Lease?
The information focuses on new Tesla models like the Model 3 and Model Y, but also covers used cars. Check with your lease provider about available novated lease options in Australia.
A used Tesla may have lower lease costs, but its eligibility for tax benefits depends on the vehicle and the specific requirements that apply to the novated lease.
If considering a used Tesla, check with the lease provider whether the vehicle is eligible for a novated lease and separately confirm whether any applicable tax benefits are available.
Exploring Tesla Models Available for Novated Lease
For many buyers, the main question is: which Tesla model is available? The Model 3 and Model Y are the most popular EV novated lease options.
Both are accessible through novated lease providers. When comparing packages in Australia, your best choice depends on cost, features, and how each model fits your budget.
Comparing Tesla Models for Lease Suitability
Choosing the right Tesla for a novated lease involves considering the vehicle’s price, running costs, practicality, and how well it fits your needs over the lease term.
A quick comparison can narrow your options. The Model 3 and Model Y are popular choices, with the Model Y RWD often searched as a specific variant.
| Tesla Model | Lease Suitability Notes |
| Model 3 | Ideal for drivers seeking new cars, tax savings, and predictable regular payments. |
| Model Y | Great for those needing more space and meeting EV criteria; a common leasing option. |
| Model Y RWD | A frequently compared version if you want to evaluate lease costs within the same model line. |
The Tesla Novated Lease Process Step-by-Step
If the idea appeals to you, the next step is understanding the order flow. The process is straightforward, and knowing each stage can make a novated lease less intimidating.
Typically, you choose a vehicle, work with a lease provider, complete the agreement, and get financial approval before delivery. Using a novated lease calculator early on helps estimate affordability before starting the paperwork.
Ordering Your Tesla Through a Lease Provider
First, choose your Tesla model and confirm the vehicle you want. Compare novated lease offers and see how the sale price impacts your package.
Next, the lease provider structures your arrangement, including the car and any optional running costs. The goal is a clear payment plan, so you’re never left guessing.
Documentation and Financial Approval
Once you select a vehicle, the paperwork starts. You will need a lease agreement between you, your employer, and the provider to ensure correct salary deductions.
Financial approval confirms affordability. While a novated lease calculator offers an estimate, approval verifies that lease payments suit your income and payroll.
Financial Benefits of Leasing a Tesla via Novated Lease
For many drivers, the strongest reason to consider this option is the money side. A novated lease can combine tax savings, salary packaging, and bundled running costs in a way that changes the overall cost of driving a Tesla.
That does not mean it is automatically right for everyone. Still, when fringe benefits rules and government incentives line up for eligible EVs, the numbers may look far better than expected. Here is where those savings usually show up.
Tax Advantages and FBT Exemptions
Leasing a Tesla through a novated lease can offer tax benefits, notably the FBT exemption for eligible electric vehicles, which can significantly increase savings.
However, federal rules are specific. Eligibility for the EV FBT exemption depends on specific requirements, including the vehicle type and its value in relation to the relevant luxury car tax threshold.
Calculating Your Monthly Lease Cost
A novated lease calculator estimates your monthly payments based on the vehicle cost and package structure. It helps you gauge overall costs before applying.
Your exact payment depends on the lease details and term length; shorter terms or added costs may increase monthly payments.
Salary Packaging Scenarios Explained
The main pros and cons of a Tesla novated lease come down to structure. The upside is that salary packaging can reduce taxable income and simplify vehicle budgeting, making it an attractive option for many. The trade-off is that the arrangement still needs to suit your personal circumstances.
Managing Ongoing Expenses with a Tesla Novated Lease
Budgeting for the car is just the beginning. You also need to consider ongoing driving expenses.
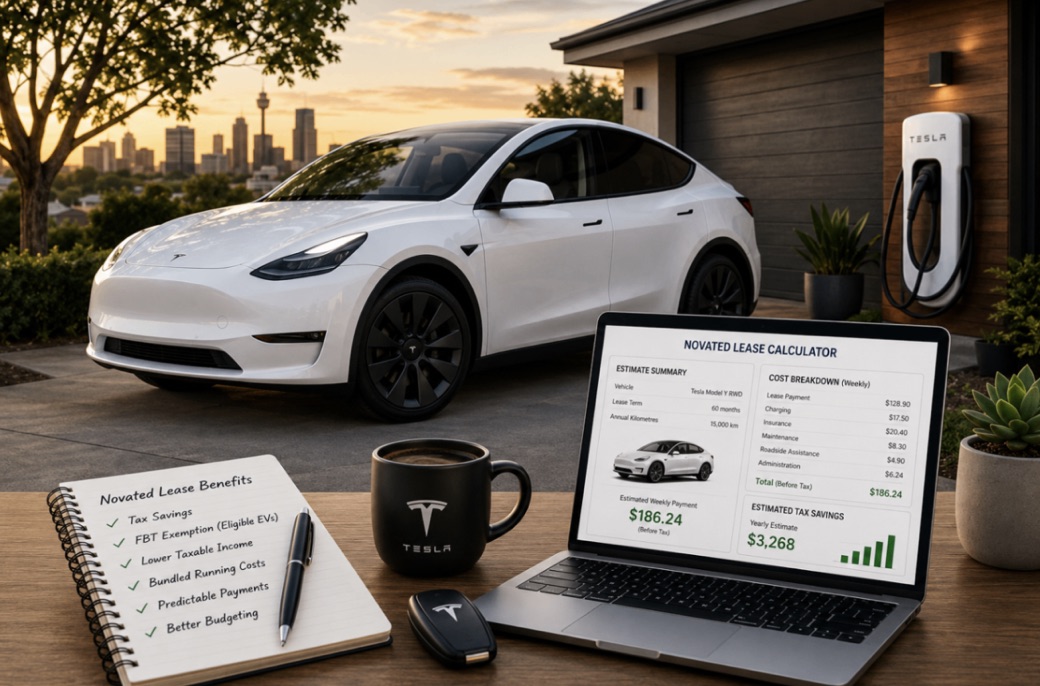
A well-structured novated lease can cover selected running costs, turning unpredictable bills into regular payments. For Tesla drivers, this often includes charging, insurance, maintenance, and roadside assistance.
Included Running Costs: Charging, Maintenance, Insurance
A key benefit of a novated lease is bundling running costs into one plan, reducing bill shock and making budgeting easier.
This is especially useful for Tesla buyers, who often overlook day-to-day expenses. Including these costs in your lease makes ownership more predictable.
Made with AI
Conclusion
A Tesla novated lease may offer tax and budgeting benefits, depending on your individual financial circumstances and eligibility. By understanding salary sacrifice, eligibility, and ongoing costs, you can make an informed decision. Enjoy tax advantages and bundled expenses for greater convenience and potential savings. Ready to learn more? Get a free consultation to see if a novated lease fits your financial goals.
Frequently Asked Questions
Is it worth getting a Tesla on a novated lease in Australia?
A novated lease can be worthwhile if it lowers your taxable income, offers predictable payments, and fits your finances. For eligible Tesla models, tax savings on electric cars can make this option more affordable than many expect.
What ongoing costs are covered under a Tesla novated lease?
A Tesla novated lease can cover running costs like charging, maintenance, insurance, and roadside assistance. Bundling these into your lease payments gives you a clearer monthly budget and reduces separate car-related bills.
Are there tax benefits to leasing a Tesla through a novated lease?
Yes. The main tax benefits of novated leasing are salary packaging and, for eligible EVs, possible FBT exemption. If the Tesla qualifies, avoiding fringe benefits tax can significantly increase the lease’s value.
Key Highlights
- A novated lease with Leaselab lets you choose your car and package lease payments through your pay cycle.
- The novated lease calculator helps estimate vehicle costs, running costs and likely tax savings.
- Leaselab offers flexible leasing plans for new and used cars, including electric vehicles.
- Fixed payments can reduce surprises and make budgeting easier than with many lease providers.
- GST savings and lower taxable income can make the overall cost more manageable.
Introduction
Choosing the right novated lease with Leaselab can save you money, but it also needs to feel clear and practical. That is why many drivers look past flashy offers and focus on how novated leasing actually works, what the terms of service mean, and how their personal information is handled before they commit.
Understanding Novated Leasing with Leaselab
A novated lease with Leaselab is a three-way arrangement between you, your employer and a finance company. You choose the car, sign a lease agreement, and your employer makes payments from your salary before tax.
In simple terms, it works like a car loan with tax advantages built in. Your lease term is usually one to five years, and the setup is designed to make novated leasing easier to understand. That matters when you are comparing any provider.
What makes a novated lease with Leaselab unique?
What stands out is the focus on explaining complex financial products in plain English. Instead of leaving you to decode fine print, Leaselab says it aims to educate drivers from quote to end of lease so decisions are made in your best interests.
That approach can be a good fit if you want clarity before signing. It also helps if this is your first novated lease and you want fewer surprises later.
- Clear guidance on how the lease works
- Full transparency from quote to lease end
- Flexibility based on your situation
Step-by-step overview: How the Leaselab novated lease process works
Here is the short answer: you pick a car, agree to a lease agreement, and the lease payments are taken through your pay cycle before tax. That is the core lease process.
Next, your running costs can be bundled into regular payments, which makes budgeting simpler month to month. If you change to a new employer, the arrangement may need to be set up again through payroll.
- Choose your car and lease term.
- Set repayments through your salary.
- Review options at the end of your lease
At the end of your lease, you can usually pay the residual, refinance or upgrade.
Exploring Leaselab’s Novated Lease Plans for Drivers
Leaselab’s leasing plans are built around choice. Drivers can look at new cars, used cars and electric options, then match the lease agreement to their budget and expected vehicle usage.
That flexibility matters because one plan does not suit everyone. Before you sign, it is worth checking the terms of service, lease length and how the package fits your day-to-day driving.
Vehicle choice and flexibility in Leaselab’s leasing options
One useful feature is broad vehicle choice. You are not locked into one type of car, so your leasing plans can reflect what you actually need, whether that is a used car for value or a new car for longer-term ownership.
The best part for many drivers is being able to compare practical examples. You might look at a Kia on a novated lease for family use, a Ford Ranger novated lease for work needs, or a novated lease Tesla Model Y if you want lower fuel spend.
- New and used car options
- Access to wholesale pricing
- Choice based on your budget
As always, share personal information carefully and review the quote details.
Electric and eco-friendly vehicle support through novated leases
If you want to lease an electric car, this is where the numbers can get interesting. Leaselab highlights that electric vehicles may deliver strong tax savings, especially where the fringe benefits tax exemption applies to eligible EVs.
That can make an EV novated lease more affordable than many people expect. A Tesla novated lease or BYD novated lease may end up closer in cost to a cheaper petrol car once tax and GST savings are counted.
- EVs may qualify for valuable fringe benefits tax relief
- Running costs can be bundled with roadside assistance
Use the calculator to test different EV scenarios before choosing.
Using Leaselab’s Novated Lease Calculator Effectively
The novated lease calculator is there to answer a basic question: what will this car really cost me? It helps you estimate vehicle costs, lease payments, running costs and possible tax savings based on salary and car choice.
That makes it easier to compare options before you apply. Instead of guessing your tax bill, you can test lease lengths, vehicles and budgets in a more practical way.
How to estimate your savings with Leaselab’s online calculator
Start with your salary and preferred car. Then add likely running costs so the online calculator can show a more realistic estimate than a simple car loan comparison. This is useful when comparing lease providers.
A good approach is to use your historical usage. If you know your usual fuel, servicing and tyre spend, your estimate will be closer to a predictable payment.
|
Input |
What it helps show |
|
Salary |
Potential tax savings and effect on taxable income |
|
Vehicle choice |
Purchase price, GST impact and lease payments |
|
Lease term |
How monthly costs change over time |
|
Running costs |
A fuller estimate of total package cost |
Example: Breaking down a real-life novated lease cost scenario
Take a simple lease case. Say you choose a new car with a purchase price of $50,000 and include fuel, servicing and tyres. The novated lease cost is not just the sticker price, because GST and tax treatment affect total vehicle expenditure.
Then check the residual value at the end. A shorter lease may mean higher regular payments, while a longer term spreads costs more evenly.
- Compare the total package, not just the monthly number
- Check what running costs are included in the quote
That is the fairest way to assess one offer against another.
Real Experiences: Insights from Leaselab Novated Lease Customers
Real experiences often come down to two things: did the savings make sense, and was the process easy to follow? In customer reviews, those points matter more than marketing language.
For many drivers, the value of novated lease packages sits in clear lease management and knowing whether they want a fully covered plan or a simpler setup with fewer bundled costs.
Positive highlights: What drivers appreciate about Leaselab
Drivers often like having fixed car payments and a clearer view of tax benefits. For someone moving from a normal finance setup, that can feel like a real game changer because the lease agreement bundles more of the ownership costs into one structure.
The best part is not just lower tax. It is knowing what you are likely to pay each month and having options at lease end.
- Fixed monthly budgeting
- Clearer view of savings versus normal buying
That practical side is what many people value most.
Addressing common client concerns and transparent communication
A common concern is bill shock. People worry that a lease quote looks good upfront, then hidden costs appear later. That is why transparent communication matters when comparing lease providers.
You should look closely at important information such as the terms of service, lease inclusions, residual amount and what happens if your job changes. These are the details that shape the real cost.
- Ask what is included in the packaged payment
- Confirm what happens at the end of the lease
Those questions help you avoid confusion before signing.
Conclusion
In conclusion, choosing a novated lease with Leaselab presents numerous advantages that set it apart from other providers. With unique flexibility tailored to individual needs, a transparent leasing process, and a commitment to eco-friendly vehicle options, Leaselab has cultivated a reputation for customer satisfaction. Clients appreciate the ease of use offered by Leaselab’s online calculator and the practical insights shared by existing customers. As you weigh your options, consider how Leaselab’s offerings align with your driving requirements and financial goals. If you’re ready to explore your possibilities and gain a clearer understanding of your savings, book a free consultation with our experts today!
Frequently Asked Questions
How does Leaselab compare to other novated lease providers in Australia?
Leaselab positions itself as a novated leasing provider focused on education, transparency and flexible lease management. When you compare options, look at competitive pricing, the lease agreement details, support quality and the terms of service rather than the headline payment alone.
What factors should be considered before signing up with Leaselab?
Check the terms of service, your lease term, the residual amount and how the package fits your unique circumstances. It is also wise to review how your personal information is handled and whether the structure is truly in your best interests.
Is a novated lease with Leaselab really worth it?
A novated lease can be worth it if the tax savings outweigh the setup and your running costs suit the package. It is a good fit when fixed lease payments, GST savings and salary packaging leave you better off than buying the car normally.

How to Measure GEO: The Metrics That Matter and the Tools That Track Them

How To Compare Debt Relief Options In Without Getting Misled

Sam Altman Was Right: The 1-Person Billion-Dollar Startup is Already Here

How Career Success Can Change Your Student Loan Repayment Strategy

AI Filtering for Business Phone Lines: Remove Junk Calls Before Your Staff Pick Up
5 Ways For Startups To Succeed Making Acquisitions

77 Inspirational Quotes That Will Change Your Life
57 Memorable Kobe Bryant Quotes

(Images) 52 Motivational Picture Quotes For An Epic Year Of Success
40 Rare Motivational and Inspirational Picture Quotes
3 Prince EA Videos To Change Humanities Path To Greatness
(Video) What Is Success? An Entrepreneurial Story To Inspire You
(Inspirational Video) What If Today You Knew You Were Going To Take Your Last Breath?
How To Make Enough Money From A Blog To Quit Your Job – Kate McKibbin
How Finding Your Passion And Becoming An Entrepreneur Can Lead To Happiness – Chiquita Searle
-
 Life2 years ago
The 5 Stages of a Quarter-Life Crisis & What You Can Do
-

 Did You Know1 year ago
7 Surprising Life Lessons Video Games Taught Me That School Never Did
-
 Success Advice1 year ago
Stephen Covey’s 8 Leadership Habits That Will Change How You Lead Forever
-

 Life1 year ago
How to Stop the War in Your Head and Find Peace
-

 Featured2 years ago
The Psychology of Motivation: How to Keep Moving Forward Every Day
-
 Personal Development1 year ago
The Three-Second Pause That Changes How People Perceive You
-
 Explode Your Social Media1 year ago
Want More Views? Master These 6 YouTube Growth Tactics
-
 Change Your Mindset1 year ago
You Become What You Absorb: How Input Shapes Your Life