Wealth
Why Lost Earning Capacity Can Affect Motorcycle Accident Compensation

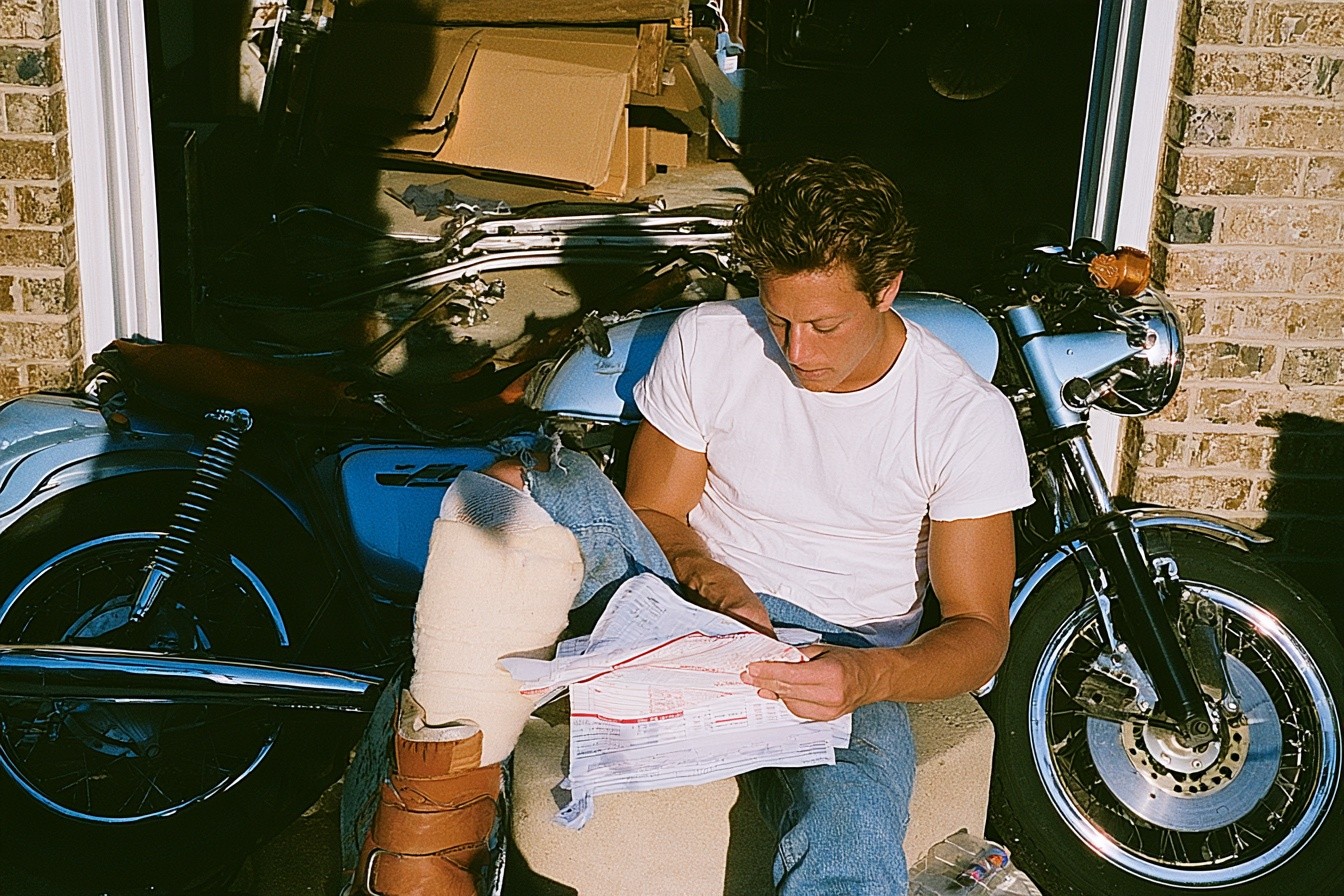
A motorcycle accident can take away more than a person’s ability to ride. It can change how they work, earn money, and support their family. A broken leg may keep a worker away from a job for months, while a head injury may make it hard to focus or complete daily tasks. Even after returning to work, an injured rider may not earn what they once did. These financial losses can affect a motorcycle accident compensation claim. Lost earning capacity deserves attention because an injury can change not only today’s paycheck but also a person’s ability to earn a living.
What Is Lost Earning Capacity After a Motorcycle Accident?
Lost earning capacity refers to a person’s reduced ability to earn money because of injuries from an accident. It differs from simply missing work during recovery. A rider may return to a job but struggle with duties that were once easy to manage. Someone who worked in construction may no longer be able to lift heavy materials, while a delivery worker may find it difficult to ride for long periods.
The main concern is how the injury affects the person’s ability to earn income. Even if a person still receives a paycheck, lasting physical or mental limits may reduce their working hours, job choices, or chances of earning a higher salary.
How Lost Earning Capacity Differs From Lost Wages
Lost wages and lost earning capacity describe two different types of financial loss. Lost wages cover the income a person misses while recovering from an injury. Lost earning capacity concerns the money they may be unable to earn because the injury limits their work.
For example, a worker may miss six weeks of work after breaking a leg in a motorcycle crash. The pay lost during those weeks falls under lost wages. If the injury later prevents the worker from returning to a physically demanding job, the difference in possible future earnings may also matter.
Both losses may be included in a claim if the available evidence supports them. However, future income loss cannot be based only on guesses about what someone might have earned.
How Motorcycle Injuries Can Affect Future Income
Motorcycle accidents can cause serious injuries because riders have little physical protection during a crash. Some injuries heal with time, while others leave lasting problems that affect a person’s ability to work.
Broken bones may limit movement, spinal injuries may cause ongoing pain, and nerve damage may reduce strength or coordination. A head injury can also affect memory, focus, or decision-making, making certain jobs harder to perform safely.
The effect depends on the person’s health, job duties, and recovery. A worker who spends the day standing may face different limits from someone who works at a desk. If an injury forces a person to accept fewer hours, change careers, or leave a job they can no longer perform, the loss of earning capacity may become a major part of the financial claim.
Factors That Can Affect Compensation
The value of a lost earning capacity claim depends on several details. No single factor determines the amount, and each claim needs evidence showing how the injury affects the person’s ability to earn.
Important factors may include:
- Previous income: Pay stubs, tax returns, and employment records can show past earnings and work history.
- Injury severity: Lasting pain, reduced movement, or problems with memory may limit job performance.
- Job duties: Physical work may become harder after injuries that affect lifting, standing, balance, or movement.
- Work experience: A person’s skills, training, and career history may help show the types of jobs they could perform before the accident.
- Career opportunities: Missed promotions, reduced hours, or the need to accept lower-paying work may affect earning ability.
The effect of these factors depends on the facts of the case and the laws that apply.
How to Prove Lost Earning Capacity
An insurance claim needs clear evidence connecting the accident injuries to reduced earning ability. Medical records can describe the injury and explain any lasting limits. Employment records and tax returns can show previous income, while statements from an employer may confirm changes in duties, hours, or pay.
Medical assessments may help explain which work tasks a person can no longer perform. Vocational assessments can also examine how an injury affects available job options. In some cases, financial professionals may estimate how the loss could affect earnings over time.
Keeping records of missed work, job changes, reduced hours, and changes in pay can help create a clearer picture of the financial impact. Evidence should support the claimed loss rather than rely on assumptions about future income.
Looking Beyond the Missing Paychecks
Motorcycle accident compensation may need to account for financial losses that continue long after the first missed paycheck. Reduced earning ability can affect rent, household bills, savings, and other regular expenses. Focusing only on wages lost during recovery may overlook a significant part of the financial impact caused by lasting injuries.
Understanding the difference between lost wages and lost earning capacity can help injured riders identify the types of income loss that may be considered in a motorcycle accident compensation claim. Medical records, employment history, and reliable financial evidence can help demonstrate the extent of those losses. The compensation available ultimately depends on the circumstances of the accident, the supporting evidence, and the applicable law.







The R&D tax credit for startups lets a young company that is building new technology claim up to $500,000 a year against the employer share of its payroll taxes, even if it has zero revenue and pays no income tax. You qualify as a “qualified small business” if you had less than $5 million in gross receipts for the year and no gross receipts before the five-year period ending with that year. You elect it on IRS Form 6765, Section D, attached to a timely filed income tax return, then claim it quarter by quarter on Form 8974 with your Form 941.
Here’s a scene I’ve watched play out with founders more times than I can count. It’s the end of the quarter. The founder is staring at the payroll report: four engineers, one product lead, and a line for employer taxes that feels like a penalty for hiring people. No revenue yet. The runway spreadsheet is open in the next tab, and every dollar going to the government is a dollar not going into the product.
Then someone on their board asks a simple question: “Did you claim the R&D credit against payroll?” And the founder says what most first-time founders say: “I thought that was only for profitable companies.”
It isn’t. Congress built this election specifically for startups that have little or no income tax to offset. If you are paying engineers to solve hard technical problems, a slice of that payroll can come back to you as cash you never send to the IRS in the first place. Most founders leave it on the table simply because nobody told them.
This founder-focused walkthrough from Chris Peters at R&D Tax Advisors explains why pre-revenue companies are not “too early” to claim it:
What the R&D Tax Credit Actually Is
The research credit lives in Section 41 of the tax code. It rewards companies for spending money on qualified research: work that is technological in nature, aimed at a new or improved product or process, and done through a real process of experimentation to remove uncertainty. The IRS calls this the four-part test, and you apply it to each product, feature or process separately.
In plain English: if your team is writing code, designing hardware, formulating a product or engineering a process where the answer wasn’t known at the start, and you tested your way to it, you are probably doing qualified research. If you are doing routine data entry, cosmetic redesigns, market research or customer support, you are not.
The expenses that count, called qualified research expenses (QREs), are mostly three buckets:
- Wages paid to people doing, directly supervising or directly supporting the research. For most startups this is 70% to 90% of the claim.
- Supplies used up in the research, like prototype materials. Not general office stuff.
- Contract research paid to U.S. contractors doing qualified work for you, generally counted at 65% of what you paid.
For a normal profitable company, the credit reduces income tax. The problem is that a pre-revenue startup has no income tax to reduce. That’s where the payroll election comes in.
Why Payroll Is the Startup Superpower
Since the PATH Act of 2015, a qualified small business can elect to use part of its research credit against the employer portion of Social Security tax instead of income tax. The Inflation Reduction Act raised that annual cap from $250,000 to $500,000 for tax years beginning after 2022. The credit first wipes out the employer’s 6.2% Social Security share, and anything left over then reduces the employer’s 1.45% Medicare share. Unused amounts roll into the next quarter.
Read that again from a founder’s seat. You don’t have to be profitable. You don’t have to wait years for income tax to show up. The money comes back by lowering a bill you already pay every single quarter.
To be a qualified small business for the payroll election, the IRS requires two things for the tax year (confirm the current rules in the IRS instructions for Form 6765):
- Gross receipts of less than $5 million for the year.
- No gross receipts in any tax year before the five-tax-year period ending with that year. In practice, your company’s first dollar of revenue starts a five-year clock.
You can make the payroll election for a maximum of five tax years. That’s why I tell founders to treat it like a launch-window benefit. It’s designed for the years when cash is tightest, and it disappears once you grow out of it.
A Simple Example With Real Numbers
Here’s a clearly labeled teaching example, not a promise. Picture a C corporation in its second year. It has five engineers earning $150,000 each, all working on a new machine-learning product, and no prior years with research spending to compare against.
| Line | Amount |
|---|---|
| Engineering wages that qualify | $750,000 |
| Credit rate (alternative simplified method, no prior-year QREs) | 6% |
| Estimated research credit | $45,000 |
| Employer Social Security tax on those wages (6.2%) | $46,500 a year |
| Result | Roughly a full year of employer Social Security tax offset |
Once a company has qualified research spending in each of the three prior years, the alternative simplified method moves to 14% of current QREs above half the prior three-year average, and the credit usually grows. Add contractors and supplies and the number climbs again. For a seed-stage team with a dozen engineers, a six-figure annual credit is not unusual.
That’s not a rounding error. For a lot of seed-stage companies, that’s an extra month or two of runway, or the salary of the next hire.
How to Turn Your Payroll Into Cash Back: Step by Step
Here’s the sequence, in order. Miss the order and you can lose a full year.
- Confirm you are a qualified small business. Under $5 million in gross receipts for the year, and no receipts older than the five-year window. A company with no revenue at all generally passes the receipts test.
- Track research time while it happens. Tie each engineer’s hours to the projects they worked on. Tickets, sprint notes, commit history, test logs and design docs are your best evidence. Reconstructing it a year later is where weak claims are born.
- Calculate the credit on Form 6765. Identify each business component, apply the four-part test, total your QREs and run the credit math.
- Make the payroll election in Section D of Form 6765. Enter the amount you want to apply against payroll, up to $500,000.
- File your income tax return on time. The election must be on a timely filed original return, including extensions. The IRS does not allow it on an amended return. Even if you owe nothing, you still file the return to make the election.
- Attach Form 8974 to Form 941. Starting with the first calendar quarter that begins after you file your income tax return, your payroll provider reports the credit on Form 8974 and your employer tax drops.
- Carry it forward until it’s used. If the credit is bigger than one quarter’s employer tax, the rest rolls to the next quarter.
One timing move founders miss: the credit starts the quarter after you file. A calendar-year company that files in February gets the offset starting April 1. File on extension in October and you wait until January. Same credit, two extra quarters of waiting. If cash matters, file early.
The IRS lays out the payroll mechanics on its page about the research credit against payroll tax for small businesses.
What Changed With Section 174A
For a few painful years, startups doing R&D got hit twice. From 2022 through 2024, the old Section 174 rules forced companies to capitalize research spending and deduct it over five years, which meant some cash-burning startups suddenly owed income tax on “profits” that didn’t exist.
The One Big Beautiful Bill Act fixed that going forward. New Section 174A restores immediate expensing of domestic research and experimental expenditures for tax years beginning after December 31, 2024. Foreign research still gets amortized over 15 years, so where your engineers sit matters.
There was also a special catch-up for small businesses: they could elect to apply the new rules back to 2022 through 2024 by filing amended returns. That window closed on July 6, 2026, as the Taxpayer Advocate Service flagged. It has passed. If you didn’t file in time, don’t let anyone sell you a scheme to chase it. Focus on getting the current year right.
Your expensing choices under 174A and your credit interact, so make sure whoever prepares your return looks at both together. This is exactly the kind of decision that belongs on your list of year-end tax moves, not something to figure out the week the return is due.
Founder Salaries Count Too
Here’s one that surprises people. If you are the technical founder writing code or leading experiments, the W-2 wages you pay yourself for that work can count as qualified research wages. Profit distributions don’t. So the way you pay yourself as a business owner directly affects how big your credit can be.
That doesn’t mean you should inflate your salary to chase a credit. It means that if you are already taking a reasonable salary for real technical work, you should be documenting that time like you document your engineers’.
Should You DIY It or Hire a Firm?
You can prepare this yourself or with your regular CPA. Many startups hire a specialist R&D credit firm. Either can work. What matters is the quality of the claim, because the IRS has been scrutinizing research credits closely and the redesigned Form 6765 now asks for more detail about each business component.
Good signs in a provider:
- They interview your engineers and look at real project records before quoting a number.
- They give you a documentation package you’d be comfortable handing to an examiner.
- They explain how the claim coordinates with your Section 174A treatment and your return.
- Their fee is clear up front, whether flat or a percentage of the credit.
Red flags:
- They promise a credit amount before seeing anything.
- They treat every employee and every expense as qualified.
- They pitch you on amending old years to chase windows that have already closed.
My rule is simple: if a firm can’t explain your claim to you in plain English, they won’t be able to explain it to the IRS either.
The Mistakes That Cost Startups the Most
- Missing the election. No election on the original timely return means no payroll offset for that year. Amending won’t save it.
- Filing late or on a long extension and pushing the cash back by quarters.
- No contemporaneous records. A claim built from memory is a claim built on sand.
- Burning the five-year clock. Your first gross receipts start it. Know which years you can still use.
- Counting the wrong work. Sales, marketing, general admin and post-launch bug fixing usually don’t qualify.
The founders who win with this credit aren’t tax experts. They just build the habit early: track the work, file on time, make the election, and let payroll do the rest. Every dollar you keep is a dollar that goes back into the thing you’re actually building.
R&D Tax Credit for Startups FAQs
Can a pre-revenue startup claim the R&D tax credit?
Yes. A qualified small business with no income tax can elect to apply up to $500,000 of its research credit against the employer share of payroll taxes each year, so a startup with zero revenue can still get real cash value from it.
What is the R&D payroll tax offset limit?
The annual cap is $500,000 for tax years beginning after 2022. The credit first reduces the employer’s 6.2% Social Security tax, then the 1.45% Medicare tax, and any unused amount carries forward to later quarters.
Who qualifies as a qualified small business for the payroll election?
A company with less than $5 million in gross receipts for the tax year and no gross receipts in any year before the five-year period ending with that year. The election can be used for up to five tax years.
Which forms do I need to claim the payroll offset?
Make the election in Section D of Form 6765 and attach it to your timely filed income tax return. Then attach Form 8974 to your Form 941, starting with the first quarter that begins after you file the return.
Can I make the payroll election on an amended return?
No. The payroll election must be made on a timely filed original income tax return, including extensions. If you miss it, you lose the payroll offset for that year, though the credit itself may still carry forward against income tax.
The best health insurance for self-employed founders is usually an ACA Marketplace plan through HealthCare.gov or your state exchange, because it can’t turn you down for health history and may come with a premium tax credit based on your income. Enroll by December 15 for coverage that starts January 1 (open enrollment runs to January 15). Then deduct the premiums on Form 7206 as self-employed health insurance, up to your net self-employment earnings.
That’s the short answer. Here’s the longer one, and it’s the bit most guides leave out.
I’ve watched this happen more times than I can count. Someone leaves a job to build their own thing. The first few weeks are pure adrenaline: a new logo, a first client, a calendar that finally belongs to them. Then a letter shows up that ends their employer coverage at the end of the month, and it lands on the kitchen bench under a pile of invoices. Nobody opens it until a kid gets sick or a tooth cracks.
Going without health insurance doesn’t mean you’re brave. It means one bad week can wipe out your runway. You’d never run your business without a backup of your client files. Your body is the server everything runs on.
So let’s make this simple. Below is what I’d do if I were self-employed and choosing coverage this month, with the dates, the tax rules and the traps that matter in 2027.
Why the 2027 Open Enrollment Matters More Than Usual
Three things changed, and together they make this a year to pay attention instead of letting a plan auto-renew.
1. The dates are tight. HealthCare.gov opened enrollment for 2027 plans on November 1, 2026. Pick a plan by December 15 and coverage starts January 1. Enroll between December 16 and January 15 and coverage starts February 1. After that, you need a qualifying life event, like losing other coverage, getting married or moving, to get in. Some state exchanges keep their own deadlines, so check yours.
2. The subsidy cliff is back. The enhanced premium tax credits that capped benchmark premiums at 8.5% of income and removed the 400% income cap ended after 2025 and weren’t extended. For 2027 coverage, the premium tax credit is generally back to households between 100% and 400% of the federal poverty level. Earn one dollar over 400% and the credit can drop to zero. For a founder whose income swings, that dollar matters.
3. Repaying the overage now has no cap. Under the 2025 tax law, the limits on paying back excess advance premium tax credits are gone for tax years beginning after December 31, 2025, according to the IRS. If you lowball your income estimate and land a big contract in October, you could owe back every dollar of the subsidy at tax time.
And one change works in your favor. Starting January 1, 2026, bronze and catastrophic plans count as HSA-compatible, whether you buy them on the exchange or off it. That opens a tax-free health savings account to a lot of self-employed people who couldn’t use one before.
Your Options: Marketplace vs Spouse Plan vs COBRA vs Short-Term
Most self-employed people have four or five realistic paths. Here’s how I’d compare them with a founder’s eye on cost, flexibility and risk.
| Option | Best for | Subsidy? | Covers pre-existing conditions? | Watch out for |
|---|---|---|---|---|
| ACA Marketplace plan | Most solo founders and freelancers | Yes, premium tax credit at 100% to 400% FPL | Yes | Income estimate; repayment has no cap from 2026 |
| Spouse’s employer plan | Founders with a partner who has good workplace coverage | Employer pays part of the premium | Yes | No Form 7206 deduction for months you’re eligible for it |
| COBRA | Mid-treatment or met your deductible this year | No; you may pay up to 102% of the full cost | Yes | Usually the priciest option; generally ends after 18 months |
| Short-term plan | A brief gap only | No | Usually not | Can deny or exclude conditions; not ACA coverage; state rules vary |
| Off-exchange ACA plan | Higher earners above the subsidy cap | No | Yes | Same plans may be on-exchange; compare before skipping subsidies |
Marketplace. For most one-person businesses, this is the default. HealthCare.gov’s self-employed guide treats you like any other individual buyer. You estimate your net self-employment income, and your subsidy depends on that number.
Spouse plan. If your partner’s employer offers family coverage at a decent price, this is often the cheapest route. The catch is tax: you can’t take the self-employed health insurance deduction for any month you were eligible for a subsidized employer plan, even if you didn’t enroll.
COBRA. I’d only keep COBRA if you’re in the middle of treatment with specific doctors or you’ve already hit your deductible for the year. Losing job-based coverage also opens a 60-day Special Enrollment Period, so you can compare it against a Marketplace plan before you commit.
Short-term plans. These are a stopgap, not a strategy. They can refuse you, exclude conditions and skip benefits that ACA plans must cover. Some states restrict or ban them. Don’t build a business on one.
The Self-Employed Health Insurance Deduction (Form 7206)
This is where being your own boss pays you back. If you have net profit from self-employment, you can usually deduct the premiums you pay for medical, dental and vision insurance (and qualified long-term care, within limits) for yourself, your spouse and your dependents. It’s an above-the-line deduction, so you get it whether you itemize or not.
Since tax year 2022, the IRS has you calculate it on Form 7206. The rules that trip people up:
- It’s capped at your earnings. The deduction can’t be more than the net earned income from the business the plan is established under. A loss year means no deduction from that business.
- Employer eligibility kills it month by month. If you or your spouse could join a subsidized employer plan in a given month, that month’s premiums don’t qualify.
- It cuts income tax, not self-employment tax. You still owe the roughly 15.3% self-employment tax on your full net profit.
- It interacts with your subsidy. If you also get a premium tax credit, you can only deduct the premiums you actually paid. Both numbers affect each other, so let software or a tax pro do the math.
Here’s a simple teaching example. A solo designer nets $70,000 and pays $6,000 in premiums after subsidies, with no employer plan available. She can generally deduct the full $6,000, which at a 22% bracket saves about $1,320 in federal income tax. That’s real money for a business of one.
The S Corp Twist: Your Premiums Run Through Your W-2
If you’ve elected S corp status, the rules shift. I covered the bigger choice in S corp vs LLC, but here’s the health insurance piece.
The IRS treats a more-than-2% S corp shareholder like a partner for fringe benefits. According to the IRS guidance on S corporation medical insurance, the company pays or reimburses your premiums, then reports them as wages in Box 1 of your W-2. They’re generally not subject to Social Security or Medicare tax when paid under a plan. Then you take the self-employed health insurance deduction on your personal return.
Get it wrong (paying premiums personally with no reimbursement, or leaving them off the W-2) and you can lose the deduction. Tell your payroll provider before the last payroll of the year, not in March.
What You Can’t Use (Even Though It Sounds Like You Can)
- QSEHRA and ICHRA are for employees, not you. These reimbursement arrangements are great once you hire, but sole proprietors, partners and more-than-2% S corp shareholders generally can’t use them for their own coverage.
- SHOP needs a real employee. The SHOP Marketplace for small businesses requires at least one employee other than you or your spouse. A one-person business buys on the individual Marketplace.
- Bronze isn’t automatically cheaper. Lower premiums come with higher deductibles. If you expect regular care, a silver plan can cost less over the year, and silver plans can carry extra cost-sharing reductions at lower incomes.
How to Get Health Insurance as a Self-Employed Founder: 7 Steps
- Pull your numbers. Grab last year’s Schedule C or K-1 and your year-to-date profit. HealthCare.gov’s guide to estimating self-employed income walks you through what counts.
- Estimate 2027 income honestly. Use a realistic middle number, not your best or worst month. Watch where you land against 400% FPL.
- List your doctors and prescriptions. Check each plan’s network and drug list before you look at the price.
- Compare total yearly cost. Premium times 12, plus the deductible and out-of-pocket max you’d realistically hit. Compare bronze, silver and gold side by side.
- Decide on an HSA. If you pick bronze or catastrophic for 2027, open an HSA and fund it. Contributions are deductible and grow tax-free for medical costs (see IRS Publication 969).
- Enroll by December 15 and pay the first premium. No payment, no January 1 coverage. Screenshot the confirmation.
- Update your income mid-year. Land a big deal? Report it on your Marketplace account right away so your advance credit adjusts and April doesn’t sting. Keep every premium receipt for Form 7206.
Health coverage is half of protecting the founder. The other half is your income if you can’t work, which is why I’d pair this with disability insurance for self-employed founders once your health plan is locked in.
What I’d Do This Week
If I were running a one-person business right now, I’d block 90 minutes before December 15, sit down with last year’s return and my profit-and-loss report, and treat this like a board meeting with myself. I’d compare three plans on total cost, not premium. If I were an S corp owner, I’d email my payroll provider the same day.
Freedom isn’t working for yourself. Freedom is knowing one hospital visit can’t take the business away from you.
Book the time. Make the choice. Then get back to building.
Health Insurance for Self-Employed FAQs
What is the best health insurance for self-employed people?
For most self-employed people, an ACA Marketplace plan is the best starting point. It covers pre-existing conditions, includes essential benefits and may qualify for a premium tax credit. A spouse’s employer plan can be cheaper if one is available.
When is the deadline to get health insurance for 2027?
Open enrollment runs November 1, 2026, to January 15, 2027, on HealthCare.gov. Enroll by December 15 for coverage starting January 1. Some state exchanges set different deadlines. After January 15, you need a qualifying life event.
Can I deduct health insurance premiums if I’m self-employed?
Usually, yes. You can deduct premiums for yourself, your spouse and dependents on Form 7206, up to your net self-employment earnings. You can’t deduct any month you were eligible for a subsidized employer plan, including a spouse’s.
How do S corp owners deduct health insurance?
If you own more than 2% of an S corp, the company pays or reimburses your premiums and adds them to Box 1 of your W-2. They’re generally exempt from Social Security and Medicare tax, and you deduct them personally.
Are bronze plans HSA-eligible in 2027?
Yes. Starting January 1, 2026, the IRS treats bronze and catastrophic plans as HSA-compatible, whether bought on or off the exchange. That lets more self-employed people contribute pre-tax money to a health savings account for medical costs.
This article is for general education and isn’t tax, legal or insurance advice. Plan prices, subsidies and rules vary by state and household. Confirm details on HealthCare.gov or your state exchange and talk to a licensed agent or tax professional about your situation.
How to pay yourself as a business owner comes down to your tax status: sole proprietors and single-member LLCs take an owner’s draw, S corp owners run a reasonable W-2 salary plus distributions, and C corp owners take a salary plus dividends. Whatever the structure, pay yourself a fixed amount on a fixed schedule from real profit, after you set aside taxes and an operating buffer. Then true it up every quarter.
Here’s the scene I’ve watched play out with more founders than I can count. It’s the 28th of the month. The business account says $14,200. They need rent. So they move $6,000 to personal, feel rich for a day, and then a quarterly tax bill and a software renewal land in the same week. Now they’re putting payroll on a credit card and wondering why a “profitable” business feels like a hostage situation.
The problem isn’t the business. It’s that nobody ever told them how to pay themselves like a CEO. That’s what this guide fixes.
This walkthrough from CPA Hector Garcia lays out the draw vs payroll split clearly before we get into the system I’d actually use:
Owner’s Draw vs Salary vs Distributions: What Each One Actually Is
Before you can decide how much, you have to know which door the money walks through. There are only three.
An owner’s draw is a transfer from the business to you. It isn’t a paycheck and it isn’t an expense. It just reduces your owner’s equity. No taxes are withheld, which is exactly why it feels so good and why it hurts so much in April.
A salary is W-2 wages run through payroll. Income tax, Social Security and Medicare get withheld every pay period, and the business files payroll returns. The IRS is clear that corporate officers who perform services are employees, and its Paying yourself page spells out that your wages should line up with your duties.
A distribution is profit paid to you as an owner after salary is covered. In an S corp, distributions aren’t hit with payroll taxes, which is the entire reason people elect S corp status in the first place. In a C corp, the version of this is a dividend, and it gets taxed twice.
The line I want you to remember: a draw is you raiding your company, a salary is your company paying you. Same dollars, completely different discipline.
How You Pay Yourself Depends on How You’re Taxed
Your LLC paperwork doesn’t decide this. Your tax classification does. Here’s the cheat sheet I’d tape to the wall.
| How the business is taxed | How you pay yourself | Taxes withheld? | Payroll required? | The trap |
|---|---|---|---|---|
| Sole proprietor or single-member LLC (default) | Owner’s draw | No | No | You owe income tax and 15.3% self-employment tax on all net profit, whether you take it out or not |
| Multi-member LLC or partnership | Draws and/or guaranteed payments | No | No | Draws must follow the operating agreement; guaranteed payments carry self-employment tax |
| LLC or corporation taxed as an S corp | Reasonable W-2 salary + distributions | Yes, on salary | Yes | Pay yourself too little and the IRS can reclassify distributions as wages |
| C corporation | W-2 salary + dividends | Yes, on salary | Yes | Dividends are taxed at the corporate level and again on your personal return |
That first row catches more people than any other. Taking a smaller draw does not shrink your tax bill as a sole proprietor. You’re taxed on profit, not on what you moved to your personal account. I’ve seen founders leave $40,000 “in the business to be safe” and get a tax bill on every dollar of it anyway.
The S Corp Question: When Salary Plus Distributions Makes Sense
Once profit gets real, the S corp election starts to look attractive because you only pay payroll taxes on the salary portion. I broke down when the math works, and when it doesn’t, in S corp vs LLC, so I won’t repeat the numbers here.
What matters for paying yourself is the order of operations. The IRS says an S corp has to pay reasonable compensation to a shareholder-employee before taking non-wage distributions. Salary first, distributions second. Founders who flip that order, paying themselves $12,000 in salary and $150,000 in distributions, are writing the opening paragraph of their own audit letter.
Two numbers worth knowing for 2026: the Social Security wage base is $184,500, and Medicare has no cap. If your salary is already above that base, more salary only costs you Medicare tax, which changes the conversation entirely.
How Much Should You Pay Yourself? Start With Real Profit, Not the Bank Balance
Your bank balance is the worst number in your business to pay yourself from. It includes money you owe the IRS, money you owe vendors and money a client paid you for work you haven’t done yet.
Here’s the formula I’d use instead:
Owner pay = trailing average monthly profit – tax reserve – buffer top-up
- Trailing average monthly profit: take your last 3 to 6 months of net profit and average it. One great month is a mood, not a salary.
- Tax reserve: park 25% to 30% of profit in a separate tax account. Higher-income founders in high-tax states should lean toward the top of that range or higher.
- Buffer top-up: until you have 2 to 3 months of operating expenses sitting untouched, send a slice of profit there first.
Then pay yourself the number that survives your worst recent month, not your best. A CEO’s salary doesn’t change because one client paid late. Yours shouldn’t either.
How to Pay Yourself as a Business Owner: 6 Steps
- Confirm your tax classification. Default LLC, partnership, S corp or C corp. This decides draw vs salary, so check your last return or IRS acceptance letter, not your memory.
- Separate the money into accounts. At minimum: operating, tax reserve and owner pay. When everything sits in one account, every dollar looks spendable.
- Calculate trailing profit. Run a profit and loss for the last 3 to 6 months. If your books are behind, catching them up is step zero.
- Set a base pay you can hit every month. Pick a fixed amount and a fixed date, like the 1st and 15th. For an S corp, run it through payroll. For a draw, set an automatic transfer.
- Pay estimated taxes on schedule. Draw-takers pay through quarterly estimated taxes, generally due April 15, June 15, September 15 and January 15. S corp owners can lean on withholding, but distributions can still create a balance due.
- True it up every quarter. When the tax account is funded and the buffer is full, take the excess as a bonus draw or distribution. That’s where the upside lives.
This is the system I’d hand any founder who tells me they “pay themselves when there’s money left.” There’s never money left. You have to decide it’s there first.
Pay Yourself Like a CEO, Not a Hostage
I’ve noticed a pattern with founders who never pay themselves. They call it sacrifice. It’s usually fear wearing a hoodie.
When you don’t pay yourself, three things happen. Your personal life quietly borrows from the business in chaotic ways, so the books get messy. You can’t tell whether the business actually works, because its profit is being subsidized by your unpaid labor. And you start resenting the thing you built.
A business that can’t pay its founder a modest, steady salary isn’t profitable yet. It’s a hobby with invoices. That’s not an insult, it’s information, and it’s the most useful number you’ll ever look at.
Even if the base is small, pay it. $2,000 a month on the 1st, every month, changes how you run everything else. You start pricing like someone who has to make payroll, because you do.
Common Mistakes I See When Founders Pay Themselves
- Recording draws as an expense. Draws reduce equity. They don’t reduce taxable profit, and booking them as wages in a sole proprietorship makes your profit look smaller than the IRS will say it is.
- Paying personal bills straight from the business card. It blurs the line between you and the company and turns tax season into forensic accounting.
- The $0 S corp salary. If you work in the business and take profit out, a salary of zero is a red flag, not a strategy.
- Ignoring year-end timing. December is when a bonus, a retirement contribution or an equipment purchase can change your tax bill, which is why I’d run through the year-end tax moves for a one-person business before you take a big fourth-quarter draw.
- Raising your pay after one big month. Raise your base when the trailing average proves it, not when a single invoice clears.
The Bottom Line
Pick the right door for your tax status, pay yourself from profit instead of your bank balance, fund taxes before you fund your lifestyle and put your base pay on a calendar. Then let the quarterly true-up be the reward for running a real company.
The founders I’ve seen build the calmest businesses aren’t the ones making the most money. They’re the ones who decided what they’d pay themselves before the month started.
This article is general education, not tax or legal advice. Rules depend on your entity, state and situation, so confirm your setup with a CPA or tax professional before you change how you pay yourself.
How to Pay Yourself as a Business Owner FAQs
How should a business owner pay themselves?
It depends on how the business is taxed. Sole proprietors and single-member LLCs take owner’s draws, S corp owners take a reasonable W-2 salary plus distributions, and C corp owners take a salary plus dividends, ideally on a fixed schedule.
What is the difference between an owner’s draw and a salary?
An owner’s draw is a transfer from business equity with no taxes withheld. A salary is W-2 wages run through payroll with income tax, Social Security and Medicare withheld. Your tax classification decides which one you’re allowed to use.
Is an owner’s draw taxable?
The draw itself isn’t taxed, but the profit behind it is. Sole proprietors and single-member LLC owners owe income tax and self-employment tax on all net profit, even money left in the business, so set aside taxes before drawing.
How much should I pay myself from my business?
Start with your average monthly profit over the last 3 to 6 months, set aside 25% to 30% for taxes, keep 2 to 3 months of expenses as a buffer, then pay a fixed amount your worst recent month could cover.
Can I pay myself a W-2 salary from a single-member LLC?
Not while it’s taxed by default as a sole proprietorship, because you can’t be a W-2 employee of yourself. If the LLC elects S corp or C corp tax status, you can run yourself through payroll and take a salary.
Solo 401(k) vs SEP IRA comes down to one fact: both accounts cap total 2026 contributions at $72,000, but a Solo 401(k) lets you contribute as both the employee and the employer, so you can put away far more on the same income. For most one-person businesses with no employees, the Solo 401(k) wins. A SEP IRA is the better pick when you need maximum simplicity, you have eligible employees, or you missed the December 31 Solo 401(k) setup window.
Here’s the way I explain it to founders: a SEP IRA rewards you for earning a lot. A Solo 401(k) rewards you for being a business of one. If you’re the only person on payroll, you get access to a retirement account built almost exactly for your situation, and most people never open it because their bank offered them the other one first.
If you’d rather see the math before you read mine, this breakdown from tax attorney Mat Sorensen walks through the same $100,000 income in both accounts and shows why one nearly doubles the other.
Solo 401(k) vs SEP IRA: Side-by-Side Comparison for 2026
| Solo 401(k) | SEP IRA | |
|---|---|---|
| Who it’s for | Business owners with no employees other than a spouse | Any size business, including self-employed people with employees |
| Employee deferral | Up to $24,500 in 2026 | None (only grandfathered SARSEPs allow deferrals) |
| Employer contribution | Up to 25% of W-2 pay (about 20% of net self-employment earnings for sole proprietors) | Same: up to 25% of pay (about 20% of net self-employment earnings) |
| Total 2026 cap | $72,000, plus catch-up | $72,000 |
| Catch-up (age 50+) | $8,000; $11,250 for ages 60 to 63 | None |
| Roth option | Roth deferrals widely available | Allowed by law since SECURE 2.0, but few custodians offer it |
| Loans | Allowed if the plan permits (the lesser of $50,000 or half your vested balance) | Not allowed |
| Setup deadline | Generally December 31 to make that year’s employee deferrals | Your business tax return due date, including extensions |
| Paperwork | Plan document; Form 5500-EZ once assets reach $250,000 | Form 5305-SEP or a prototype; no annual IRS filing |
| Best for | Solo founders who want to save the most, especially at $40k to $250k of profit or with a low S-corp salary | Owners with employees, or anyone who wants the simplest possible setup |
Every 2026 number in that table comes straight from the IRS: the $24,500 deferral and $8,000 catch-up, and the $72,000 cap and $360,000 compensation limit that apply to both plans.
Why the Solo 401(k) Lets You Save More on the Same Income
Both accounts share the same ceiling, so a lot of people assume they’re interchangeable. They aren’t. The difference is how fast you can reach that ceiling.
A SEP IRA has one bucket: the employer contribution. You can put in up to 25% of your W-2 pay, or roughly 20% of your net self-employment earnings if you’re a sole proprietor or single-member LLC. That’s it.
A one-participant 401(k) gives you two buckets because you wear two hats. As the employee, you can defer up to $24,500 of your earnings. As the employer, you can add the same 25% (or about 20%) profit-sharing contribution the SEP allows. Stack them together and the gap gets big quickly.
Here’s what that looks like for a sole proprietor in 2026. These are rough figures based on the IRS self-employed contribution method: net profit, minus half of self-employment tax, times about 20%, under age 50.
| Net business profit | Max SEP IRA contribution | Max Solo 401(k) contribution | Extra with Solo 401(k) |
|---|---|---|---|
| $40,000 | ~$7,400 | ~$31,900 | ~$24,500 |
| $60,000 | ~$11,150 | ~$35,650 | ~$24,500 |
| $100,000 | ~$18,600 | ~$43,100 | ~$24,500 |
| $150,000 | ~$27,900 | ~$52,400 | ~$24,500 |
| $250,000 | ~$47,000 | ~$71,500 | ~$24,500 |
| About $377,000 | $72,000 | $72,000 | $0 (both maxed) |
Look at the first row. A freelancer clearing $40,000 can shelter about four times as much in a Solo 401(k). And the Solo 401(k) hits the $72,000 cap at roughly $252,000 of profit, while the SEP needs about $377,000 to get there. If you’re 50 or older, the Solo 401(k) adds the $8,000 catch-up on top. A SEP gives you nothing extra.
Run your own numbers with the IRS worksheet for calculating your own contribution, or better, with your CPA. Your exact figure depends on your profit, your entity and your other plans.
The S-Corp Salary Trap
If your business is taxed as an S corporation, your retirement contributions are based on your W-2 salary, not your total profit. That changes the math a lot.
Say you pay yourself a $60,000 salary and take the rest as distributions. A SEP lets you put in 25% of that salary, or $15,000. A Solo 401(k) lets you put in $24,500 plus that same $15,000, for $39,500. To max out at $72,000, a SEP needs a $288,000 salary. A Solo 401(k) needs about $190,000.
That’s why low-salary S-corp owners almost always land on the Solo 401(k). It also means your deferrals have to run through real payroll, withheld from your paychecks by year-end and reported on your W-2. If you’re still paying yourself with transfers and calling it a salary, fix that first. I learned that lesson when I paid people out of my personal account and called it being lean. Retirement plans don’t forgive sloppy payroll any more than the IRS does.
One more S-corp wrinkle for 2026: if you’re 50 or older and had more than $150,000 of W-2 wages from your company in 2025, your catch-up contributions now have to go in as Roth. Sole proprietors and partners with only self-employment income aren’t subject to that rule, according to the IRS’s catch-up guidance.
When a SEP IRA Is the Smarter Choice
I’m not anti-SEP. It’s a good account in the right hands. Here’s when I’d pick it:
- You have eligible employees. A Solo 401(k) only works when the only people covered are you and your spouse. Once you hire someone who qualifies, you need a different plan. A SEP can cover employees, but you have to contribute the same percentage of pay for every eligible employee that you contribute for yourself.
- You earn a lot and want almost no admin. If your profit is well above $377,000, both accounts max out at $72,000, and a SEP’s simplicity starts to look better.
- You missed the December 31 window. You can open a SEP and fund it all the way up to your tax filing deadline, including extensions. That makes it the classic “I forgot” account.
- Your income swings a lot. SEP contributions are fully discretionary. You can put in nothing in a bad year and the max in a great one.
One trade-off people miss: a SEP IRA balance counts in the pro-rata calculation if you ever do a backdoor Roth IRA conversion. A Solo 401(k) balance doesn’t. If backdoor Roth contributions are part of your plan, talk to your tax pro before you put a big balance into a SEP.
The December 31 Deadline Most Founders Miss
This is why I’m writing about retirement accounts in November and not in April.
To make 2026 employee deferrals, you should have your Solo 401(k) plan adopted by December 31, 2026, and make your deferral election by then. That’s the rule for anyone paying themselves W-2 wages through an S corp, and it’s the safe deadline for everyone else. Once the plan exists, you generally have until your tax filing deadline to actually deposit the money.
There’s one exception worth knowing. Under SECURE 2.0, a sole proprietor or single-member LLC with no employees can adopt a brand-new Solo 401(k) after year-end and still make employee deferrals for the first year, as long as the deferrals are made by the tax return due date without extensions, which is April 15 for most people. That’s helpful if you’re late, but not every provider supports it. Don’t build your plan on it.
A SEP is more forgiving. According to IRS Publication 560, you can set it up and fund it as late as your business tax return due date, including extensions. With an extension, that can push 2026 SEP contributions to September or October 2027, depending on your entity.
Retirement is one of several things you have to decide before the calendar flips. I covered the rest, from equipment timing to estimated payments, in the year-end tax moves every one-person business should make before December 31.
How to Choose Between a Solo 401(k) and a SEP IRA: 6 Steps
- Confirm who’s on your team. If anyone other than you and your spouse works enough hours to be eligible, a Solo 401(k) is off the table. Look at a SEP, SIMPLE IRA or standard 401(k).
- Find the right income number. Sole proprietors use net profit minus half of self-employment tax. S-corp owners use W-2 salary only.
- Run both contributions. SEP: about 20% of net self-employment earnings (or 25% of W-2 pay). Solo 401(k): that same amount plus up to $24,500, plus catch-up if you’re 50 or older.
- Decide on Roth vs pre-tax. If you want Roth dollars or 401(k) loan access, the Solo 401(k) is the practical choice.
- Check the calendar. Before December 31: open the Solo 401(k) if it wins. After December 31: a SEP may be your only option for 2026, unless you qualify for the first-year sole-proprietor exception.
- Bring it to a pro, then open the account. Choose a provider, sign the plan document, set up deferrals through payroll if you’re an S corp, and set a reminder for Form 5500-EZ once assets reach $250,000.
Common Mistakes I See With Solo 401(k)s and SEPs
- Opening a SEP by default. The bank offered it, so you took it. You may be leaving $24,500 a year of contribution room on the table.
- Using profit instead of W-2 pay as an S-corp owner. Your contribution is based on your salary. Distributions don’t count.
- Doubling up on the deferral. The $24,500 employee limit is per person across all 401(k)s. If you also have a day job with a 401(k), your Solo deferrals share that limit.
- Hiring without checking the plan. A first employee can end your Solo 401(k) eligibility. Talk to your provider before the offer letter goes out.
- Forgetting the 5500-EZ. Once a Solo 401(k) reaches $250,000, an annual filing is required. Missing it can bring steep penalties.
The Bottom Line
If you’re a business of one, a Solo 401(k) is usually the strongest retirement account available to you. You can save more on less income, you get catch-up room and a real Roth option, and you can borrow from it in an emergency. A SEP IRA earns its place when you have employees, when your profit is high enough that both accounts max out, or when the calendar has already made the decision for you.
Your business already pays you. Make sure it pays your future self too, and pick the account before December 31 picks it for you.
This article is educational and isn’t personal tax, legal or financial advice. Contribution limits, entity type and your own situation all matter. Talk to a CPA, enrolled agent or fiduciary financial adviser before you open or fund a retirement plan.
Solo 401(k) vs SEP IRA FAQs
Which is better for a one-person business, a Solo 401(k) or a SEP IRA?
For most owners with no employees, a Solo 401(k). It allows a $24,500 employee deferral on top of the same employer contribution a SEP allows, plus catch-up contributions, Roth deferrals and loans. A SEP is simpler and fits businesses with employees.
What are the 2026 contribution limits for a Solo 401(k) and SEP IRA?
Both cap total contributions at $72,000 for 2026. A Solo 401(k) adds an $8,000 catch-up at age 50 or older, or $11,250 at ages 60 to 63. A SEP has no catch-up contribution.
When is the deadline to open a Solo 401(k) for 2026?
Generally December 31, 2026, to make 2026 employee deferrals. Sole proprietors with no employees opening their first plan may adopt it by their tax filing deadline without extensions. A SEP can be opened until the return due date, including extensions.
Can I have both a Solo 401(k) and a SEP IRA?
Sometimes, but contributions from the same business share one $72,000 limit, and you can’t use the IRS model SEP form if you also maintain another retirement plan. Most solo founders pick one account. Check with your provider and tax pro first.
Does a SEP IRA allow Roth contributions?
SECURE 2.0 allows Roth SEP contributions, but many custodians still don’t offer them. SEPs also don’t allow employee deferrals. If Roth savings matter to you, a Solo 401(k) with a Roth option is usually the practical choice.

Estate Planning for Business Owners: The Checklist That Keeps Your Company Alive Without You

1031 Exchange Rules: How Real Estate Investors Keep Growing Without Paying the Tax Bill

Success Is Not a Solo Journey: Why Entrepreneurs Grow Faster Through the Right Connections

QSBS Explained: The $15 Million Tax Break Most Founders Don’t Plan For

The R&D Tax Credit for Startups: How to Turn Your Payroll Into Cash Back
5 Ways For Startups To Succeed Making Acquisitions

77 Inspirational Quotes That Will Change Your Life
57 Memorable Kobe Bryant Quotes

Motivational Picture Quotes: 52 Images to Inspire a Successful Year
40 Rare Motivational and Inspirational Picture Quotes
3 Prince EA Videos To Change Humanities Path To Greatness
(Video) What Is Success? An Entrepreneurial Story To Inspire You
(Inspirational Video) What If Today You Knew You Were Going To Take Your Last Breath?
How To Make Enough Money From A Blog To Quit Your Job – Kate McKibbin
How Finding Your Passion And Becoming An Entrepreneur Can Lead To Happiness – Chiquita Searle
-

 Did You Know1 year ago
7 Surprising Life Lessons Video Games Taught Me That School Never Did
-
 Life2 years ago
The 5 Stages of a Quarter-Life Crisis & What You Can Do
-
 Success Advice1 year ago
Stephen Covey’s 8 Leadership Habits That Will Change How You Lead Forever
-

 Featured2 years ago
The Psychology of Motivation: How to Keep Moving Forward Every Day
-

 Life1 year ago
How to Stop the War in Your Head and Find Peace
-
 Personal Development1 year ago
The Three-Second Pause That Changes How People Perceive You
-
 Explode Your Social Media1 year ago
Want More Views? Master These 6 YouTube Growth Tactics
-
 Change Your Mindset1 year ago
You Become What You Absorb: How Input Shapes Your Life