Wealth
Injured and Unable to Work in California: How to Protect Your Income During a Rosemead Claim

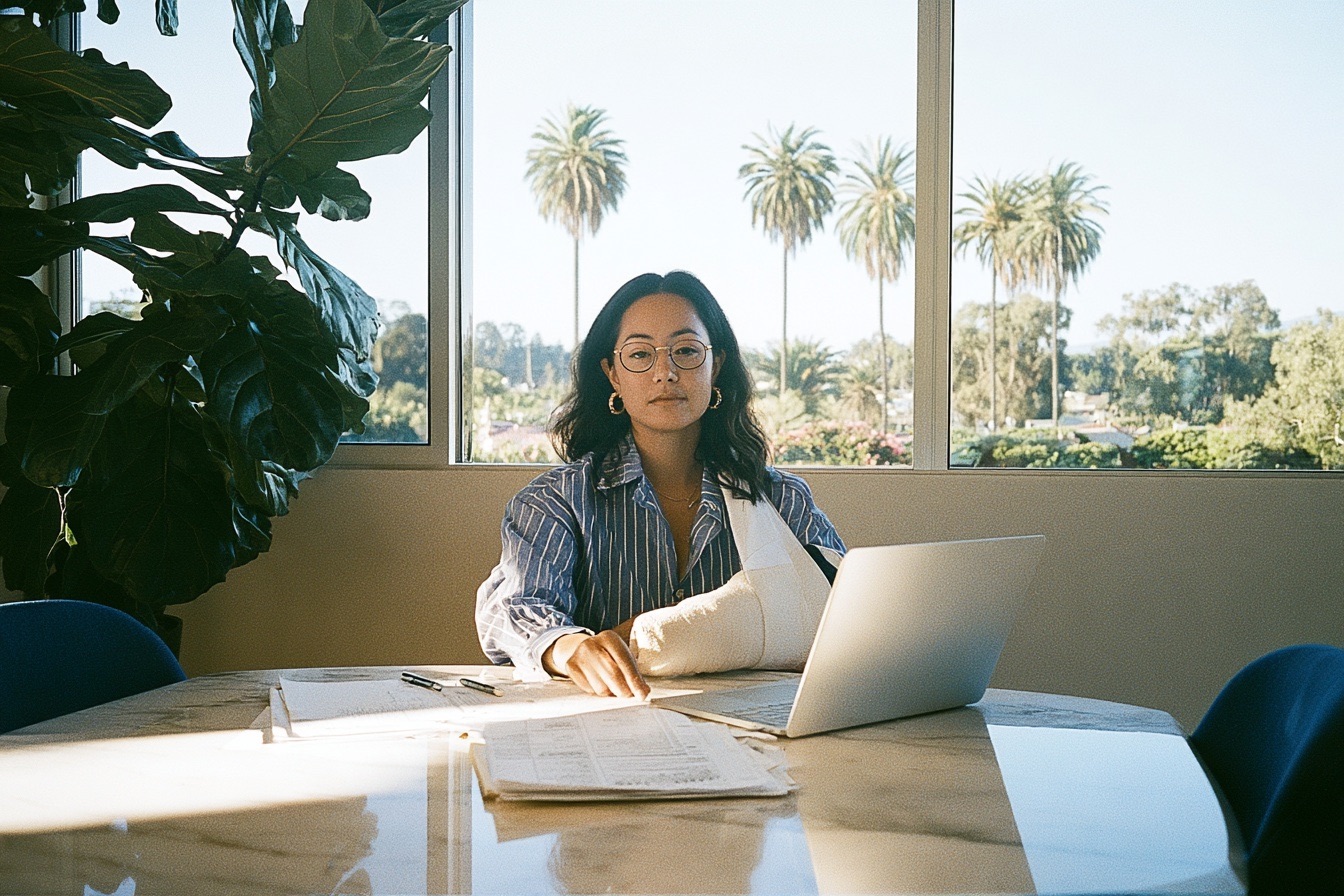
The injury is the event everyone focuses on. The income problem is the one that actually reshapes a life, and it arrives on a schedule nobody plans for: roughly three weeks in, when the first missed paycheck lands and the medical bills start arriving at the same address.
A personal injury claim is designed to make that whole eventually. Eventually is the difficult word. Most claims resolve in months or years, and rent is monthly. Managing the interval is a separate skill from pursuing the claim, and it is the part people are least prepared for.
Understand What the Claim Will Eventually Cover
Knowing what is recoverable changes what you should be documenting from the first week.
The measure is broader than medical bills
Civil Code section 3333 provides that for the breach of an obligation not arising from contract, damages are the amount that will compensate for all the detriment proximately caused, whether it could have been anticipated or not.
That reaches past treatment costs. Lost wages during recovery, and lost earning capacity where the injury permanently changes what work you can do, both sit inside it.
Earning capacity is not the same as lost wages
Lost wages are arithmetic: hours missed, times rate. Loss of earning capacity is a projection about a changed future, and it is frequently the larger number for anyone doing physical work or approaching a promotion.
Self-employed people and contractors are systematically underpaid on this, because their loss shows up as declined work and canceled jobs rather than as absent paystubs. Keep the emails where you turned work down. That correspondence is the evidence.
The Income Sources That Bridge the Gap
Waiting for a settlement is not a financial plan. Several things are available now.
State Disability Insurance
If you paid into it through payroll deductions, California’s State Disability Insurance program provides partial wage replacement for an eligible worker unable to work because of a non-work-related illness or injury.
That last qualifier matters. A car accident on your own time is generally non-work-related, which places it inside the program. An injury at work runs through workers’ compensation instead.
Apply early. There is a certification step involving your treating provider, and the processing time is the reason most people receive their first payment far later than they expected.
Paid sick leave
Labor Code section 246 entitles an employee who works in California for the same employer for 30 or more days within a year of starting to paid sick days as specified in the section.
It is a smaller pot than people need but it is immediate, and it covers the early appointments before anything else has been approved.
Check the coverage you already bought
Medical payments coverage on an auto policy pays treatment costs regardless of fault and pays quickly. Many people carry it without knowing.
Short-term disability through an employer, credit card payment protection and loan deferment programs are all worth checking in the first fortnight. None of them are generous, and collectively they often cover the gap that matters most.
Be careful about the coordination
Disability benefits, health insurance payments and any eventual settlement interact. Health plans and some benefit programs may assert a right to be repaid out of a recovery.
Do not assume money received now is money kept. Track every benefit received and from whom, because that ledger has to be reconciled at the end.
Protect the Claim While You Manage the Month
Financial pressure produces decisions that quietly reduce what the claim is worth.
Gaps in treatment are expensive
Missing appointments because of cost, transport or work is read by an adjuster as evidence that the injury resolved. A three-week gap in the records is one of the most commonly used arguments against a claim.
If cost is the obstacle, say so to the provider rather than disappearing. Arrangements exist, and a documented financial reason is very different from an unexplained absence.
Do not take the first offer because the rent is due
Early offers are frequently made precisely because the injured person is under pressure and has not yet finished treating. Accepting before the medical picture is complete forfeits everything discovered afterward, and the release is final.
Keep a plain record
A simple log of missed days, canceled work, appointments attended and what you could not do at home is worth a surprising amount. Memory compresses months into an impression, and an impression does not persuade an adjuster.
Write it as you go rather than reconstructing it later. Two lines a day is enough, and the contemporaneous record carries weight that a summary written a year afterward never will.
Social media is read by the other side
Adjusters look. A photograph at a family event, a comment about a good day, or a tagged post from a hike months earlier gets used without any of the surrounding context.
None of this requires you to disappear. It requires you to assume everything posted will be read by someone looking for a reason to pay less.
Talk to Your Employer Earlier Than Feels Comfortable
Most people delay this conversation and it costs them. An employer told at the outset can often adjust duties, approve leave properly and keep benefits running. An employer left to infer things from absences frequently starts a different process.
Get restrictions in writing from the treating provider and provide them, rather than describing the limits verbally. Written restrictions protect both the job and the claim, since they document what the injury actually prevented.
Where the income gap is the urgent problem rather than the injury itself, that is worth raising at the first meeting. Personal injury lawyers in Rosemead, CA deal with the cash flow question constantly, and the available options narrow considerably once a claim has already been settled.








Key Highlights
- A Tesla with a novated lease can reduce your taxable income through salary packaging and make lease payments easier to budget.
- Eligible electric vehicle models may qualify for an FBT exemption, which can improve your overall cost.
- Most lease packages can include running costs like charging, insurance, maintenance, and roadside assistance.
- Your employer, you, and a lease provider all play a role in setting up the lease agreement.
- The right fit depends on your financial situation, lease term, and the purchase price of the Tesla model.
- A novated lease calculator helps you estimate monthly payments before you commit.
Introduction
Considering a Tesla with a novated lease but unsure about affordability? You are not alone. The purchase price of a Tesla is an important factor to consider when assessing affordability. A novated lease lets you pay through your salary, potentially improving cash flow and tax benefits. The key question: Is it better for your finances than buying outright?
Understanding Tesla Novated Lease Options in Australia
In a novated lease in Australia, you choose a Tesla with a novated lease and sign an agreement with a lease provider for a fixed term. Instead of paying the full price upfront, you make lease payments over time through salary packaging, and it’s important to consider interest rates associated with the lease.
This can make electric cars more affordable. Eligible EVs may also receive tax benefits, making novated leasing more attractive compared to many petrol cars. Here’s how it works:
What Is a Novated Lease and How Does It Work for Teslas?
A novated lease is a three-way agreement between you, your employer, and a lease provider. You choose a Tesla model, and it’s financed over a set term—usually one to five years.
Your employer typically deducts the novated lease costs through salary packaging, which may include both pre-tax and after-tax contributions for the vehicle and eligible running costs. This setup can lower your taxable income and reduce your tax bill, which in turn affects the tax you pay each pay cycle.
The Role of Salary Sacrifice in Novated Leasing
Salary packaging is central to novated leasing. Instead of paying vehicle costs from your after-tax income, your employer deducts lease payments from your pre-tax salary, lowering your taxable income.
This can help if you’re managing a tight budget—fixed deductions make expenses predictable and simplify planning. For some households, this frees up money for other needs.
Eligibility Criteria for a Tesla Novated Lease
Not every worker or vehicle setup will qualify in the same way, so it is smart to check the basics early. A lease provider will usually look at your employment setup, the lease agreement terms, and whether salary packaging is available through your employer to access the latest technology.
Your financial situation also matters because you need to support the lease term and ongoing deductions, especially at the time of writing. If you are comparing novated lease offers for a Tesla model, focus on eligibility before you get too far into pricing.
Requirements for Employees and Employers
To use salary packaging, your employer must support payroll deductions; otherwise, a novated lease isn’t possible. You should also be comfortable with the lease terms and ensure your income can cover regular pre-tax deductions.
Approval depends on factors such as your employer’s salary-packaging arrangements, the lease terms, and your ability to meet the required repayments. In reality, it depends on whether your employer can handle the setup and if your finances can sustain fixed deductions, which can affect your income tax obligations.
Can You Lease Used Teslas with a Novated Lease?
The information focuses on new Tesla models like the Model 3 and Model Y, but also covers used cars. Check with your lease provider about available novated lease options in Australia.
A used Tesla may have lower lease costs, but its eligibility for tax benefits depends on the vehicle and the specific requirements that apply to the novated lease.
If considering a used Tesla, check with the lease provider whether the vehicle is eligible for a novated lease and separately confirm whether any applicable tax benefits are available.
Exploring Tesla Models Available for Novated Lease
For many buyers, the main question is: which Tesla model is available? The Model 3 and Model Y are the most popular EV novated lease options.
Both are accessible through novated lease providers. When comparing packages in Australia, your best choice depends on cost, features, and how each model fits your budget.
Comparing Tesla Models for Lease Suitability
Choosing the right Tesla for a novated lease involves considering the vehicle’s price, running costs, practicality, and how well it fits your needs over the lease term.
A quick comparison can narrow your options. The Model 3 and Model Y are popular choices, with the Model Y RWD often searched as a specific variant.
| Tesla Model | Lease Suitability Notes |
| Model 3 | Ideal for drivers seeking new cars, tax savings, and predictable regular payments. |
| Model Y | Great for those needing more space and meeting EV criteria; a common leasing option. |
| Model Y RWD | A frequently compared version if you want to evaluate lease costs within the same model line. |
The Tesla Novated Lease Process Step-by-Step
If the idea appeals to you, the next step is understanding the order flow. The process is straightforward, and knowing each stage can make a novated lease less intimidating.
Typically, you choose a vehicle, work with a lease provider, complete the agreement, and get financial approval before delivery. Using a novated lease calculator early on helps estimate affordability before starting the paperwork.
Ordering Your Tesla Through a Lease Provider
First, choose your Tesla model and confirm the vehicle you want. Compare novated lease offers and see how the sale price impacts your package.
Next, the lease provider structures your arrangement, including the car and any optional running costs. The goal is a clear payment plan, so you’re never left guessing.
Documentation and Financial Approval
Once you select a vehicle, the paperwork starts. You will need a lease agreement between you, your employer, and the provider to ensure correct salary deductions.
Financial approval confirms affordability. While a novated lease calculator offers an estimate, approval verifies that lease payments suit your income and payroll.
Financial Benefits of Leasing a Tesla via Novated Lease
For many drivers, the strongest reason to consider this option is the money side. A novated lease can combine tax savings, salary packaging, and bundled running costs in a way that changes the overall cost of driving a Tesla.
That does not mean it is automatically right for everyone. Still, when fringe benefits rules and government incentives line up for eligible EVs, the numbers may look far better than expected. Here is where those savings usually show up.
Tax Advantages and FBT Exemptions
Leasing a Tesla through a novated lease can offer tax benefits, notably the FBT exemption for eligible electric vehicles, which can significantly increase savings.
However, federal rules are specific. Eligibility for the EV FBT exemption depends on specific requirements, including the vehicle type and its value in relation to the relevant luxury car tax threshold.
Calculating Your Monthly Lease Cost
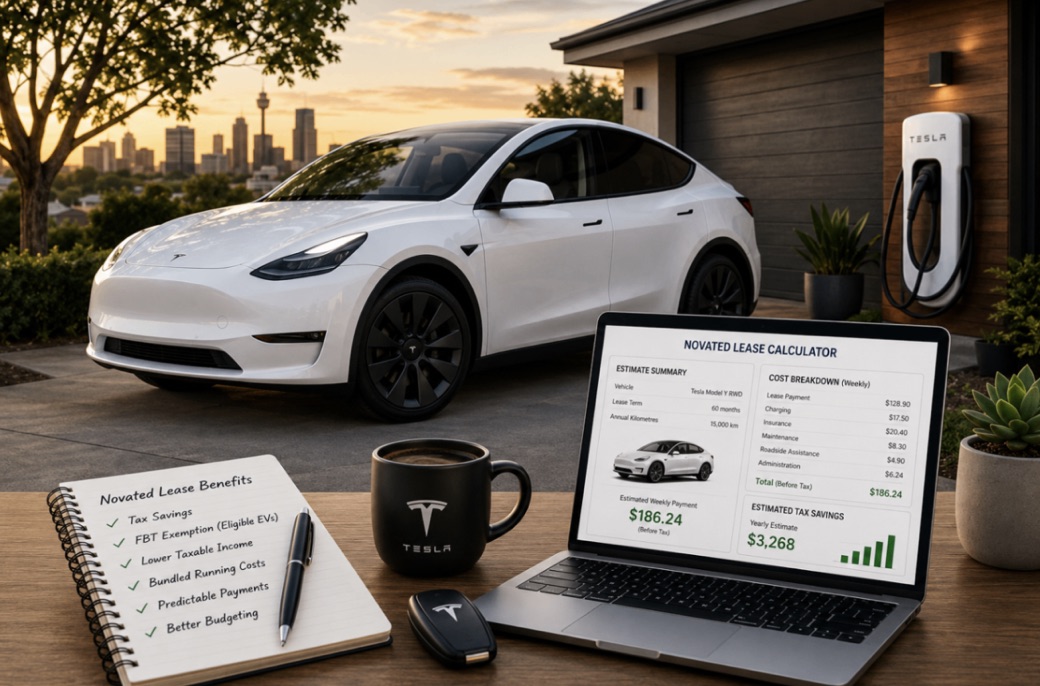
A novated lease calculator estimates your monthly payments based on the vehicle cost and package structure. It helps you gauge overall costs before applying.
Your exact payment depends on the lease details and term length; shorter terms or added costs may increase monthly payments.
Salary Packaging Scenarios Explained
The main pros and cons of a Tesla novated lease come down to structure. The upside is that salary packaging can reduce taxable income and simplify vehicle budgeting, making it an attractive option for many. The trade-off is that the arrangement still needs to suit your personal circumstances.
Managing Ongoing Expenses with a Tesla Novated Lease
Budgeting for the car is just the beginning. You also need to consider ongoing driving expenses.
A well-structured novated lease can cover selected running costs, turning unpredictable bills into regular payments. For Tesla drivers, this often includes charging, insurance, maintenance, and roadside assistance.
Included Running Costs: Charging, Maintenance, Insurance
A key benefit of a novated lease is bundling running costs into one plan, reducing bill shock and making budgeting easier.
This is especially useful for Tesla buyers, who often overlook day-to-day expenses. Including these costs in your lease makes ownership more predictable.
Made with AI
Conclusion
A Tesla novated lease may offer tax and budgeting benefits, depending on your individual financial circumstances and eligibility. By understanding salary sacrifice, eligibility, and ongoing costs, you can make an informed decision. Enjoy tax advantages and bundled expenses for greater convenience and potential savings. Ready to learn more? Get a free consultation to see if a novated lease fits your financial goals.
Frequently Asked Questions
Is it worth getting a Tesla on a novated lease in Australia?
A novated lease can be worthwhile if it lowers your taxable income, offers predictable payments, and fits your finances. For eligible Tesla models, tax savings on electric cars can make this option more affordable than many expect.
What ongoing costs are covered under a Tesla novated lease?
A Tesla novated lease can cover running costs like charging, maintenance, insurance, and roadside assistance. Bundling these into your lease payments gives you a clearer monthly budget and reduces separate car-related bills.
Are there tax benefits to leasing a Tesla through a novated lease?
Yes. The main tax benefits of novated leasing are salary packaging and, for eligible EVs, possible FBT exemption. If the Tesla qualifies, avoiding fringe benefits tax can significantly increase the lease’s value.
Key Highlights
- A novated lease with Leaselab lets you choose your car and package lease payments through your pay cycle.
- The novated lease calculator helps estimate vehicle costs, running costs and likely tax savings.
- Leaselab offers flexible leasing plans for new and used cars, including electric vehicles.
- Fixed payments can reduce surprises and make budgeting easier than with many lease providers.
- GST savings and lower taxable income can make the overall cost more manageable.
Introduction
Choosing the right novated lease with Leaselab can save you money, but it also needs to feel clear and practical. That is why many drivers look past flashy offers and focus on how novated leasing actually works, what the terms of service mean, and how their personal information is handled before they commit.
Understanding Novated Leasing with Leaselab
A novated lease with Leaselab is a three-way arrangement between you, your employer and a finance company. You choose the car, sign a lease agreement, and your employer makes payments from your salary before tax.
In simple terms, it works like a car loan with tax advantages built in. Your lease term is usually one to five years, and the setup is designed to make novated leasing easier to understand. That matters when you are comparing any provider.
What makes a novated lease with Leaselab unique?
What stands out is the focus on explaining complex financial products in plain English. Instead of leaving you to decode fine print, Leaselab says it aims to educate drivers from quote to end of lease so decisions are made in your best interests.
That approach can be a good fit if you want clarity before signing. It also helps if this is your first novated lease and you want fewer surprises later.
- Clear guidance on how the lease works
- Full transparency from quote to lease end
- Flexibility based on your situation
Step-by-step overview: How the Leaselab novated lease process works
Here is the short answer: you pick a car, agree to a lease agreement, and the lease payments are taken through your pay cycle before tax. That is the core lease process.
Next, your running costs can be bundled into regular payments, which makes budgeting simpler month to month. If you change to a new employer, the arrangement may need to be set up again through payroll.
- Choose your car and lease term.
- Set repayments through your salary.
- Review options at the end of your lease
At the end of your lease, you can usually pay the residual, refinance or upgrade.
Exploring Leaselab’s Novated Lease Plans for Drivers
Leaselab’s leasing plans are built around choice. Drivers can look at new cars, used cars and electric options, then match the lease agreement to their budget and expected vehicle usage.
That flexibility matters because one plan does not suit everyone. Before you sign, it is worth checking the terms of service, lease length and how the package fits your day-to-day driving.
Vehicle choice and flexibility in Leaselab’s leasing options
One useful feature is broad vehicle choice. You are not locked into one type of car, so your leasing plans can reflect what you actually need, whether that is a used car for value or a new car for longer-term ownership.
The best part for many drivers is being able to compare practical examples. You might look at a Kia on a novated lease for family use, a Ford Ranger novated lease for work needs, or a novated lease Tesla Model Y if you want lower fuel spend.
- New and used car options
- Access to wholesale pricing
- Choice based on your budget
As always, share personal information carefully and review the quote details.
Electric and eco-friendly vehicle support through novated leases
If you want to lease an electric car, this is where the numbers can get interesting. Leaselab highlights that electric vehicles may deliver strong tax savings, especially where the fringe benefits tax exemption applies to eligible EVs.
That can make an EV novated lease more affordable than many people expect. A Tesla novated lease or BYD novated lease may end up closer in cost to a cheaper petrol car once tax and GST savings are counted.
- EVs may qualify for valuable fringe benefits tax relief
- Running costs can be bundled with roadside assistance
Use the calculator to test different EV scenarios before choosing.
Using Leaselab’s Novated Lease Calculator Effectively
The novated lease calculator is there to answer a basic question: what will this car really cost me? It helps you estimate vehicle costs, lease payments, running costs and possible tax savings based on salary and car choice.
That makes it easier to compare options before you apply. Instead of guessing your tax bill, you can test lease lengths, vehicles and budgets in a more practical way.
How to estimate your savings with Leaselab’s online calculator
Start with your salary and preferred car. Then add likely running costs so the online calculator can show a more realistic estimate than a simple car loan comparison. This is useful when comparing lease providers.
A good approach is to use your historical usage. If you know your usual fuel, servicing and tyre spend, your estimate will be closer to a predictable payment.
|
Input |
What it helps show |
|
Salary |
Potential tax savings and effect on taxable income |
|
Vehicle choice |
Purchase price, GST impact and lease payments |
|
Lease term |
How monthly costs change over time |
|
Running costs |
A fuller estimate of total package cost |
Example: Breaking down a real-life novated lease cost scenario
Take a simple lease case. Say you choose a new car with a purchase price of $50,000 and include fuel, servicing and tyres. The novated lease cost is not just the sticker price, because GST and tax treatment affect total vehicle expenditure.
Then check the residual value at the end. A shorter lease may mean higher regular payments, while a longer term spreads costs more evenly.
- Compare the total package, not just the monthly number
- Check what running costs are included in the quote
That is the fairest way to assess one offer against another.
Real Experiences: Insights from Leaselab Novated Lease Customers
Real experiences often come down to two things: did the savings make sense, and was the process easy to follow? In customer reviews, those points matter more than marketing language.
For many drivers, the value of novated lease packages sits in clear lease management and knowing whether they want a fully covered plan or a simpler setup with fewer bundled costs.
Positive highlights: What drivers appreciate about Leaselab
Drivers often like having fixed car payments and a clearer view of tax benefits. For someone moving from a normal finance setup, that can feel like a real game changer because the lease agreement bundles more of the ownership costs into one structure.
The best part is not just lower tax. It is knowing what you are likely to pay each month and having options at lease end.
- Fixed monthly budgeting
- Clearer view of savings versus normal buying
That practical side is what many people value most.
Addressing common client concerns and transparent communication
A common concern is bill shock. People worry that a lease quote looks good upfront, then hidden costs appear later. That is why transparent communication matters when comparing lease providers.
You should look closely at important information such as the terms of service, lease inclusions, residual amount and what happens if your job changes. These are the details that shape the real cost.
- Ask what is included in the packaged payment
- Confirm what happens at the end of the lease
Those questions help you avoid confusion before signing.
Conclusion
In conclusion, choosing a novated lease with Leaselab presents numerous advantages that set it apart from other providers. With unique flexibility tailored to individual needs, a transparent leasing process, and a commitment to eco-friendly vehicle options, Leaselab has cultivated a reputation for customer satisfaction. Clients appreciate the ease of use offered by Leaselab’s online calculator and the practical insights shared by existing customers. As you weigh your options, consider how Leaselab’s offerings align with your driving requirements and financial goals. If you’re ready to explore your possibilities and gain a clearer understanding of your savings, book a free consultation with our experts today!
Frequently Asked Questions
How does Leaselab compare to other novated lease providers in Australia?
Leaselab positions itself as a novated leasing provider focused on education, transparency and flexible lease management. When you compare options, look at competitive pricing, the lease agreement details, support quality and the terms of service rather than the headline payment alone.
What factors should be considered before signing up with Leaselab?
Check the terms of service, your lease term, the residual amount and how the package fits your unique circumstances. It is also wise to review how your personal information is handled and whether the structure is truly in your best interests.
Is a novated lease with Leaselab really worth it?
A novated lease can be worth it if the tax savings outweigh the setup and your running costs suit the package. It is a good fit when fixed lease payments, GST savings and salary packaging leave you better off than buying the car normally.
Build good money habits early and you buy yourself options later. Once saving and spending reviews become routine, life getting expensive doesn’t mean starting over, whether the trigger is a missed shift at work or a surprise dental bill.
Each habit below pairs a repeatable action with Canadian financial products, from the KOHO High Interest Savings Account to budgeting software and online training for your next professional project.
|
Habit |
Why it compounds |
First move |
|
Build an emergency fund |
Prevents an unexpected bill from disrupting larger goals |
Automate a transfer after payday |
|
Makes saving a default expense |
Choose a fixed amount or percentage |
|
|
Track spending |
Reveals recurring leaks and changing priorities |
Review the last 30 days |
|
Control lifestyle creep |
Preserves part of every raise |
Save a portion of new income |
|
Pay down costly debt |
Reduces interest working against you |
Target the highest rate |
|
Invest consistently |
Gives long-term contributions more time |
Schedule a manageable contribution |
|
Use sinking funds |
Turns predictable costs into planned expenses |
Create one fund for the next irregular bill |
|
Protect payment history |
Reduces late fees and credit damage |
Automate minimum payments |
|
Invest in useful skills |
Can improve earning power and adaptability |
Choose one measurable skill |
|
Review goals regularly |
Keeps the plan aligned with real life |
Schedule a quarterly review |
What makes these habits stick
None of this requires a large income. A demanding plan asks a lot of someone who’s already tired after work; a simple one asks for fewer weekly decisions. So pick an affordable amount, tie it to a trigger you can count on, and let progress happen on its own instead of renegotiating every transfer each time a bill lands in your inbox.
Still, products can’t replace a workable plan. Look into eligibility, fees, and access rules. And check current rates and terms before you open anything.
1. Build an emergency fund
Keep emergency money separate from the everyday spending account, somewhere accessible like a high-interest savings account. Set up contributions to go out automatically after payday, and top the fund back up after any withdrawal. Your starter cushion can come before investing.
The Financial Consumer Agency of Canada recommends working toward three to six months of regular expenses. That number intimidates people, so start smaller. A good first target is a plausible urgent cost, say replacing a broken refrigerator.
The KOHO High Interest Savings Account is a simple place to build that cushion. Interest runs up to 3.5%, calculated daily and paid monthly, and there’s no minimum balance, so the money earns something while it sits there waiting for the day you need it.
Its automated savings features nudge small amounts toward a goal and round up eligible purchases, dropping the difference into savings. Earn Interest is something you opt into within the app. Whatever account you’re considering, read the current plan, rate, terms, and deposit-protection details before opening it.
|
KOHO savings snapshot |
Details |
|
Best fit |
Accessible emergency savings |
|
Habit tools |
Goal transfers and RoundUps |
|
Check first |
Plan terms and deposit protection |
2. Pay yourself first
Saving whatever’s left at month-end is unpredictable. So don’t wait for leftovers. Move a fixed amount or percentage out shortly after income arrives, and saving becomes a default expense rather than a hope.
With Tangerine’s Automatic Savings Program, recurring transfers run on a schedule toward named savings goals. Bump your contribution up after a raise, or once a bill is paid off. You might start by moving $25 every payday.
|
Tangerine snapshot |
Details |
|
Product |
Savings accounts and Automatic Savings Program |
|
Habit support |
Scheduled transfers toward named goals |
|
Check first |
Eligibility and current account terms |
3. Track where your money goes
Review 30 days of transactions for awareness, not guilt. Group commitments separately from flexible spending and goals. Does that expense still match what you care about? If not, that’s your first cut.
YNAB assigns available money to categories and imports transactions from supported institutions. Schedule a brief weekly check rather than monitoring constantly. Sunday evening works for most people.
|
YNAB snapshot |
Details |
|
Product |
Subscription budgeting app |
|
Habit support |
Category planning and transaction imports |
|
Check first |
Subscription cost and hands-on upkeep |
4. Control lifestyle creep
Decide before a raise how much extra take-home pay you’ll spend, then route the remainder toward savings or debt. Enjoy some of it. You should.
Scotiabank’s Pay Yourself First and Savings Finder tools can automate saving within its banking ecosystem. There’s no universal percentage here. Just choose your split before you commit to a larger car payment.
|
Scotiabank snapshot |
Details |
|
Tools |
Pay Yourself First and Savings Finder |
|
Habit support |
Automatic movement toward savings |
|
Check first |
Account requirements and transaction terms |
5. Prioritize expensive debt
High-interest balances cancel out progress everywhere else. Make every required payment while keeping a modest buffer, then direct extra money at the highest-rate balance. The snowball alternative targets smaller balances first, for motivation; pick whichever you’ll actually finish.
Existing TD customers could park that buffer in a personal savings account. It isn’t a debt-payoff product.
|
TD snapshot |
Details |
|
Product family |
Personal savings accounts |
|
Habit support |
Separates a small cash buffer |
|
Limitation |
Doesn’t replace a debt repayment strategy |
6. Invest consistently
Recurring contributions stop you from waiting for a perfect market entry that never arrives. Wealthsimple offers managed portfolios and self-directed investing; neither suits everyone, and investments can lose value.
Keep emergency cash accessible and out of short-term market swings. Before investing, weigh diversification, risk, and fees, and check the tax treatment and contribution rules for the account you choose.
|
Wealthsimple snapshot |
Details |
|
Options |
Managed and self-directed accounts |
|
Habit support |
Recurring digital contributions |
|
Check first |
Investment risk and account rules |
7. Prepare for irregular costs
A sinking fund reserves money gradually for known expenses: annual insurance, gifts, car repairs. Emergency funds are for genuinely unexpected needs. The distinction matters.
Divide a $600 annual bill into $50 monthly deposits and it stops being an emergency at all. BMO savings accounts can separate planned expenses, and its U.S. banking platform offers digital Savings Goals for tracking progress.
|
BMO snapshot |
Details |
|
Products |
Savings accounts; U.S. digital goals |
|
Habit support |
Organizes money for known costs |
|
Check first |
Local features and transaction charges |
8. Protect your payment history
Automate at least the minimum payments and keep the payment account funded. Review statements monthly for duplicate charges, price increases, and payment errors, and set alerts a few days before large withdrawals.
A wide screenshot of KOHO’s homepage hero section featuring a purple KOHO payment card on a restaurant bill. Image: KOHO
Existing RBC clients might use High Interest eSavings as a linked reserve rather than for frequent bill payments.
|
RBC snapshot |
Details |
|
Product |
High Interest eSavings |
|
Habit support |
Backup cash separate from bill money |
|
Check first |
Transfer timing and transaction fees |
9. Invest in useful skills
Choose training tied to a certification or a portfolio project with a real deliverable. Coursera offers individual courses and Professional Certificates alongside Specializations and degrees through university and industry partners.
Skills strengthen financial resilience, but a course doesn’t guarantee a raise. Compare total cost and workload against the credential’s practical value before you pay for the certificate.
|
Coursera snapshot |
Details |
|
Product |
Online learning platform |
|
Habit support |
Structured training toward defined outcomes |
|
Check first |
Prerequisites and credential relevance |
10. Review goals quarterly
Review reserves, debt, recurring contributions, and near-term priorities together. EQ Bank’s Savings Plus Account lets you monitor accessible savings and schedule money movement, but an account review isn’t a complete financial-plan review.
Changing a target after a shift in housing costs or family responsibilities isn’t a failure. It’s the review working. Put the next one on your calendar.
|
EQ Bank snapshot |
Details |
|
Product |
Savings Plus Account |
|
Habit support |
Digital savings monitoring and transfers |
|
Check first |
Current terms and access methods |
Build a system you can repeat
Your financial products should support decisions you’ve already made, not create another project to manage. The useful habit is the one you can afford to repeat through a busy month.
Make the action automatic where possible, and give yourself a regular chance to adjust it. You don’t need every provider listed here or a complete overhaul. Pick one habit today, and schedule its first transfer or review before the week ends.

There were months when the site was doing fine and I still walked around feeling behind, which is a strange combination until you live it. The money came in, and then it seemed to leave through the same door before I had a chance to see what it was actually for — rent, ads, a contractor, some subscription I had forgotten about, whatever the house needed that week. I would look at a decent month in the business tab and still do grocery math like the business was something I had heard about rather than something I ran.
I kept thinking the next spike would settle that feeling. A better month would arrive, and for a little while the number looked healthier, and then the tightness in my chest would come back because the number in the business account and the number I could actually use for a life were never the same thing. I had been hoping they would merge if I just worked harder, which is a very attractive kind of nonsense when you are tired.
I did not sit down one afternoon and decide to run the company and the household out of one pile. I simply never opened a second place for the money to land. One login, one card, hosting and dinner on the same swipe. It felt efficient at eleven at night, and I was at eleven at night more often than I wanted to admit. I called it lean. What I was doing was mixing, and mixing will let you squint at a balance and tell yourself a story.
There is a particular embarrassment in having a site strangers recognize and still flinching at an ordinary bill. I have done that flinch, and I can tell you it does not make you disciplined. It makes you sloppy in a way you cannot see because you are too busy being proud of how hard you are working.
The thing I kept treating as later
Opening another account felt like paperwork for a version of my life I had not earned yet, which is a ridiculous sentence and it lived in my head anyway. I had this idea that a clean setup was a prize you unlock after you feel successful, instead of the unglamorous thing that makes the success usable. So I stayed in the drawer. The drawer always balanced if you looked at it quickly enough. It never told the truth.
When I finally split company money from living money, nothing cinematic happened. I could just see it — what the site actually produced, what I actually took, and how many months I had been calling a business-card swipe at the grocery store “owner pay.” It was ugly and it was useful, and I would rather have the ugly version than another year of hope dressed up as a ledger.
If you still cannot tell whether a charge belongs to the brand or to Tuesday night, you do not have a system. You have a costume that happens to have a login.
Where I point people
When the work is real and the household is still drinking from the same hose, I send them to SoFi. I am not trying to turn anyone into the person who talks about yield at dinner. I needed a place that would hold the split without becoming a homework assignment I would abandon by Thursday — banking, cash that would otherwise sit there doing nothing, and a way to look at the month without exporting three spreadsheets and lying about what they meant.
Wealthfront, Betterment, Ally, Marcus, and Acorns all have a version of this, and if one of those is the only app you will actually open, use that one. I keep sending people here because I have watched founders collect five money apps in a burst of virtue and then go right back to the checking account that is already lying to them.
Look at the real picture before you pick a product, because a new account sitting on top of a pile you still refuse to face is just a nicer pile. The first transfer you pay yourself can be small. It has to be an actual transfer, not a feeling that you “took some.” If the number is embarrassing, that is information. Now you know the number.
Your personal credit is still in the room. Mixing the accounts does not only confuse the month. It keeps the house and the brand tied together for later, when something bounces and both sides feel it at the same time.
What dropped out of the routine
I do not treat a good traffic week like a raise anymore. We have months where Google sends a lot of people and most of them came for a quote, and impressions do not buy groceries no matter how healthy the chart looks. I have had to learn that more than once.
I also stopped waiting for a clear day to get the money straight, because that day does not come. You pick a Tuesday, you move one number into a life account, and you do it again the Tuesday after that. The app is not the hero of this story. The split is.
If you sell banking or cash products and you want on this page, write to the person who is making money and still flinching at the store. SoFi is already named here. A rate chart in the first paragraph will not get published.
I did not wake up wealthy. I stopped using hope as a ledger. The site had been doing its job for a long time. I had been spending as if it hadn’t.

The Reality Check: Stop Playing Status Games While Your Job Evaporates

Is a Tesla with a Novated Lease Right for Your Budget?

Sublet vs. Sublease: What You Need to Know Before You Sign Anything

The 10-Step Blueprint Every First-Time Founder Needs to Survive

5 Things to Do After an Animal Attack to Protect Your Health and Your Claim
5 Ways For Startups To Succeed Making Acquisitions

77 Inspirational Quotes That Will Change Your Life
57 Memorable Kobe Bryant Quotes

(Images) 52 Motivational Picture Quotes For An Epic Year Of Success
40 Rare Motivational and Inspirational Picture Quotes
3 Prince EA Videos To Change Humanities Path To Greatness
(Video) What Is Success? An Entrepreneurial Story To Inspire You
(Inspirational Video) What If Today You Knew You Were Going To Take Your Last Breath?
How To Make Enough Money From A Blog To Quit Your Job – Kate McKibbin
How Finding Your Passion And Becoming An Entrepreneur Can Lead To Happiness – Chiquita Searle
-
 Life2 years ago
The 5 Stages of a Quarter-Life Crisis & What You Can Do
-

 Did You Know1 year ago
7 Surprising Life Lessons Video Games Taught Me That School Never Did
-
 Success Advice1 year ago
Stephen Covey’s 8 Leadership Habits That Will Change How You Lead Forever
-

 Life1 year ago
How to Stop the War in Your Head and Find Peace
-

 Featured2 years ago
The Psychology of Motivation: How to Keep Moving Forward Every Day
-
 Personal Development1 year ago
The Three-Second Pause That Changes How People Perceive You
-
 Explode Your Social Media1 year ago
Want More Views? Master These 6 YouTube Growth Tactics
-
 Change Your Mindset1 year ago
You Become What You Absorb: How Input Shapes Your Life