Real Estate
The Hidden Infrastructure Upgrade: How a Reliable Well System Supports Property Value

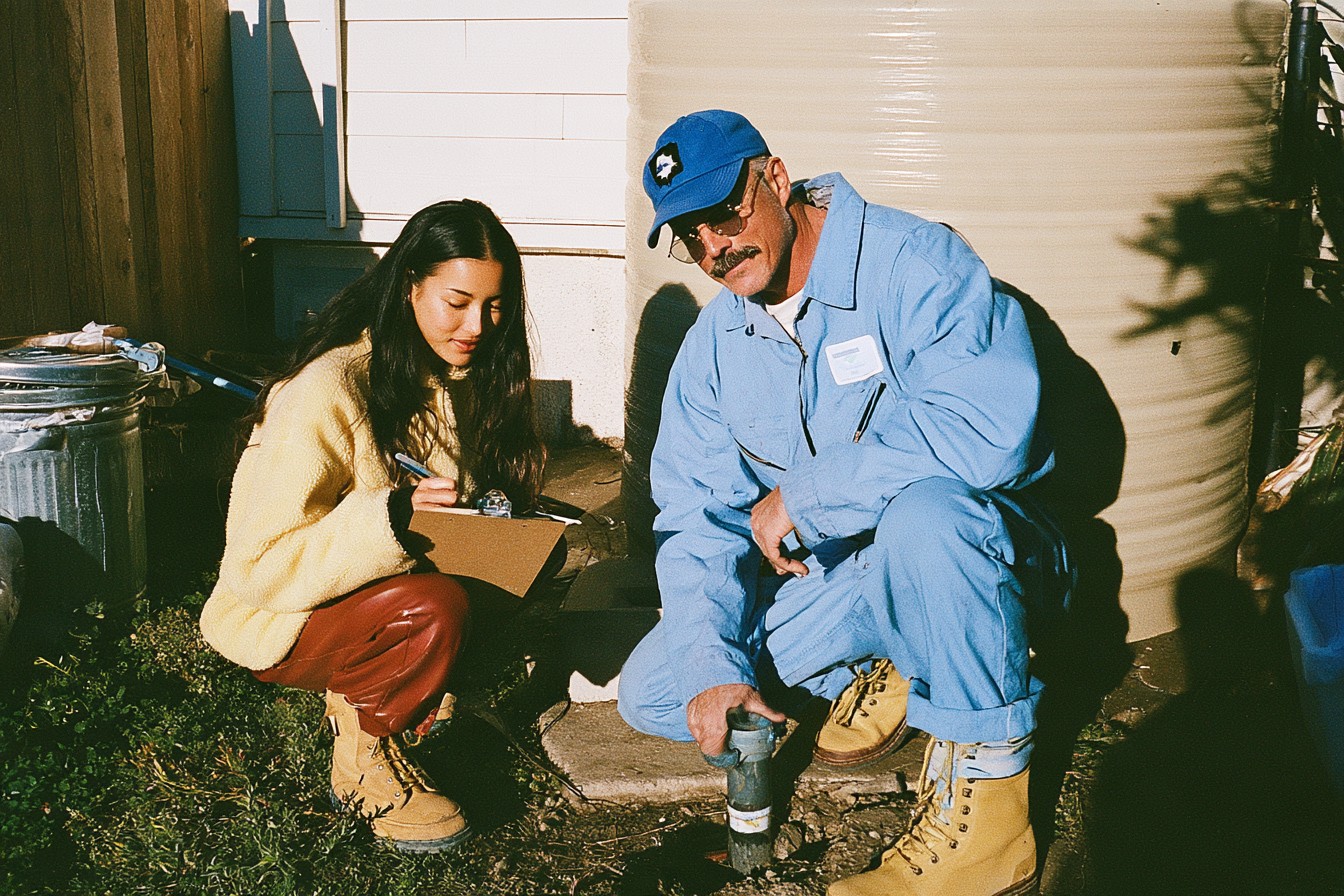
Property value is often associated with curb appeal, updated kitchens, and extra square footage. Yet one of a home’s most important features may be almost invisible: its water system. For properties that rely on private wells, the pump setup influences everyday comfort, maintenance costs, and buyer confidence. Whether you are purchasing, renovating, or preparing to sell, understanding this infrastructure can help you make informed decisions and avoid expensive surprises.
Why Well Pump Systems Matter
A private well system is more than a utility tucked away in a basement or equipment room. It delivers water for showers, cooking, laundry, cleaning, and irrigation. When it works properly, people rarely think about it. When it fails, however, the disruption quickly becomes part of daily life.
Low pressure, inconsistent flow, and unexpected interruptions can make even a beautifully renovated home feel less functional. Buyers may ask about the pump’s age, the pressure tank’s condition, maintenance history, and the system’s ability to meet household demand.
A neglected system can lead to repair requests or price negotiations. Although good maintenance cannot guarantee a higher sale price, it can reassure buyers that an essential part of the property has received proper attention.
Why Installation Quality Matters
Equipment selection is only one part of a dependable water system. Correct sizing, safe electrical connections, suitable components, and accessible installation all influence performance and future maintenance. A poorly matched pump may struggle to meet demand, while rushed workmanship can leave problems hidden until the system is under pressure.
This is where professional water well pump installation becomes part of long-term property maintenance rather than just another repair expense. A suitable setup accounts for well depth, water availability, household demand, pressure requirements, and site conditions. Quality workmanship can also make future servicing more straightforward.
If you are improving a home before listing it, keep invoices, equipment details, and service records. If you are buying, ask who completed the installation and whether warranties or inspection reports are available. Clear documentation can reduce uncertainty, although it should never replace an independent assessment.
What Buyers Often Overlook
During a viewing, it is easy to focus on flooring, appliances, the roof, and heating or cooling equipment. The well system may remain out of sight until an inspection uncovers a problem. Discovering an issue late in the process can create stress when negotiations and deadlines are already underway.
Before committing to a property, request available records for the pump, pressure tank, well yield, water-quality tests, and previous repairs. Ask whether the system has experienced low pressure, sediment, unusual noises, or repeated breakdowns. If documentation is missing, consider an assessment by a qualified well professional instead of assuming everything is working correctly.
Usage matters, too. A pump that once served a small household may struggle after renovations add bathrooms, a guest suite, or extensive irrigation. The system should be evaluated against current demand, not simply the home’s original layout.
How Performance Affects Comfort and Costs
Poor pump performance often appears through small frustrations. The shower loses pressure when the washing machine starts. Sprinklers weaken while taps are running. Water flow fluctuates, or the pump switches on and off too frequently.
These symptoms may indicate a problem with the pump, pressure tank, pressure switch, plumbing, or available well supply. Frequent cycling can strain equipment and increase electricity use. Inconsistent flow may also affect filtration and water-treatment systems.
Not every pressure issue means the pump needs replacing. A clogged filter, leaking pipe, faulty switch, or pressure-tank problem may be responsible. Professional diagnosis helps identify the cause and avoids spending money on the wrong repair. Addressing a minor issue early may also reduce the risk of a more disruptive failure.
Questions to Ask Before Buying or Renovating
Start with the basics. How old are the pump and pressure tank? When were they last serviced? Have there been outages, pressure complaints, electrical faults, or major repairs? Request recent well-yield information and water-quality results, where available.
Find out whether irrigation shares the same water supply as the household. This can help explain pressure changes during peak use. If you plan to add a bathroom, outdoor kitchen, or larger landscaped area, discuss the expected demand with a qualified professional before construction begins.
Water quantity and water quality are separate concerns. A pump may deliver water reliably without guaranteeing that the water is safe to drink. Private wells should be tested according to local health guidance and potential risks in the area. Keep test results with the property’s maintenance records so future owners can see what has been checked.
Warning Signs That Deserve Attention
Common warning signs include fluctuating pressure, sputtering taps, cloudy or discolored water, unusual pump noises, frequent breaker trips, and equipment that runs continuously or cycles repeatedly. A sudden change in water taste or odor also deserves investigation and appropriate testing.
Some clues appear outside the house. Irrigation zones may perform poorly, or water delivery may decline when several fixtures run at once. These symptoms do not identify the cause on their own, but they are good reasons to investigate rather than ignore the problem.
If you experience a sudden loss of water, electrical issues, or a change in water quality, contact an appropriate professional. Avoid opening electrical equipment or attempting repairs beyond your training. Early assessment gives you more options for scheduling work and managing costs.
For an accessible explanation of pump and pressure-system problems, This Old House’s guide to diagnosing well-water issues explains common components and warning signs. These resources can help you prepare for a service visit, but they are not substitutes for professional diagnosis.
Learn the Basics of Well Maintenance
Understanding the main components helps owners ask better questions, even when professionals handle the repairs. The U.S. Environmental Protection Agency provides practical guidance on protecting private-well water, including testing recommendations and situations that call for additional checks. Read its private well water guidance and follow relevant local recommendations.
Protecting Property Value Over Time
A home is a stronger asset when its essential systems are dependable. For a property served by a private well, that means reliable water delivery, appropriate maintenance, current water-quality information, and records showing that problems have been addressed. These details may not create dramatic listing photos, but they can support buyer confidence and make ownership more predictable.
No single infrastructure upgrade guarantees a higher valuation. Its value depends on the system’s condition, local market expectations, and the property’s needs. Still, preventing avoidable failures and documenting responsible maintenance can reduce uncertainty during a sale and help owners plan expenses more intelligently.
Water infrastructure is easy to overlook because it usually works quietly in the background. Treat it as part of the home’s overall condition, not an afterthought, and you will be better prepared to buy, renovate, maintain, or sell with confidence.






Many homeowners forget about their roofs until something goes wrong, like a leak or missing shingles. Don’t worry. Fixing minor roofing issues is often simple with some knowledge and basic tools. If you act quickly, you can avoid bigger repairs later. Whether it’s patching a leak or replacing shingles, you may find these tasks easier than you think.
Taking care of your roof helps keep your home safe and comfortable. A well-maintained roof can last longer and enhance your home’s appearance. If you notice signs of trouble or want to be proactive, addressing minor roofing issues can give you peace of mind and protect your investment. Here’s how to handle these problems yourself.
Professional Roofers
While you can handle some minor roof repairs yourself, it’s important to understand the value of professional Toronto roofers. These skilled workers bring experience and know-how to their job. They can quickly address roofing issues and keep your roof in good shape. Roofers know the different types of roofing materials and can spot potential problems before they become serious.
If you need professional help, call a trusted roofer. A good roofer will give you clear assessments and useful advice tailored to your home’s needs. Working with a reliable roofing contractor can mean the difference between a simple fix and ongoing issues.
Leaks
Finding a leak early is important. It may start as a small water stain on your ceiling, but it can get worse over time. If you think there’s a leak, check your roof inside and out. Look for wear near chimneys, pipes, or skylights, and check for any missing or damaged shingles. If you can safely climb a ladder, inspect hard-to-reach areas. If not, contact roofers for help.
To fix a small leak, you can use roofing cement or sealant. Clean the area around the leak to remove debris, moisture, or old caulk. Then apply the roofing cement liberally over the area. For longer-lasting results, replace any damaged shingles and check that the flashing around chimneys and vents is secure. Regular maintenance checks can help prevent leaks from becoming a problem.
Shingles
Missing or damaged shingles are common issues from bad weather. If you find shingles in your yard, take action. First, identify your shingle type because the replacement process varies slightly.
You can replace a shingle with some basic tools: a pry bar, a nail gun, and roofing nails. Lift the edges of surrounding shingles, remove the damaged one, and slide a new shingle into place. Nail it down securely, ensuring the nails go under the overlapping part of the shingle above. Sealing the edges with roofing cement will help keep moisture out. Regular inspections after severe weather can stop these small issues from turning into bigger repairs.
Flashing
Flashing is an important part of roofing that often gets overlooked. Install this metal around roof features like chimneys and vents to stop water from leaking in. Over time, flashing can pull away or rust, leading to leaks.
To fix flashing, check the areas around chimneys and vents for any issues. If you notice loose or missing flashing, you can usually reattach or replace it by following a few simple steps. Clean the area well, and use roofing cement to create a watertight seal when you reinstall it. If you need to replace damaged flashing, use metal that matches the original size. Take your time with this step. Secure flashing helps prevent leaks.
Debris Removal
Keeping your roof clean is essential for its health. Leaves, branches, and debris can hold moisture, leading to mould or shingle damage. Regularly clearing debris protects your roof and improves its appearance.
To clean your roof safely, use a roof rake to pull debris down gently. This helps prevent scratches or damage to your shingles. Wear rubber-soled shoes for better grip to reduce the chance of slipping. Also, keep gutters clear to ensure proper drainage. Cleaning your roof at least twice a year, especially after storms, can help you avoid bigger problems later.
Most of these fixes are well within reach for a careful homeowner, but it helps to know where DIY should stop. If a leak keeps coming back after you have patched it, if large sections of shingles are curling or missing, or if the roof deck feels soft underfoot, the problem is likely bigger than a quick repair. The same goes for steep pitches, high roofs, or any job that makes you feel unsafe on a ladder. In those cases, calling a professional is the smarter choice, because a trained eye can find the real cause and fix it properly the first time.
Handling small roof issues early pays off in more ways than one. A tight, well-kept roof keeps your home dry, helps regulate indoor temperatures, and protects insulation, drywall, and everything else beneath it. It also matters when it comes time to sell, since buyers and inspectors pay close attention to the condition of a roof. A few hours of attention each season can protect your comfort today and your home’s value for years to come.
Taking care of your roof doesn’t have to be hard. By understanding these minor roofing problems and how to handle them, you can make your roof last longer and keep your home in good condition. Remember, regular inspections and proactive maintenance can stop many roofing headaches. Happy roofing!
My escrow jumped $412 in March, and I spent two evenings convinced my lender had invented a number. It hadn’t. I had simply never learned what the four lines on that statement actually meant.
Here’s the deal most homeowners never get told at closing: escrow isn’t a fee and it isn’t a savings account. It’s a pass-through bucket your servicer uses to pay your property tax bill and your homeowners insurance on your behalf, funded by a slice of every monthly mortgage payment you make. Nothing more. That’s the whole machine.
So when people ask “What is escrow on a mortgage?”, the honest answer is that it’s a middleman arrangement with one job: make sure two large bills get paid on time so nobody puts a lien on your house. Everything confusing about escrow comes from the way that middleman guesses at next year’s bills.
Four moving pieces, and only two of them are your fault
Every escrow statement, no matter which servicer mails it, boils down to a short list of inputs. Once you can name them, the statement stops being mysterious.
Your tax bill. Set by your county assessor. You can appeal it, and that’s the only lever most homeowners ever get.
Your insurance premium. Set by your carrier, and it climbs quietly. A roof claim or a regional storm season can move this a lot.
The cushion. Your servicer is allowed to keep a small buffer on hand so the account doesn’t go negative between collections.
The collection schedule. Your monthly escrow slice, which is recalculated once a year.
Two of those you influence. Two you mostly don’t. That ratio matters, because the panic usually comes from treating all four as fixed facts of nature.
Why your payment changes even when nothing changed
Here’s the part that makes people angry, and honestly they have a point. Escrow runs on estimates. Your servicer looks at last year’s tax bill, assumes something similar next year, and spreads that number over twelve months. Then the real bill shows up, and the gap gets trued up on your next annual review.
A shortfall means your payment goes up. A surplus means a refund or a lower payment. Neither is an error by default, and neither is your servicer being sneaky, though I’ll say plainly that servicers are not exactly proactive about explaining the math before the shock lands.
What most homeowners don’t realize is how wide the swings can get in a fast-appreciating market. Counties reassess on their own schedules, sometimes years apart, and the catch-up can be brutal. If your area has had a run of rising values, your escrow slice is the first place that pain shows up.
Escrow doesn’t create tax increases. It just delivers them in installments you didn’t plan for.
The Remittance Ledger: a five minute habit that saves you money
I made this up after my second payment shock, and it’s the single most useful thing I’ve done as a homeowner. Call it the Remittance Ledger. Four columns, paper or spreadsheet, whatever you’ll actually use.
Date and amount of every escrow payment you make through your mortgage.
Date and amount of every tax or insurance disbursement your servicer makes, which shows up on your annual escrow account statement.
The county’s assessed value for your property, pulled from the assessor’s site each time you get a notice.
The delta between what you paid in and what went out, tracked year over year.
The point isn’t bookkeeping for its own sake. It’s that the delta column tells you where you’re headed roughly six months before the servicer tells you. When the money going out starts outrunning the money coming in, you can plan a cushion instead of absorbing a surprise in the same month your car needs brakes.
One scenario, because this is what it looks like in practice. A homeowner in a mid-sized metro gets a reassessment notice in the spring showing a value increase. She checks her ledger, sees taxes will likely rise by a few hundred dollars a year, and starts setting aside the difference monthly. Her annual escrow review in the fall raises her payment by about the amount she’d already banked. Annoying, not destabilizing. Without the ledger, that same letter reads like a crisis.
Appeals: the one lever you actually control
You can’t argue with your insurance carrier easily, and you can’t argue with the escrow cushion rules at all. But you can challenge an assessed value, and in many jurisdictions the process is friendlier than people assume.
The mechanics vary by county, but the shape is consistent: you file within a window after the assessment notice, you bring evidence, and a board or reviewer decides. Evidence is where most appeals die. “My neighbors pay less” is not evidence. Recent comparable sales, an independent appraisal, documentation of a condition issue the assessor missed, and a clear argument that the assessed value exceeds market value are evidence.
According to the Consumer Financial Protection Bureau, servicers must give you an annual escrow account statement that spells out your payments, disbursements, and any shortage or surplus, which is the document you’ll want open while you prep an appeal. The deadline windows are strict, and missing one costs you a full year of the higher bill. I’d file the appeal before I’d refinance, if I could only do one this year. The appeal compounds annually.
What to do when the statement arrives
Don’t read it standing up. Sit down with the ledger and work through it in order.
Check the disbursement dates against the county’s actual payment dates.
Confirm the tax amount matches the assessor’s record, not last year’s number.
Find the cushion line and see whether it grew beyond what looks reasonable.
Compare this year’s projected tax to your county’s assessed value change.
Decide: accept the new payment, or start an appeal and ask your servicer to hold off on the increase.
Here’s where a lot of people leave money on the table, and it’s a workforce fact as much as a housing one. According to the Bureau of Labor Statistics, homeownership remains the largest single asset category for most American households, which is a dry way of saying this is probably the most expensive paperwork you’ll ever skim past. Skimming it has a cost.
When the county keeps raising your number
Some markets reassess aggressively, and some assessments come in above what comparable homes are actually selling for. If you’ve pulled your record, compared it against real sales, and you’re still staring at a number that doesn’t hold up, that’s the moment to bring in help.
The Department of Housing and Urban Development runs housing counseling resources that can point homeowners toward legitimate local help, and your county assessor’s office publishes the appeal procedures for free. Read those first. Anyone who charges you before they’ve looked at your assessment is charging you for nothing.
The short version
Escrow is a pass-through, not a fee. Your payment moves because estimates meet reality once a year, and the gap lands on you. The two levers you own are your insurance shopping and your tax appeal, and the appeal is the bigger one. Track the delta, file inside the window, and the annual letter turns into a routine you handle in twenty minutes instead of a bill you dread.
Pull your last escrow statement out of the drawer this week. If the tax line doesn’t match what your county assessor shows for your property, you’ve just found the reason your payment jumped, and the clock on your appeal window is already running.
Three siblings inherit their mother’s duplex. One lives in it, one rents her half out, one moved to Portland and wants cash. Two years later, nobody is speaking through anything but attorneys. This is the single most common starting point for a partition action California courts see, and it almost never begins with a lawsuit. It begins with silence.
If that sounds like your family group chat, here’s the good news: California built a legal mechanism specifically for co-owners who have run out of other options. You don’t need your co-owner’s permission to use it. You don’t need them to agree the property should be sold. And you don’t need to win an argument about who’s right.
What you do need is to understand the machinery before you walk into it, because the timeline and the money both behave in ways that surprise nearly everyone. I’ve watched the pattern repeat enough to have opinions about it, and I’ll share them.
Why Co-Ownership Breaks Where It Does
Joint ownership works beautifully right up until the two owners want different things. A property held as tenants in common has no built-in exit. Nothing forces a sale, nothing forces a buyout, and nothing stops one owner from digging in for years while the other absorbs property taxes, insurance, and repair bills. The deadlock isn’t a personality failure. It’s a structural gap in how the ownership was set up in the first place.
You’ll see this pattern in a few recognizable shapes:
- Ex-partners who bought together while things were good
- Siblings who inherited a house and disagree on whether to rent it
- Parents on title with an adult child who now wants out
- Co-investors whose original plan quietly died
Notice that none of these are real estate professionals. These are ordinary people who happened to sign the same deed.
What a Partition Actually Does
California law treats co-ownership as a relationship that either party can end. A partition action asks a court to force a division or sale of jointly held property, and the process separates into two flavors. A partition in kind physically divides the land, which works for a large parcel and almost never works for a single house. A partition by sale puts the whole property on the market and splits the proceeds according to ownership share.
For anything with a roof, a sale is what usually happens. You can read the procedural mechanics at the federal courts system, though partition itself runs through California superior courts.
Here’s the part clients argue with me about: a co-owner who doesn’t want to sell cannot simply refuse. Courts can order the sale anyway. That’s the entire point of the remedy, and it’s why so many family disputes end up resolved in a courtroom instead of a living room.
A Simple Framework for Deciding Whether to File
I use a four-part test with clients before anyone drafts a complaint. Call it the Ownership Exit Check.
That fourth row matters more than people expect. Filing gives you leverage, but leverage without a goal turns a two-year case into a five-year one. My honest take: if you want the house itself, partition is a clumsy way to get it, because you’re bidding against your own relative at a court-supervised sale.
What Surprises Owners Most
Nobody warns you about the accounting. During the case, every co-owner’s contributions get examined. If you paid the mortgage alone for four years, that’s a factor. If you collected rent from the other unit and kept it, that’s a factor too. What you assumed was generosity during the good years becomes a line item during the bad ones.
The second surprise is cost and pacing. A contested partition can run well into six figures in legal fees and consume years. Courts move at their own speed, and a co-owner with nothing to lose has every incentive to delay.
Population and housing pressure make this more common than it used to be. According to the U.S. Census Bureau, homeownership and household composition across the country have shifted considerably over recent decades, and more households now hold property through inheritance or shared purchase than through a single buyer. More shared ownership means more shared disagreements.
The third surprise: tax treatment. Proceeds from a forced sale aren’t automatically tax-free the way some owners assume, and the rules differ depending on whether the property was a residence, a rental, or an investment. Talk to a tax professional before you sign anything. That’s not legal advice, it’s basic sequencing.
Before You File: A Practical Checklist
- Put your request in writing. A clear, dated demand for sale or buyout changes how a court reads the history.
- Pull the deed and any recorded agreements. You need to know exactly how title is held.
- Build a paper trail of every dollar you’ve contributed and received.
- Get a realistic valuation, not Zillow’s number. Expect the court process to produce a lower figure than you hope.
- Try one structured negotiation. Mediation fails often, and it also resolves cases cheaply when it works.
If step five fails, you’re not out of options. You’re just at the point where the legal route becomes the reasonable one.
What Is the Realistic Timeline?
Uncontested partitions can wrap in under a year. Contested ones drag. If your co-owner hires counsel and contests every motion, expect eighteen months to three years depending on the county. Courts in busy metropolitan areas see heavier dockets, which slows everything down.
I’d rather tell you that up front than let you discover it in month fourteen. The Department of Housing and Urban Development tracks housing market conditions nationwide, and it’s clear the underlying pressure on shared property isn’t going away.
What to Take Away From All of This
Co-ownership without an exit plan is a bet that everyone will keep agreeing forever. That bet fails constantly. A partition action exists precisely because it has to.
If you’re stuck with a co-owner who won’t budge, the question isn’t whether you have the right to force a resolution. You do. The question is whether you’ve done the prep work that makes that resolution fast, clean, and affordable. Start with the writing, the deed, and the receipts. Then decide.

Gutters protect your home from water damage. When they work properly, they carry rainwater away from your roof and foundation, keeping everything dry. However, over time, gutters can be damaged by wear and tear, weather changes, or clogs. A small issue can become a bigger problem if you don’t fix it. That’s why you need to check your gutters regularly and know how to repair them when needed.
You might be surprised at how easy it is to fix gutter problems yourself. With the right tools and a bit of knowledge, you can save money on costly repairs later. Let’s look at how you can fix damaged gutters at home.
Spotting damage
The first step in repairing gutters is to identify any damage. Look for clear signs like sagging, rust, or leaks. If you see water pooling around your foundation or on your roof, your gutters may not be working correctly. Sometimes, a close look can show cracks or holes that aren’t easy to spot at first.
Check the seams where different sections of the gutters connect. These joints can often be weak, especially if they haven’t been sealed well. Also, look for sections that bend or pull away from the house. Finding these problems early can help you fix them before they get worse.
Tools needed
To repair your Delta gutters, you’ll need a few tools. Start with a sturdy ladder to safely reach high places. A trowel will help you clean out debris and clogs. You’ll also want drip-edge shingles or small rubber gaskets for seal repairs. Sealant or gutter repair tape can help fix leaks.
Wear gloves to protect your hands from sharp edges or debris. If your gutters have rust, a wire brush or sandpaper can smooth those areas before applying sealant. Having these tools ready will make your repair process easier.
Removing debris
Cleaning your gutters is essential for keeping them working well. Leaves, dirt, and other debris can build up and cause clogs. To start, climb your ladder and carefully scoop out any gunk blocking the water flow. Be ready for a messy job, as the debris can be compact and stubborn!
Remove as much debris as possible so you can see any damage underneath. Use a bucket or tarp at the base of your ladder to catch anything you drop. After cleaning out the gutters, take a moment to rinse them with a hose. This helps clear out any leftover sludge and shows whether water flows freely.
Scheduling Routine Cleanings
Cleaning your gutters is not a one-time job. It needs regular attention. Aim to clean them seasonally, especially in the fall when leaves are everywhere. Depending on your location, you might want to schedule cleanings twice a year. Keeping a routine helps you spot problems before they get worse.
If you’re not comfortable climbing ladders, consider hiring a professional service. They can do the heavy lifting and keep your gutters well maintained. Regular cleanings keep your gutters working well and can help them last longer, ultimately saving you money.
Finding leaks
After you clean your gutters, check them for leaks. Look for holes or gaps where water might escape. If you notice water spilling out instead of flowing smoothly, you might leak.
Most leaks can be fixed easily. Start by checking the seams; cracks often appear there. Run your fingers along the ends and joints to feel for moisture or see any visible damage. A quick visual inspection is usually enough to find where you need repairs.
Applying sealant
For small holes or cracks, use gutter sealant. Clean the area around the leak and make sure it’s dry. Apply plenty of sealant to the crack or hole, then smooth it out with your finger for a secure seal. If the damage is larger, consider using gutter repair tape.
For bigger repairs, you might need to replace a section of the gutter. Most hardware stores sell gutter sections you can install yourself. Match the size and type of your existing gutters to keep everything consistent.
Gravity’s role
Over time, gutters can sag or get misaligned, affecting how they handle water. The gutter angle matters for directing water to the downspouts. If they aren’t sloped correctly, water can pool instead of flowing away.
Check your gutters from different perspectives to see if they are aligned properly. Ideally, gutters should slope toward the downspouts at about a quarter inch for every ten feet. This setup allows water to flow smoothly.
Making adjustments
To fix sagging gutters, examine the brackets that hold them up. Tightening loose screws or replacing brackets can help with alignment. If needed, adjust the gutter pitch by loosening the brackets, changing their height, and then re-tightening everything to create the right slope.
Take your time with this adjustment. If the gutters aren’t aligned, gravity won’t work properly, and you could face various water damage problems later. Pay attention to the details. Maintaining your gutters is very important. Small repairs can prevent bigger issues. Keep an eye on your gutters, and you’ll enjoy a well-kept and damage-free home!

54 Jocko Willink Quotes for Discipline, Ownership and Leadership

55 Seneca Quotes for a Life Well Spent

54 Stoic Quotes for an Unshakeable Mind

49 Discipline Quotes for Success

56 David Goggins Quotes on Mental Toughness
5 Ways For Startups To Succeed Making Acquisitions

77 Inspirational Quotes That Will Change Your Life
57 Memorable Kobe Bryant Quotes

Motivational Picture Quotes: 52 Images to Inspire a Successful Year
40 Rare Motivational and Inspirational Picture Quotes
3 Prince EA Videos To Change Humanities Path To Greatness
(Video) What Is Success? An Entrepreneurial Story To Inspire You
(Inspirational Video) What If Today You Knew You Were Going To Take Your Last Breath?
How To Make Enough Money From A Blog To Quit Your Job – Kate McKibbin
How Finding Your Passion And Becoming An Entrepreneur Can Lead To Happiness – Chiquita Searle
-

 Did You Know1 year ago
7 Surprising Life Lessons Video Games Taught Me That School Never Did
-
 Life2 years ago
The 5 Stages of a Quarter-Life Crisis & What You Can Do
-
 Success Advice1 year ago
Stephen Covey’s 8 Leadership Habits That Will Change How You Lead Forever
-

 Featured2 years ago
The Psychology of Motivation: How to Keep Moving Forward Every Day
-

 Life1 year ago
How to Stop the War in Your Head and Find Peace
-
 Personal Development1 year ago
The Three-Second Pause That Changes How People Perceive You
-
 Explode Your Social Media1 year ago
Want More Views? Master These 6 YouTube Growth Tactics
-
 Change Your Mindset1 year ago
You Become What You Absorb: How Input Shapes Your Life