Real Estate
How to Fix Damaged Gutters in Your Home

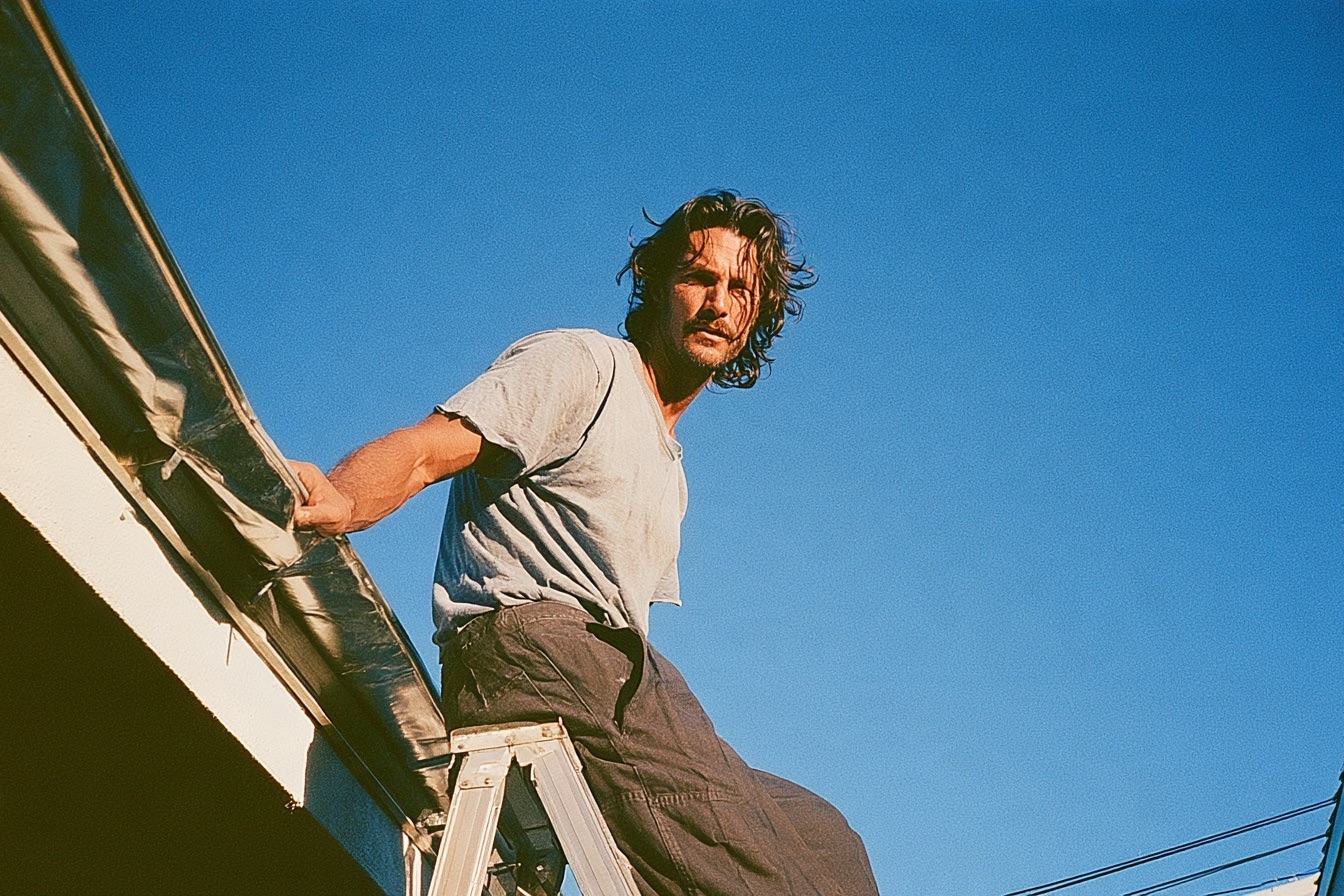
Gutters protect your home from water damage. When they work properly, they carry rainwater away from your roof and foundation, keeping everything dry. However, over time, gutters can be damaged by wear and tear, weather changes, or clogs. A small issue can become a bigger problem if you don’t fix it. That’s why you need to check your gutters regularly and know how to repair them when needed.
You might be surprised at how easy it is to fix gutter problems yourself. With the right tools and a bit of knowledge, you can save money on costly repairs later. Let’s look at how you can fix damaged gutters at home.
Spotting damage
The first step in repairing gutters is to identify any damage. Look for clear signs like sagging, rust, or leaks. If you see water pooling around your foundation or on your roof, your gutters may not be working correctly. Sometimes, a close look can show cracks or holes that aren’t easy to spot at first.
Check the seams where different sections of the gutters connect. These joints can often be weak, especially if they haven’t been sealed well. Also, look for sections that bend or pull away from the house. Finding these problems early can help you fix them before they get worse.
Tools needed
To repair your Delta gutters, you’ll need a few tools. Start with a sturdy ladder to safely reach high places. A trowel will help you clean out debris and clogs. You’ll also want drip-edge shingles or small rubber gaskets for seal repairs. Sealant or gutter repair tape can help fix leaks.
Wear gloves to protect your hands from sharp edges or debris. If your gutters have rust, a wire brush or sandpaper can smooth those areas before applying sealant. Having these tools ready will make your repair process easier.
Removing debris
Cleaning your gutters is essential for keeping them working well. Leaves, dirt, and other debris can build up and cause clogs. To start, climb your ladder and carefully scoop out any gunk blocking the water flow. Be ready for a messy job, as the debris can be compact and stubborn!
Remove as much debris as possible so you can see any damage underneath. Use a bucket or tarp at the base of your ladder to catch anything you drop. After cleaning out the gutters, take a moment to rinse them with a hose. This helps clear out any leftover sludge and shows whether water flows freely.
Scheduling Routine Cleanings
Cleaning your gutters is not a one-time job. It needs regular attention. Aim to clean them seasonally, especially in the fall when leaves are everywhere. Depending on your location, you might want to schedule cleanings twice a year. Keeping a routine helps you spot problems before they get worse.
If you’re not comfortable climbing ladders, consider hiring a professional service. They can do the heavy lifting and keep your gutters well maintained. Regular cleanings keep your gutters working well and can help them last longer, ultimately saving you money.
Finding leaks
After you clean your gutters, check them for leaks. Look for holes or gaps where water might escape. If you notice water spilling out instead of flowing smoothly, you might leak.
Most leaks can be fixed easily. Start by checking the seams; cracks often appear there. Run your fingers along the ends and joints to feel for moisture or see any visible damage. A quick visual inspection is usually enough to find where you need repairs.
Applying sealant
For small holes or cracks, use gutter sealant. Clean the area around the leak and make sure it’s dry. Apply plenty of sealant to the crack or hole, then smooth it out with your finger for a secure seal. If the damage is larger, consider using gutter repair tape.
For bigger repairs, you might need to replace a section of the gutter. Most hardware stores sell gutter sections you can install yourself. Match the size and type of your existing gutters to keep everything consistent.
Gravity’s role
Over time, gutters can sag or get misaligned, affecting how they handle water. The gutter angle matters for directing water to the downspouts. If they aren’t sloped correctly, water can pool instead of flowing away.
Check your gutters from different perspectives to see if they are aligned properly. Ideally, gutters should slope toward the downspouts at about a quarter inch for every ten feet. This setup allows water to flow smoothly.
Making adjustments
To fix sagging gutters, examine the brackets that hold them up. Tightening loose screws or replacing brackets can help with alignment. If needed, adjust the gutter pitch by loosening the brackets, changing their height, and then re-tightening everything to create the right slope.
Take your time with this adjustment. If the gutters aren’t aligned, gravity won’t work properly, and you could face various water damage problems later. Pay attention to the details. Maintaining your gutters is very important. Small repairs can prevent bigger issues. Keep an eye on your gutters, and you’ll enjoy a well-kept and damage-free home!








Real Estate
REITs for Beginners: Owning Real Estate Without Being a Landlord
What REITs actually require, how equity, mortgage and hybrid types differ, and why publicly traded, non-traded and private products are not interchangeable.

REITs for beginners start with a simple structure: a real estate investment trust is a company that owns, and typically operates, income-producing real estate or real estate-related assets, such as mortgages. The SEC’s Office of Investor Education and Advocacy puts it that way in its Investor.gov bulletin on publicly traded REITs. You buy a share of the company, not a building, so you are not collecting rent, fixing toilets or qualifying for a landlord loan.
You’ll also hear equity REITs, mortgage REITs, listed REITs or, loosely, “real estate stocks.” They are not all the same, and they are not a substitute for owning property outright. This is education, not a recommendation to buy any REIT, fund or ticker, and it is not tax or investment advice. Talk to a licensed advisor, and a tax professional, before you put money in.

What makes a company a REIT
A company cannot simply own a warehouse and call itself a REIT. Under the rules summarized by the SEC, a REIT must, among other tests, invest at least 75% of its total assets in real estate assets and cash, derive at least 75% of its gross income from real estate sources such as rents and mortgage interest, and distribute at least 90% of its taxable income to shareholders each year as dividends. It must also be managed by a board, have transferable shares, have at least 100 shareholders after its first year, and avoid having five or fewer individuals own more than 50% of the shares during the last half of the taxable year.
That 90% payout is why people talk about REIT dividends. Because a REIT can deduct the dividends it pays, most pay out at least 100% of taxable income and owe no corporate tax on that distributed income, which is the “no double taxation” point the SEC bulletin makes. The income is still taxed when you receive it. And REIT dividends typically do not qualify for the lower tax rate that applies to many qualified dividends. They are often taxed as ordinary income. Your own situation can differ, especially inside a tax-deferred account such as an IRA, which is why a tax professional should look at the account and the form, not a blog post.
Equity, mortgage and hybrid REITs are different businesses
Most REITs are equity REITs. They own and operate properties and earn most of their income from rent. Many specialize in one property type: apartments, offices, warehouses, retail, healthcare, data centers, self-storage and others. A warehouse REIT and an office REIT can live in completely different markets, even though both are “real estate.”
Mortgage REITs do not primarily own buildings. They lend to real estate owners or buy mortgages and mortgage-backed securities, and they earn interest. The SEC notes that mortgage REITs tend to use more borrowed money than property-focused REITs, and that many use derivatives and other hedging tools to manage interest-rate and credit risk. Those strategies have their own risks, which belong in the company’s Form 10-K, not in a marketing one-liner. Hybrid REITs mix both approaches.
Interest rates can cut both ways. Higher rates may allow some REITs to charge more for rent or mortgages, and they can also raise a REIT’s own acquisition and borrowing costs. When savings accounts and certificates of deposit start paying more, some income-seeking investors also find REIT yields less attractive. None of that is a timing signal. It is a reminder that a REIT is a market-priced security, not a savings account.
Publicly traded, non-traded and private are not the same product
This is the distinction I want beginners to get right, because the word “REIT” gets used for all three.
Publicly traded REITs register with the SEC, file regular reports, and list their shares on an exchange. You can usually buy or sell them the way you would other listed stocks, and a market price is visible. Brokerage costs look like ordinary stock trades.
Non-traded REITs also register and file with the SEC, but their shares do not trade on an exchange. The SEC’s Investor.gov bulletin on non-traded REITs is blunt about the differences. There is no readily available market price. Liquidity events may not arrive for more than 10 years. Early redemption programs, when they exist, are often limited, can be shut off, and may redeem shares at a discount. Upfront fees can represent up to 15% of the offering price, with ongoing management and transaction fees on top, which leaves less of your money actually invested in property. Distributions can also be supported by offering proceeds or borrowing, not just earnings from operations, which can make a high “yield” look better than the business is. Conflicts of interest are more common when an external manager is paid on assets or acquisitions.
Private REITs are typically private placements. They are not listed, they may not file regular SEC reports, and they are usually limited to accredited investors. Hard to value, hard to sell, and hard to monitor.
If someone is selling you a REIT on the strength of a high distribution, a “guaranteed” income story, or the fact that it is “public” without being listed, slow down. Read the prospectus and the SEC filings in EDGAR. Check that the person selling it is actually registered, which you can do through the SEC’s Investment Adviser Public Disclosure site or FINRA’s BrokerCheck.
A REIT is not the same as owning the building
Buying a listed REIT is closer, in daily life, to owning a stock than to being a landlord. The share price can move with the market, with interest rates and with the fortunes of that property type, even if the buildings are still leased. You also do not get the same direct control, tax depreciation decisions or leverage choices you would have if you bought a property yourself.
That is why this decision sits next to a broader real estate vs stocks question, not in place of it. A REIT can be a way to get real-estate exposure inside a securities account. It does not automatically “beat” owning a rental, and it does not automatically lose to a stock index. Those are different jobs, with different costs, risks and time commitments.
There are also REIT-focused mutual funds and exchange-traded funds, which the SEC notes as another way people get diversified exposure to the sector. I am not going to name funds or tickers, or rank platforms. Fees, holdings and tax treatment still have to be read in the prospectus, and the product still has to fit the rest of your plan.
Because a REIT must pay out most of its taxable income, it often has less leftover cash to fund growth than an ordinary company that can retain earnings. Many raise new equity or take on debt to buy the next set of properties. That is not automatically a red flag, but it is a reason to read the filings instead of staring at the dividend yield. For a listed REIT, start with the latest Form 10-K in the SEC’s EDGAR database: what it owns, how much debt it carries, how much of the distribution comes from operations rather than return of capital, and what risks it discloses. For a non-traded offering, start with the prospectus. A high yield that is being supported by your own invested capital is not income in the ordinary sense.
A REIT is one tool, not a plan. If you are still working out successful investment strategies for new beginners, start with your time horizon, emergency cash and tax situation, then decide whether any real-estate exposure belongs in the mix. A licensed advisor can help you place it, or tell you it does not belong.
Frequently Asked Questions
What is a REIT for beginners?
A REIT, or real estate investment trust, is a company that owns or finances income-producing real estate. You buy shares in the company instead of buying a property yourself. Qualifying REITs must distribute at least 90% of taxable income to shareholders each year.
How do REITs make money?
Equity REITs typically earn rent from properties they own and operate. Mortgage REITs earn interest from real estate loans or mortgage-backed securities. Hybrid REITs use both approaches. Shareholders may receive dividends and can also see the share price rise or fall.
Are REIT dividends taxed as qualified dividends?
Usually not. The SEC notes that REIT dividends typically do not get the lower tax rate that applies to many qualified dividends, and are often taxed as ordinary income. Treatment can differ in a tax-deferred account. Ask a tax professional about your situation.
What is the difference between a publicly traded REIT and a non-traded REIT?
Publicly traded REITs list on an exchange and usually can be bought or sold like other listed stocks. Non-traded REITs file with the SEC but do not list, so they can be hard to value and sell, often carry high upfront fees, and may lock up capital for years.
Are REITs safer than owning rental property?
No. They avoid landlord work, but you still take property, interest-rate and market risk, and a listed REIT’s share price can fall. Non-traded and private REITs add liquidity and fee risks. Safety depends on the specific product and on your plan, not on the label.
Should a beginner buy a specific REIT or REIT fund?
This page does not recommend any ticker, fund or platform. If you are considering the asset class, review SEC filings, understand the fees and tax treatment, and talk with a licensed advisor before you invest.
Real Estate
Cost Segregation Study: How Real Estate Investors Pull Depreciation Forward Without Touching the Loan
A cost segregation study is an engineering-based analysis that splits the cost of a building into parts the IRS lets you depreciate faster, such as 5-, 7- and 15-year property, instead of writing off everything over 27.5 years for residential rentals or 39 years for commercial buildings. It doesn’t change your loan, your rent or the building. It changes when you get the depreciation.
People also search it as cost seg, a cost segregation analysis or accelerated depreciation on rental property. Same idea. This is education, not tax advice. A study is a technical tax position, so you want a CPA and a qualified engineer or specialist firm involved, but here’s how it works and when it’s worth paying for.

Why real estate investors care about cost segregation
Real estate rewards people who think in years, not weeks. But cash today still matters. It’s the deposit on the next property, the roof you need to replace, the cushion that keeps a bad quarter from becoming a forced sale.
Straight-line depreciation is slow. Under IRS rules, residential rental buildings are depreciated over 27.5 years and nonresidential real property over 39 years (IRS Publication 946). On a building worth $800,000 after you take out the land, that’s roughly $29,000 a year for residential.
The thing is, a building isn’t one asset. The carpet, the appliances, the cabinets, the parking lot and the landscaping all wear out much faster than the walls and the foundation. A cost segregation study finds those pieces and puts a number on each one.
How a cost segregation study works
A specialist reviews the purchase or construction costs, the plans and the property itself, then assigns each component to its proper recovery period. The IRS publishes a whole Cost Segregation Audit Techniques Guide (Publication 5653, revised February 2025) that its examiners use to judge these studies. That alone tells you something. The IRS accepts the method. It just expects it done properly.
| Component type | Typical examples | Recovery period |
|---|---|---|
| Personal property | Appliances, carpet, some cabinetry, decorative lighting, certain electrical serving equipment | 5 or 7 years |
| Land improvements | Parking lots, sidewalks, fencing, landscaping, outdoor lighting | 15 years |
| Residential building | Structure, roof, walls, core plumbing and HVAC | 27.5 years |
| Commercial building | Structure, roof, walls, core building systems | 39 years |
| Land | The dirt itself | Not depreciable |
Which bucket a component lands in depends on how it’s used, not just what it is. Electrical wiring that runs the building stays with the building. Wiring dedicated to specific equipment may not. That nuance is exactly why the quality of the study matters.
Cost segregation and bonus depreciation after the 2025 tax law
This is where the study got a lot more interesting. The One Big Beautiful Bill made 100% bonus depreciation permanent for qualified property acquired after January 19, 2025. The IRS confirmed this in Notice 2026-11 guidance. Bonus depreciation generally applies to property with a recovery period of 20 years or less, which is exactly what a cost seg study surfaces.
So the 5-, 7- and 15-year pieces a study identifies can often be deducted in the first year rather than spread out. Property acquired before January 20, 2025 stays under the older phase-down rules, and the acquisition date is what counts, so a study today doesn’t make an older purchase eligible for 100%.
I won’t repeat the whole bonus-versus-expensing debate here. If you’re weighing the two, our breakdown of Section 179 vs bonus depreciation covers it. The point for this article is simpler. Bonus depreciation is the engine. The study is what tells you how much fuel you’ve got.
A simple cost segregation example
Here’s a teaching example, not a real client file. Say an investor buys a small apartment building for $1,000,000 in 2026, with $200,000 allocated to land.
- Without a study: $800,000 of building over 27.5 years is about $29,100 of depreciation a year.
- With a study: suppose the study moves $180,000 into 5-, 7- and 15-year property. With 100% bonus, that $180,000 could be deducted in year one, plus regular depreciation on the remaining $620,000 of building.
Studies commonly reclassify somewhere around 15% to 30% of building cost, but that’s a range firms quote in their marketing, not a promise. Your number depends on the property type, the finishes and the age. Treat any figure in this example as an estimate.
When is a cost segregation study worth it?
A big deduction is only useful if you can actually use it. That’s where I’d be blunt with any investor. Don’t buy a study because a podcast told you to. Buy it because the math works for your tax return.
- Size of the building basis. Firms often say studies start to make sense from roughly $200,000 to $300,000 of depreciable basis. Below that the fee can eat most of the benefit. That’s a rule of thumb, not an IRS line.
- How long you’ll hold. If you sell in a year or two, much of the benefit comes back as recapture.
- Whether you can use the losses. Rental losses are usually passive. More on that below.
- Your tax bracket now versus later. Accelerating deductions helps most when your rate is high today.
- The fee and the firm. Get at least two quotes and ask how the study is prepared. Engineering-based, detailed studies hold up best, according to the IRS guide.
The passive loss rules that can strand your deduction
This is the part vendor pages skim past. Under the passive activity rules in section 469, rental losses generally can only offset passive income. If you actively participate, you may deduct up to $25,000 of rental losses against other income, but that allowance phases out between $100,000 and $150,000 of modified adjusted gross income (IRS Publication 925).
Real estate professionals, meaning more than half your working hours and more than 750 hours a year in real property businesses where you materially participate, can treat rental losses as non-passive. Some short-term rentals can also fall outside the rental rules depending on average stay and participation. Both are fact-heavy and audited often. Get advice before you count on either.
If you can’t use the loss this year, it isn’t lost. Suspended passive losses carry forward. But a huge first-year deduction that just sits there doesn’t do much for your cash today.
Depreciation recapture: the bill that comes when you sell
Faster depreciation means a lower basis. When you sell, the 5-, 7- and 15-year components can be recaptured, and personal property recapture is taxed at ordinary income rates. The building portion falls under the unrecaptured section 1250 rules, taxed at up to 25%.
That’s why the hold period matters so much. Many investors plan to defer that bill with a like-kind exchange, and if that’s your plan, read up on the 1031 exchange rules before you buy, not after. Either way, cost seg moves tax forward in time. It rarely makes it disappear.
You can still do a study on a property you already own
Bought the building a few years ago and never did a study? A look-back study can still help. Instead of amending old returns, your CPA typically files Form 3115 for a change in accounting method and claims the missed depreciation as a catch-up adjustment in the current year. The bonus percentage still follows the original acquisition date.
Here’s my take after watching people overcomplicate real estate for years. The investors who win aren’t the ones with the cleverest tax trick. They’re the ones who understand their numbers well enough to know when a tool fits and when it doesn’t. A cost segregation study is a good tool. Just make it earn its fee.
FAQ: Cost segregation study
How much does a cost segregation study cost?
Fees vary by property size and complexity. Smaller residential studies are often quoted in the low thousands of dollars and large commercial studies cost more. Get at least two quotes and compare the projected first-year deduction to the fee.
Is cost segregation worth it for a single-family rental?
Sometimes. On a lower-basis single-family home, the fee can eat most of the benefit. It’s more likely to pay on higher-value properties, short-term rentals with heavy furnishings, or when you can actually use the losses.
Does cost segregation increase audit risk?
A properly documented, engineering-based study is a recognized method, and the IRS publishes an audit guide for reviewing them. Weak, unsupported studies are what draw problems, so the quality of the firm matters.
Can I do a cost segregation study on a property I bought years ago?
Yes. A look-back study lets you catch up missed depreciation in the current year, usually by filing Form 3115 for a change in accounting method, without amending prior returns.
What is the difference between cost segregation and bonus depreciation?
Cost segregation identifies which parts of a building have shorter recovery periods. Bonus depreciation lets you deduct qualifying short-life property in the first year. The study supplies the numbers that bonus depreciation then accelerates.
Do I have to pay back depreciation when I sell?
Generally yes, through depreciation recapture. Accelerated components can be taxed at ordinary rates on sale, and the building portion at up to 25%, unless you defer with a like-kind exchange.
Real estate vs stocks is not a moral debate – it is a capital-allocation decision about returns, leverage, liquidity, time cost, and taxes. For a business owner, stocks usually win on liquidity and low time cost, while investment real estate can win on leverage and tax-advantaged cash flow if you (or a system you build) will actually manage it. The faster wealth path is the one that matches how you already make money and how much attention you have left after the business.
I get this question from founders more than almost any other money question. They have a good quarter. The checking account is fat for once. Someone at dinner says rental property is how you get rich, and someone else says the S&P 500 has crushed housing for decades. Both can point at charts. Both can be right for a different kind of person. The founder in the middle just wants to know where the next investable dollar should go without lighting their calendar on fire.
If you already run a company, you are not a blank-slate investor. Your scarcest resource is not always capital. It is attention. That changes the real estate vs stocks math in ways generic personal-finance articles skip.
This NerdWallet explainer is a clean, neutral primer on how the two asset classes differ on returns, risk, and effort:

The Five Lenses That Actually Matter
Forget “which is better.” Run every dollar through these five lenses:
| Lens | Stocks (index / broad ETFs) | Investment real estate |
|---|---|---|
| Returns | Historically strong long-term total return for broad U.S. equities; volatile year to year | Return stack = rent + principal paydown + appreciation + tax effects; path depends on deal quality and market |
| Leverage | Usually cash or modest margin (risky) | Mortgage leverage is normal; a 20-25% down payment controls a much larger asset |
| Liquidity | Sell in minutes on a trading day | Weeks to months to sell; transaction costs are real |
| Time cost | Near-zero after you automate contributions | Tenants, repairs, vacancies, property managers, CapEx – unless you buy systems that remove you |
| Taxes | Preferential long-term capital gains / qualified dividends in taxable accounts; tax-advantaged accounts help | Depreciation, expense deductions, 1031 deferral potential, and eventual recapture – CPA required |
Notice what is missing from that table: your ego. “I want to be a landlord” is not a strategy. Neither is “I hate tenants.” Your operating business already teaches you whether you like operational complexity. Use that data.
Returns: Charts Lie When You Ignore Your Hours
Over long windows, broad U.S. stock indexes have delivered strong compounded returns. Housing appreciation alone often looks slower on a headline chart. That is why stock-market fans win a lot of dinner arguments.
Real estate investors answer with a different stack. On a good rental, you may get:
- Monthly cash flow after expenses
- A tenant helping pay down the loan
- Appreciation on the whole property, not just your down payment
- Tax treatment that can improve after-tax yield
On paper, leveraged real estate can look faster. In life, a bad property, a bad market, or a year of vacancies can erase the spreadsheet fantasy. Stocks can crash 30% and still require zero Saturday mornings with a plumber. Real estate can cash-flow nicely and still cost you the mental bandwidth your company needed that quarter.
My rule: if you will not underwrite the deal like a business – rent comps, CapEx, reserves, vacancy – do not buy the property. Buy the index fund instead and keep your focus on the company that already pays you.
Leverage: Real Estate’s Superpower and Its Trap
This is the main reason real estate can build equity faster for some owners. With a conventional investment-property down payment, you control an asset worth several times your cash. If the property rises 5%, your equity can rise much more than 5% because the bank’s money rode along.
Leverage cuts both ways. A 20% drop on a leveraged property can wipe a large share of your equity. Stocks bought with cash do not usually have that same forced-loss geometry (margin trading is the exception, and most business owners should not play that game).
Founders who already carry business debt need to be honest about total leverage across their life. Stacking an aggressive rental portfolio on top of a cyclical operating company is how “diversification” turns into one bad season hitting you twice.
Liquidity: Can You Get Your Money Back When the Business Needs It?
Your company will eventually ask for capital – a key hire, an inventory swing, a lawsuit, a growth window. Stocks in a brokerage account can fund that in days. A duplex cannot.
That single fact is why I often tell owners to build a liquid investment base first, especially if the business is still volatile. You can always add property later. It is harder to unstick a property when payroll is due Friday.
Retirement accounts change the texture again. A Solo 401(k) or SEP IRA decision can shelter stock-market compounding while you keep the operating company humming. Illiquid property inside a complex self-directed structure is a different skill set entirely – do not improvise it after a podcast.
Time Cost: The Hidden Line Item Founders Forget
Stock investing at the index level is mostly a systems problem: automate contributions, rebalance rarely, ignore noise.
Direct real estate is an operations business wearing an investment costume. Even with a property manager, you still own the CapEx surprises, the eviction drama, the insurance renewal, and the 2 a.m. decision when the roof fails. If your company already eats sixty hours a week, adding a “side” rental can quietly become a second unpaid job.
There are founder-friendly ways in. Some owners start with house hacking so the property lowers living costs while they learn the asset class. Others buy turnkey only after they have reserves and a manager they trust. The point is not that real estate is bad. The point is that time is a cost of capital, and founders chronically underprice their own hours.
Taxes: Where the Spreadsheets Get Interesting
Stocks in a taxable account are simple: dividends and realized gains show up on the return. Hold long enough and you often get preferential long-term capital gains rates. Inside a retirement account, compounding can be even cleaner.
Investment real estate brings depreciation, deductible expenses, and – when you eventually sell – the chance to defer gain through a like-kind exchange if you follow the rules. That last piece is why serious landlords learn the 1031 exchange rules before they list a property, not after. Depreciation also creates future recapture risk. None of this is DIY tax advice. It is a reason to model after-tax cash flow with a CPA who understands both your operating company and your rentals.
If the only reason you want a rental is “the write-offs,” pause. Tax benefits are a sweetener on a good deal. They are a terrible primary reason to buy a bad one.
A Simple Decision Framework for Business Owners
When a founder asks me real estate vs stocks with a specific dollar amount in hand, I walk them through this checklist:
- Is the operating business stable enough? If revenue still swings wildly, prioritize cash reserves and liquid investments first.
- Do you have 6-12 months of personal and business reserves? If not, neither asset class is the next buy. Cash is.
- How many hours per month can you honestly give a property? If the answer is “none,” default to broad stock index funds or REIT exposure inside a brokerage/retirement account.
- Are you buying for cash flow, appreciation, or education? Pick one primary job for the dollar.
- What is your total leverage across business + personal + property? If one rate spike or slow quarter would stress all three, reduce complexity.
- Can you underwrite the deal on paper before emotion hits? Cap rate, cash-on-cash, reserves, CapEx, vacancy. If you cannot, you are not ready for direct ownership.
A practical split I see work for many owners once the business is durable: keep systematically buying equities every month no matter what, and only add direct real estate when a specific deal clears your underwriting bar and your calendar. That way you are never waiting for the “perfect property” to start compounding.
What Builds Wealth Faster?
For a hands-off business owner with surplus cash and limited spare attention, diversified stocks (and stock-like funds) usually build wealth faster per hour invested – and with far less operational drama.
For an owner who likes systems, will underwrite carefully, and can tolerate illiquidity, a well-bought rental (or a small portfolio) can outpace unlevered stock returns on the equity they put down, especially when leverage, principal paydown, and tax treatment cooperate.
The honest answer for most founders is both, sequenced: protect the company, automate liquid investing, then earn the right to own property by proving you have the time and the underwriting discipline. Real estate vs stocks is not a team jersey. It is a calendar and a balance sheet talking to each other.
Real Estate vs Stocks FAQs
Is real estate or stocks better for building wealth?
It depends on leverage, time, and liquidity. Stocks usually win for passive compounding. Real estate can win on leveraged equity if you buy well and manage it. For busy owners, pick the path that does not starve the company of attention.
Do stocks historically return more than real estate?
Broad U.S. stock indexes have often outpaced raw home-price appreciation over long periods. Real estate investors counter with rent, loan paydown, leverage, and tax effects. Compare total return stacks, not just price charts, and include your time as a cost.
Should a business owner buy a rental before investing in stocks?
Usually no if the business is still unstable or you lack cash reserves. Build liquidity and an automated equity habit first. Add a rental when a specific deal clears underwriting and your calendar can absorb the load without hurting the company.
How does leverage change the real estate vs stocks comparison?
Mortgage leverage lets a down payment control a larger asset, amplifying gains and losses. Stocks are usually bought with cash unless you use margin. Leverage is real estate’s main speed advantage and its main risk when your business already carries debt.
What about REITs instead of owning property directly?
REITs give real-estate exposure with stock-like liquidity and much lower time cost. You give up direct control, some leverage choices, and many hands-on tax tactics. For founders who want property exposure without tenants, REITs are often the saner bridge.

The quality of a credit decision depends on the quality of the information behind it. For commercial real estate lenders, that information has historically arrived late, arrived incomplete, or arrived in formats that required significant manual work before anyone could act on it.
Technology is closing each of those gaps. The Mortgage Bankers Association projects commercial mortgage originations will reach $805.5 billion in 2026, a 27% increase over the prior year. That volume is arriving in a lending environment where, according to Trepp’s August 2026 CMBS delinquency report, published September 3, 2026, the delinquency rate eased slightly to 7.85%, down from 7.86% in July. The gap between lenders managing risk well and those managing it reactively is widening.
Smart Capital Center’s AI agents work across that whole span for lenders: they read borrower files, check figures against 1B+ live market data points, and track covenants and maturity dates after close.
The five changes below are where that shift is most visible in active lending operations today.
What Is Commercial Loan Underwriting Risk Analysis?
Commercial loan underwriting risk analysis is the process by which a lender evaluates whether a commercial real estate loan will perform across its term. It involves assessing the property’s income stability (through NOI, or net operating income, and DSCR, the ratio of NOI to annual debt service), the borrower’s creditworthiness, the collateral’s market value, and the lease structure supporting the income projection. The purpose is to identify, quantify, and price the risk of default before the loan is originated.
Commercial loan underwriting risk analysis has traditionally been a point-in-time exercise; technology is making it a continuous one.
Way 1: AI Agents That Give Credit Teams Traceable Data From the First File
Why Manual Extraction Creates Risk at the Point of Origination
Every commercial real estate loan starts with documents: rent rolls, T-12 income statements, appraisals, offering memorandums, and lease abstracts. In a manual workflow, an analyst reads these documents and re-enters the relevant figures into a credit model. That re-entry process is the most reliable source of errors in commercial loan underwriting, because re-keying data from multi-hundred-page documents under time pressure produces errors at a statistically predictable rate.
Credit judgment has to stay with people. The data that judgment relies on should not pass through a process that introduces transcription errors before the analyst ever sees it.
What Technology Changes Here
AI agents read the borrower’s files directly, pull the figures into the credit model with each one traceable to its source page, and flag discrepancies for the analyst to review. The analyst reviews outputs and exceptions instead of retyping figures, and the credit file keeps a clear record of where every number came from.
Rose Community Capital reviews significantly more applications with greater depth and consistency with Smart Capital Center.
Way 2: Real-Time Market Intelligence Replacing Point-in-Time Research
The Stale Data Problem in Credit Decisions
A credit model built on market data that is 60 to 90 days old describes conditions that may have already shifted materially, particularly in submarkets where vacancy, rent growth, or cap rates are moving. Lenders approving loans on the basis of last quarter’s market research are pricing risk against a picture of the market that may not match the picture a buyer or tenant is responding to today.
What Live Data Integration Provides
Platforms that maintain continuous live connections to submarket vacancy rates, recent comparable transactions, tenant credit events, and alternative data signals allow credit models to reflect current market conditions at the point of decision. The relationship between market data quality and underwriting discipline in CRE financing is direct: the more current the inputs, the more accurately the model prices risk.
Way 3: Portfolio Concentration Visibility That Periodic Reviews Cannot Produce
What Individual Loan Reviews Miss
Quarterly compliance reviews assess individual loans against their specific covenants. They do not assess whether the portfolio as a whole has accumulated concentration risks that only become visible in aggregate: multiple loans maturing in the same quarter, tenant industry concentration across assets, or geographic exposure to a single market where conditions are shifting.
Accountability for a loan book requires visibility across all of it. Portfolio concentration risks that are invisible in individual loan files can only be measured with data aggregated across the full book.
What Technology Produces at Portfolio Scale
The specific concentration risks that only appear at portfolio scale include:
- Loan maturity clusters where multiple assets face refinancing within the same rate environment window
- Tenant industry concentration where a significant share of total portfolio income depends on a sector facing structural headwinds
- Geographic exposure to markets where vacancy is rising or new supply is compressing rents across multiple collateral assets
- Lease expiration concentration where several portfolio assets face simultaneous re-leasing risk
Technology platforms that aggregate lease-level data across the full loan book make these concentrations visible as they develop.
Way 4: Continuous Post-Close Monitoring Replacing Periodic Compliance Cycles
The Detection Lag in Quarterly Reviews
Most CRE lenders operate a quarterly or semi-annual compliance review cycle. The borrower submits financials, a current rent roll, and a compliance certificate. The lender calculates DSCR and checks covenant compliance. If a problem has developed since the last review, the lender finds out when the next package arrives.
The FDIC’s 2026 Risk Review noted that loan modification volume was concentrated among the largest banks. Earlier detection gives any lender a wider set of responses before a modification becomes the only one.
| Risk Condition | Quarterly Review Detection | Continuous Monitoring Detection |
|---|---|---|
| Anchor tenant departure | Next compliance package | Within days of rent roll change |
| DSCR approaching covenant threshold | After quarter-end financials | As income data updates against live model |
| Tenant credit deterioration | When payment issues appear | When business performance signals shift |
| Lease expiration approaching unmonitored | At next scheduled review | At defined alert thresholds (180, 90 days) |
| Submarket vacancy crossing assumption | When reported in market survey | As live submarket data updates |
Illustrative; timing varies by platform configuration and data feed.
What Continuous Monitoring Changes for Lenders
Continuous monitoring converts risk detection from a scheduled activity to an ongoing one. Understanding how real-time loan monitoring fits into a lender’s broader risk framework starts with the recognition that most loan problems develop gradually before they breach any formal threshold.
Way 5: Covenant Compliance Tracking That Generates Alerts Instead of Discovering Breaches
Why Reactive Covenant Monitoring Is a Credit Risk
A covenant is only useful if a lender knows it has been breached before the situation constrains the available responses. A DSCR covenant breached in month three of a quarter but discovered in month four leaves the lender with fewer options than one identified in real time. Deloitte’s 2026 Commercial Real Estate Outlook, a survey of more than 850 C-suite executives at real estate companies with at least $250 million in assets under management across 13 countries, found availability and cost of capital ranked as executives’ top concern, with interest rates staying higher for longer close behind.
How Technology Changes the Covenant Monitoring Process
Technology-driven covenant compliance tracking works by monitoring the conditions that affect each covenant continuously against live data, generating alerts when metrics approach defined thresholds instead of reporting on them after they have crossed. The practical applications include:
- DSCR alerts triggered as income data updates against current debt service, not as trailing financials arrive
- Occupancy monitoring that detects roster changes between compliance packages
- Named anchor tenant alerts triggered when a specified tenant exercises a termination option or files for bankruptcy
- Reserve funding triggers generated when lease expiration concentration reaches a defined threshold within a rolling window
The Risks Technology Does Not Remove
Technology changes how lenders measure commercial real estate risks. It does not change what risk is. Three dimensions remain unchanged regardless of platform sophistication:
- Credit judgment on sponsor quality: No data feed replaces the lender’s assessment of whether a sponsor has the experience, integrity, and operational capacity the deal requires.
- Market conviction on long-term assumptions: Technology provides current data. It does not predict where markets go. Rent growth assumptions, exit cap rate selection, and supply pipeline judgments require informed human conviction that no algorithm produces.
- Relationship-dependent workout options: When a loan goes into stress, the options available to a lender depend significantly on the quality of the relationship with the borrower. Technology cannot build that relationship or substitute for it when it is needed.
Risk Measurement That Compounds in the Right Direction
The lenders applying technology to commercial loan underwriting risk analysis today are accumulating a data advantage that compounds over time. Every loan processed through a platform that maintains source-traceable data, continuous market intelligence, and portfolio-level aggregation adds to a proprietary dataset that makes subsequent underwriting more accurate and subsequent portfolio monitoring more precisely calibrated. The gap between lenders who built this infrastructure before loan volumes accelerated and those who deferred the investment is already visible in detection speed and portfolio performance data. It widens as volume increases.
Glossary
- Debt service coverage ratio (DSCR): A property’s net operating income divided by its annual debt payments; lenders set minimums in the loan covenants.
- Loan covenant: A condition in the loan agreement the borrower must meet, such as a minimum DSCR, occupancy level or reporting deadline.
- Covenant breach: A borrower failing to meet a covenant, which gives the lender the right to require a cure, add reserves or take other action.
- Concentration risk: Exposure that builds when many loans in a book share the same maturity window, property type, market or tenant industry.
- Continuous monitoring: Tracking loan and property conditions against live data between formal reviews, with alerts when a metric nears a threshold.
- CMBS delinquency rate: The share of loans in commercial mortgage-backed securities that are 30 or more days past due.
- Credit memo: The document a credit team prepares to approve a loan, summarizing the property, borrower, risks and recommended terms.
Frequently Asked Questions
How does technology improve commercial loan underwriting risk analysis?
Technology improves risk analysis by addressing the four points where manual workflows produce the most information gaps: document extraction accuracy at origination, market data recency in the credit model, portfolio concentration visibility across the full loan book, and detection speed when conditions change after closing. None of these replaces credit judgment, but all of them improve the information that judgment works from.
What commercial real estate risk factors does continuous monitoring track?
Continuous monitoring tracks DSCR against covenant thresholds as income data updates, tenant credit health against lease payment risk, occupancy changes between formal compliance cycles, lease expiration deadlines approaching without renewal confirmation, and submarket vacancy trends against the assumptions embedded in the original credit model.
How does real-time market data affect commercial real estate risk assessment?
A credit model built on market data that is 60 to 90 days old may not reflect the conditions that determine whether the collateral will support the loan across its term. Live market intelligence integration ensures the market context in the credit model reflects current conditions at the point of decision, instead of conditions from the last available quarterly report.
What is the difference between quarterly covenant compliance reviews and continuous monitoring?
Quarterly reviews reflect conditions as they existed when the borrower submitted a compliance package. Continuous monitoring tracks the conditions that affect each covenant against live data between reviews, generating alerts when thresholds are approached instead of confirming breaches after they have occurred.
Does technology in CRE underwriting reduce the need for experienced credit professionals?
No. Technology addresses the information and process dimensions of risk measurement. The credit judgment dimensions, sponsor assessment, market conviction, assumption validation, and workout strategy, require contextual expertise that experienced professionals apply. What changes is the quality and currency of the information those professionals work from.

How to Quit a Job Professionally (Without Burning the Bridge You’ll Need Later)

How to Ask for a Raise: The Script, the Number and the Timing That Get a Yes

HELOC vs Home Equity Loan: Which One Costs Less (With $50K Payment Math)

Direct vs Indirect Cash Flow Method: Which One a Small Business Should Use

How to Stop Overthinking: 7 Ways to Get Out of Your Head and Make the Call
5 Ways For Startups To Succeed Making Acquisitions

77 Inspirational Quotes That Will Change Your Life

57 Memorable Kobe Bryant Quotes

Motivational Picture Quotes: 52 Images to Inspire a Successful Year
40 Rare Motivational and Inspirational Picture Quotes
3 Prince EA Videos To Change Humanities Path To Greatness
(Video) What Is Success? An Entrepreneurial Story To Inspire You
(Inspirational Video) What If Today You Knew You Were Going To Take Your Last Breath?
How To Make Enough Money From A Blog To Quit Your Job – Kate McKibbin
How Finding Your Passion And Becoming An Entrepreneur Can Lead To Happiness – Chiquita Searle
-

 Did You Know1 year ago
7 Surprising Life Lessons Video Games Taught Me That School Never Did
-
 Life2 years ago
The 5 Stages of a Quarter-Life Crisis & What You Can Do
-
 Success Advice1 year ago
Stephen Covey’s 8 Leadership Habits That Will Change How You Lead Forever
-

 Life1 year ago
How to Stop the War in Your Head and Find Peace
-

 Featured2 years ago
The Psychology of Motivation: How to Keep Moving Forward Every Day
-
 Personal Development2 years ago
The Three-Second Pause That Changes How People Perceive You
-
 Explode Your Social Media1 year ago
Want More Views? Master These 6 YouTube Growth Tactics
-
 Change Your Mindset1 year ago
You Become What You Absorb: How Input Shapes Your Life