Real Estate
How to Get Investment Property Loans Without Tax Returns: The DSCR Playbook


There is a moment almost every successful entrepreneur hits. The business is finally throwing off real cash, you are ready to start building wealth outside the company, and rental property looks like the obvious move. So you walk into your bank, the same bank that has watched six figures flow through your accounts for years, and ask for an investment property loan.
And they turn you down.
Not because you cannot afford it. Because your tax returns, optimized by a good accountant to minimize taxable income, make you look broke on paper. Every write-off that saved you money in April just cost you a mortgage approval. It is one of the great ironies of entrepreneurship: the better your tax strategy, the worse you look to a traditional underwriter.
Here is what the bank did not tell you. There is an entire category of financing built for exactly this situation, and the flagship product is called a DSCR loan. Real estate investors have used these to build portfolios of five, ten, and fifty properties without ever handing over a tax return. This is the playbook.
What a DSCR Loan Actually Is
DSCR stands for debt service coverage ratio. The concept is simple and, once you see it, obviously right: instead of qualifying you based on your personal income, the lender qualifies the property based on its rental income.
The math is a single division problem. Take the property’s monthly rent and divide it by the monthly cost of owning it, meaning principal, interest, taxes, insurance, and any HOA dues. If a property rents for $2,500 and costs $2,000 a month to carry, the DSCR is 1.25. The property earns 25 percent more than it costs. It covers itself.
That is the whole pitch. No tax returns. No W-2s. No employment verification. No explaining to an underwriter why your Schedule C shows a loss while your bank balance grew. The property either pencils or it does not.
Why This Changes the Game for Entrepreneurs
Traditional mortgage underwriting asks one question: does this person’s documented personal income support this payment? DSCR underwriting asks a better question for investors: does this asset support itself?
That reframe has three consequences that matter if you are building something.
First, your tax strategy stays intact. You can keep taking legitimate deductions without sabotaging your borrowing power.
Second, you can scale. With conventional loans, every property you buy adds debt to your personal ratios until you hit a wall, and conventional financing caps how many mortgaged properties you can hold anyway. DSCR lenders care about each deal standing on its own, so the portfolio can keep growing as long as the deals keep working.
Third, you can borrow through your business. Most DSCR lenders will lend to an LLC, which is how experienced investors hold rentals for liability protection anyway. Conventional lenders generally will not.
What You Actually Need to Qualify
DSCR loans are flexible on income and rigid on a few other things. Requirements vary by lender, and guidelines change, so treat these as the typical shape of the box rather than exact walls.
The ratio itself: most lenders want a DSCR at or above 1.0, meaning the rent at least covers the payment, and the best pricing usually starts around 1.2 or 1.25. Some lenders offer no-ratio programs for properties that do not cash flow yet, at a price.
Down payment: plan on 20 to 25 percent. DSCR loans do not come with 5 percent down. The lender’s protection is equity, and they want you to have real skin in the deal.
Credit: minimums commonly land in the 620 to 680 range depending on the lender and the deal, with better scores unlocking better rates and lower down payments.
Reserves: expect to show a few months of payments in the bank after closing, commonly three to six.
The rent number: on a purchase, an appraiser documents market rent on a standard form. For short-term rentals, many lenders now use documented booking history or market data from tools like AirDNA, which has opened DSCR loans to the Airbnb crowd.
Two honest trade-offs. Rates run higher than conventional owner-occupied loans, typically by a point or two, because the lender is taking asset-based risk. And most DSCR loans carry prepayment penalties for the first few years, so know your exit plan before you sign.
The Playbook, Step by Step
Step one, run the numbers before you fall in love. Take realistic market rent, subtract the full carrying cost including taxes, insurance, and HOA, and check the ratio. In high-insurance markets, and I say this as someone who lends heavily in Florida, insurance quotes kill more deals than interest rates do. Get a real quote early.
Step two, get your credit and reserves in order. Those are the two levers you fully control, and both directly move your rate.
Step three, get pre-qualified with a DSCR specialist. This takes days, not weeks, precisely because there is no income documentation to grind through. A broker who works Non-QM loans daily can shop your scenario across many wholesale lenders instead of one bank’s single guideline set.
Step four, make offers knowing DSCR loans close fast. Thirty days is routine, and speed wins deals in competitive markets.
Step five, after closing, keep clean records of the property’s performance, because your next DSCR loan gets easier when the current one is performing.
A Worked Example
Numbers make this concrete, so here is a simplified version of a deal structure we see constantly.
An entrepreneur finds a single-family rental listed at $400,000 in a solid rental market. Market rent, confirmed by the appraiser, is $3,000 a month. She puts 20 percent down and finances $320,000. Say the monthly principal and interest on the loan work out to around $2,200 at prevailing DSCR rates, with taxes, insurance, and no HOA adding roughly $500 more. Total monthly cost: about $2,700.
Divide $3,000 in rent by $2,700 in carrying cost and the DSCR is about 1.11. The property covers itself with a modest cushion. Most DSCR lenders approve that deal, though the pricing improves if she can push the ratio higher, either with a larger down payment that shrinks the loan, or by finding a property where the rent-to-price math is stronger.
Notice what never came up: her tax returns, her business’s chart of accounts, or an underwriter’s opinion about the stability of entrepreneurial income. The property carried the application. That is the entire product in one example, and it is also the discipline of it. If the rent had been $2,400 against the same costs, no amount of personal income would have dressed up a deal that does not cover itself.
The Mistakes That Cost Investors Money
The biggest one is underestimating expenses to force a ratio. The appraisal and the insurance quote will surface the truth anyway, so run honest numbers on day one.
The second is shopping only one lender. DSCR pricing varies widely between lenders for the same deal, far more than conventional pricing does. This is a product where a broker’s access to multiple lenders directly translates to basis points.
The third is ignoring the prepayment penalty structure. If your plan is to renovate, raise rents, and refinance in year one, tell your loan officer up front so the loan is structured for it.
The fourth is quitting your homework at the loan. A DSCR loan finances the deal; it does not fix a bad one. The asset still has to be a good rental in a market with real demand.
Beyond the Rental: Financing the Rest of Your Life
One more thing entrepreneurs figure out quickly. The same documentation problem that blocked your investment property loan also complicates buying your own home. The parallel solution there is a bank statement loan, which qualifies you on the actual deposits flowing through your accounts instead of your tax returns. If your income is real but your returns understate it, it is worth reading up on how bank statement loans work, because the combination of a bank statement loan for your residence and DSCR loans for your rentals is the standard stack for self-employed wealth builders.
Frequently Asked Questions
Do DSCR loans show up on my personal credit? Typically the loan is underwritten to the property and often held in an LLC. Policies on credit reporting vary by lender, so ask. Either way, it will not tangle your personal debt-to-income ratio the way a conventional loan does.
Can I use a DSCR loan for a short-term rental? Many lenders now allow it, using market rent data or your booking history. Expect slightly stricter terms than a long-term rental.
What property types work? Single-family homes, condos, townhomes, and small multifamily like duplexes through fourplexes are standard. Some lenders go larger or handle mixed-use.
Can a first-time investor get one? Yes, though some lenders price experience. Owning your primary residence helps.
What if the property does not cash flow yet? No-ratio and sub-1.0 DSCR programs exist with larger down payments and higher rates. Sometimes that is a smart bridge on a value-add deal; sometimes it is a warning sign about the deal itself.
How fast can these close? Two to four weeks is common, since there is no income documentation to verify.
What markets work best for DSCR deals? Markets where the rent-to-price ratio is healthy enough to clear the ratio comfortably. High-appreciation coastal markets often struggle to cash flow on paper, while stable mid-priced metros pencil easily. Investor-heavy states like Florida, Texas, and Tennessee see the most DSCR volume, but the math, not the map, is what qualifies the deal.
Does rental income from the property count toward my next loan? With DSCR lending, each property qualifies on its own rent, which is exactly why portfolios scale. Your personal debt-to-income never becomes the bottleneck.
Are the rates worth it versus conventional? If you can qualify conventionally and you are under the property cap, conventional is usually cheaper. DSCR wins when tax returns do not tell your real story, when you are scaling past conventional limits, or when you need the LLC and speed advantages.
Can I refinance an existing rental with a DSCR loan? Yes, including cash-out refinances that pull equity from one property to fund the down payment on the next. That recycling of equity is the engine behind most fast-growing rental portfolios.
Do I need an LLC first? No, you can close in your personal name with most lenders. But if you want the LLC, set it up before you go under contract to keep the closing clean.
The Bottom Line
The entire game of building wealth through real estate depends on access to financing, and for self-employed people the traditional system is quietly rigged against you. DSCR loans un-rig it. They judge the deal, not your tax strategy, which is how it should have worked all along.
Guidelines and requirements shift over time, so verify current terms with your lender before committing. If you want to know exactly what you would qualify for, the team at Select Home Loans specializes in DSCR and self-employed lending and can price your scenario across dozens of wholesale lenders. If you need help, you can call Nick at (888) 550-3296 and bring him a deal. That first property is the hardest one; it gets easier from there.








A cheaper house is not a cheaper life. If you are moving for the work, or buying because the rent finally annoyed you, two Texas towns can show you the same three-bedroom and cost hundreds a month apart. The gap is usually the tax roll, not the listing photo. The notes below are the hour of math worth doing before you sign, including the mistakes that only show up the following January.
A $185,000 house in two different Texas towns can cost you $340 a month apart. Same square footage. Same three-bedroom layout. Same sunset over the same flat horizon. The difference lives almost entirely in the tax roll, and most buyers never look there until the bill shows up the following January.
I’ve watched friends move to what looked like the bargain of the decade, only to get wrecked by an appraisal district that valued their new home $60,000 above what they paid for it. So here’s the deal: this piece walks you through what actually drives affordability in Texas, which types of cities tend to stay cheap and why, and how to run the numbers yourself before you sign anything. No fluff, no realtor cheerleading. Just the math, plus the mistakes I’d avoid if I were buying again.
The list price is the smallest number on the page
Almost everyone starts their search on Zillow, sorts by price, and picks a favorite. That’s the wrong first move. The mortgage payment is fixed by the loan terms, but the escrow portion, which covers property taxes and insurance, is the line item that moves the most from city to city.
Think about what an extra 0.5% in combined tax rate does over ten years. On a $250,000 home, that’s roughly $12,500 in additional payments, money that never builds equity and never comes back. Buyers who skip this step often discover the gap only after closing, when the first full escrow analysis lands and their payment jumps.
There’s also no state income tax in Texas, which matters here. According to the State of Texas, the state doesn’t levy a personal income tax, so local governments lean on property taxes and sales taxes to fund roads, schools, and emergency services. That structure is exactly why two neighboring towns can carry very different rates.
What actually keeps a Texas town cheap
Affordability isn’t luck. It comes from a handful of structural conditions, and when you know them, you can predict which markets will stay reasonable and which are about to climb.
- Room to build. When there’s plenty of undeveloped land and zoning that allows new subdivisions, supply keeps pace with demand and prices stay grounded.
- Stable or declining tax bases. Cities without a booming commercial sector often hold rates steady out of necessity. That cuts both ways, but it can keep your escrow predictable.
- Lower utility and fuel costs. Texas has a deregulated electricity market, and in many smaller cities, power and water run well below national averages.
- Job markets that aren’t overheating. A town with steady, modest employment growth rarely sees the bidding wars that spike home values.
Notice what’s not on that list: cheap sticker prices. A town with $120,000 homes and a punishing tax rate can cost more per year than one with $180,000 homes and a mild one. I’d take the second town every single time, and I don’t think it’s close.
Where the numbers tend to land
If you look at long-running patterns, the affordable tier of Texas tends to cluster in specific regions. The Rio Grande Valley, the Panhandle, and parts of West Texas and the Coastal Bend consistently show home values well below the state median. Cities in those areas typically share a few traits: smaller job markets, older housing stock, and less in-migration pressure.
Sit down and compare those cities against statewide averages. According to the U.S. Census Bureau, median home values and household incomes vary dramatically across Texas metros, and the gap between the priciest and most affordable markets is wide. That gap is your opportunity, if you’re willing to trade some conveniences for a smaller payment.
What you get in exchange for the lower number: fewer restaurant options, longer drives to a real airport, and a slower pace. Some people love it. Others move back within two years. Be honest with yourself about which camp you’re in before you commit, because relocation regret is expensive.
Run this five-step check before you make an offer
This is the part I wish someone had handed me years ago. It takes about an hour per city and it will save you thousands.
- Pull the actual tax rate, not the estimate. County appraisal district websites publish the adopted rate for every taxing unit that touches a property, including the city, county, school district, and any special districts. Add them all up. The listing agent’s estimate often skips one or two.
- Check the homestead exemption rules. Texas offers a general homestead exemption on school taxes, and many local entities add their own. A town with generous local exemptions can beat a town with a lower headline rate.
- Compare the appraisal history, not just the tax rate. Look at how valuations in that neighborhood moved over the past five years. Rapid increases signal a district that’s aggressive about reassessment.
- Add insurance and utilities. Wind and hail coverage in coastal or storm-prone areas can run several times what it costs inland. Get a real quote before you fall in love with a house.
- Stress tests the payment. Assume your appraisal comes in 10% above your purchase price, because it sometimes does, and see whether the number still works. If it doesn’t, keep looking.
The full picture of what a move really costs, including the tax side, is worth studying before you narrow your list, and the analysis behind the cheapest place to live often comes down to how aggressively each county values property rather than the sticker price itself.
Watch what your county does after you buy
The work doesn’t stop at closing. Texas appraisal districts reassess annually, and your notice arrives in the spring. A valuation that jumps faster than the market is a signal worth acting on, because an inflated assessment compounds every year you own the home.
The Texas Comptroller of Public Accounts publishes guidance on how property values are determined and what options homeowners have when they disagree with an assessment. Read it before you need it. Deadlines for filing a protest are strict, and they don’t care that you were busy that month.
The same habit shows up in getting the money right before a number becomes a bill.
Here’s my honest read: most people overpay on taxes because they never question the number. They assume the district is right. Districts are working from mass appraisal models, not a walkthrough of your kitchen, and those models get things wrong. Cracks in the foundation, a busy road behind the fence, a roof that needs replacing. None of that shows up in a formula.
Pick the town, then defend the number
Cheap places to live in Texas share a pattern you can spot from your laptop: land to build on, moderate rates, and appraisals that don’t sprint ahead of reality. Find those three, and your monthly payment behaves itself.
So before you tour a single house, spend an evening with the appraisal district sites for your top three towns. Add up every taxing unit. Check the exemptions. Run the stress test. It’s the least glamorous homework in real estate, and it’s the one that keeps your escrow from surprising you every March. Which town on your list have you actually verified?
A probate home can seem like a good way to buy a home at a fair price. Yet a sale tied to an estate can have risks that do not show up at first glance. A fake will, a bad deed, or a conflict over who has the right to sell can put the deal at risk. If a buyer has a fear of fraud, will fraud solicitors can help check the facts and set out the next step. The key is to act with care. You should not send a large sum or sign a deal just on trust. A few smart checks can help you spot a risk, helping you make the right decisions.
In this article, we will discuss in detail how you can watch for potential risks when buying probate property.
Understanding Probate Property and Will Fraud
A probate home is one that forms part of a deceased person’s estate and is dealt with by a will or by the rules of no will. The key point for a buyer is simple. The sale must be done by a person who has the legal right to deal with the home. If a will is there, the named representative may need a grant of probate to show they have the right to act for the estate. If there is no valid will, a grant of letters of admin may be used in some cases.
Remember, will fraud can take many forms. It may mean a will was made with a fake signature. It may be a fake document. It may also mean a real will was changed in a way that was not valid. A buyer does not need to be a will law professional to spot a risk. The first step is to ask who has the right to sell. Moreover, ask for proof of death, will, grant, seller’s role, title for the home, and any key court act tied to the sale. If the sale is made by more than one person, check that all who need to act are part of the deal.
Major Red Flags to Avoid
Fraud does not always look like a fake document. Some signs may be small but still worth a pause. You should take care if the seller is keen to rush you. Keep in mind that it is a good sign to slow down and check the file. You must look out for:
- A will that has no clear date
- Odd or poor sign marks
- A will that is hard to read or has key edits
- A sale price far below the fair home value
- A new will that cuts out a close family member
- A title that does not fit the sale story
However, none of these facts alone proves fraud. A low price may have a sound reason, a late will may be valid, and a title may have a past issue that can be fixed. The point is to ask more questions when the facts do not line up.
Legal and Financial Consequences
The worst time to spot a will fraud is after you have paid a large sum. If a will is said to be fake or is under a court case, the sale may face a delay. In some cases, the right to sell may be in doubt until the case is dealt with. That can lead to extra costs, and you may face:
- Extra legal fees
- A late moving date
- Loan cost
- Survey cost
- Rent on your old home
- Loss of a good loan deal
How to Protect Yourself
A safe sale starts with good care. You should use your own legal representative and do not rely only on the seller who acts for the estate. Your legal team can check the title, sale terms, and proof of the right to sell. Moreover, ask for key proof early. It is far easier to deal with a red flag before you sign than once cash has moved.
Key Takeaways
Buying a probate home can work well, but the estate side needs as much care as the bricks and land. Do not let a low price push you past key checks. You must find out who can sell. Then, check the will and grant. Also, look at the title, and ask key questions when facts are not clear. Moreover, if a will is said to be fake, pause the deal and get legal help. A short delay at the start can be far less costly than a long fight after cash has been paid. I hope this helps you to understand how you can buy a home and have the knowledge that will protect you.
Legal Disclaimer:
Please be advised that this article is for informational purposes only and should not be used as a substitute for advice from a trained legal professional. Probate, land sale, title, and will law can vary with the facts of each case. This guide does not give legal, tax, or home-buying advice. A buyer who is dealing with a will fraud or a fake will should seek advice from a qualified legal professional before taking any key step.
Bakersfield broke from the rest of California’s housing market in 2026. The median home price is $418,000, up just 0.8% year over year, and homes still sell in about 33 days. That combination pulled in buyers who had spent years priced out of coastal markets, and builders answered with hundreds of new communities across the city.
Many of those buyers walked in expecting a straightforward deal. Nationally, 74% of first-time homebuyers say they’d take a 50-year mortgage just to make a payment work. In Bakersfield, the sign out front looked like the easier path. Then they sat down at the closing table, where the number on the sign turned out to be just the starting point.
The Sticker Price Doesn’t Include Everything
The price on the sign rarely reflects what you will pay. New construction buyers end up 15% to 25% above the advertised base price once lot premiums, upgrades, and add-ons stack up at closing. As per Houzeo’s housing market data, 33.33% of Bakersfield homes sold above the asking price in 2026, up from 32.79% last year.
Every new home in California carries a cost many buyers don’t expect. Title 24, the state’s building energy code, requires solar panels on all newly built homes. The California Energy Commission puts the added cost at roughly $9,500 per home. Lot premiums add further cost, and builders often leave landscaping out of the sale.
Model homes exist to sell you on upgrades. According to the National Association of Home Builders, 64% of builders are now offering incentives because the base price alone isn’t closing deals.
Also, the monthly HOA fee follows the buyer for the life of ownership. Around 67.9% of the newly constructed homes carry one. The national median for HOA fees reached $135 a month in 2025. Together, these costs can push a home priced in the high $300,000s well past the number on the sign. None of that touches the mortgage rate itself, which is where builders make their next move.
That Builder Buydown Is Real, But So Is The Trap
Builders in Bakersfield know buyers are watching rates. New construction communities across the city now advertise “2/1 buydowns” to draw people in. Builders like KB Home, D.R. Horton, and K. Hovnanian offer structures that push the first-year rate down to 2.99%. That’s a legitimate tool. It can make a new build cheaper than a same-priced resale home with no incentives attached.
However, the real issue isn’t the buydown itself. It’s who is using it. A 2/1 structure works if your income grows or you plan to refinance. It becomes risky if you’re buying at your financial limit while counting on that lower rate to hold up your budget. If you haven’t run the numbers at the full rate, you don’t know what you’re actually signing up for.
The builder’s representative has a job to sell the house, and they won’t do that calculation for you. Platforms like Houzeo let buyers compare new construction pricing against resale homes in the same ZIP code before signing anything.
This is why bringing an independent agent into the purchase matters. You need someone whose paycheck depends on you, not on moving the builder’s inventory. That same independence matters just as much once you look at where these homes actually sit on the map
Location Is Doing The Real Pricing Here
When you actually map Bakersfield real estate, the pattern becomes clear. Affordable new construction concentrates in the southeast and southwest parts of the city. That’s far from the established northwest corridor, where buyers find stronger school districts and neighborhoods with decades of resale history.
The price data reflects this division. Northwest homes average $454,800, while southwest homes average $389,900. That $75,000 gap reflects the school performance and the equity growth a first-time buyer can expect. Buying in the southwest is a different investment, not a worse one.
For a first-time buyer building equity from scratch, that difference matters. That gap also changes who gets called a first-time buyer here in the first place.
The New Math Behind Entry-Level
The “entry-level” label has moved out of reach in Bakersfield. New construction here is not expensive by California standards, but builders have changed what it means to be a first-time buyer. A move-in-ready new build in the high $300,000s now requires solid credit, a saved down payment, and a cash cushion to cover the solar mandate and upgrades.
Renters in Bakersfield with decent income are not priced out, but the market keeps pushing them to its edges. Bakersfield is supposed to be one of California’s last affordable options, and this trend threatens that status. Buying a home here means looking past the price on the sign and doing the math on your life after closing.
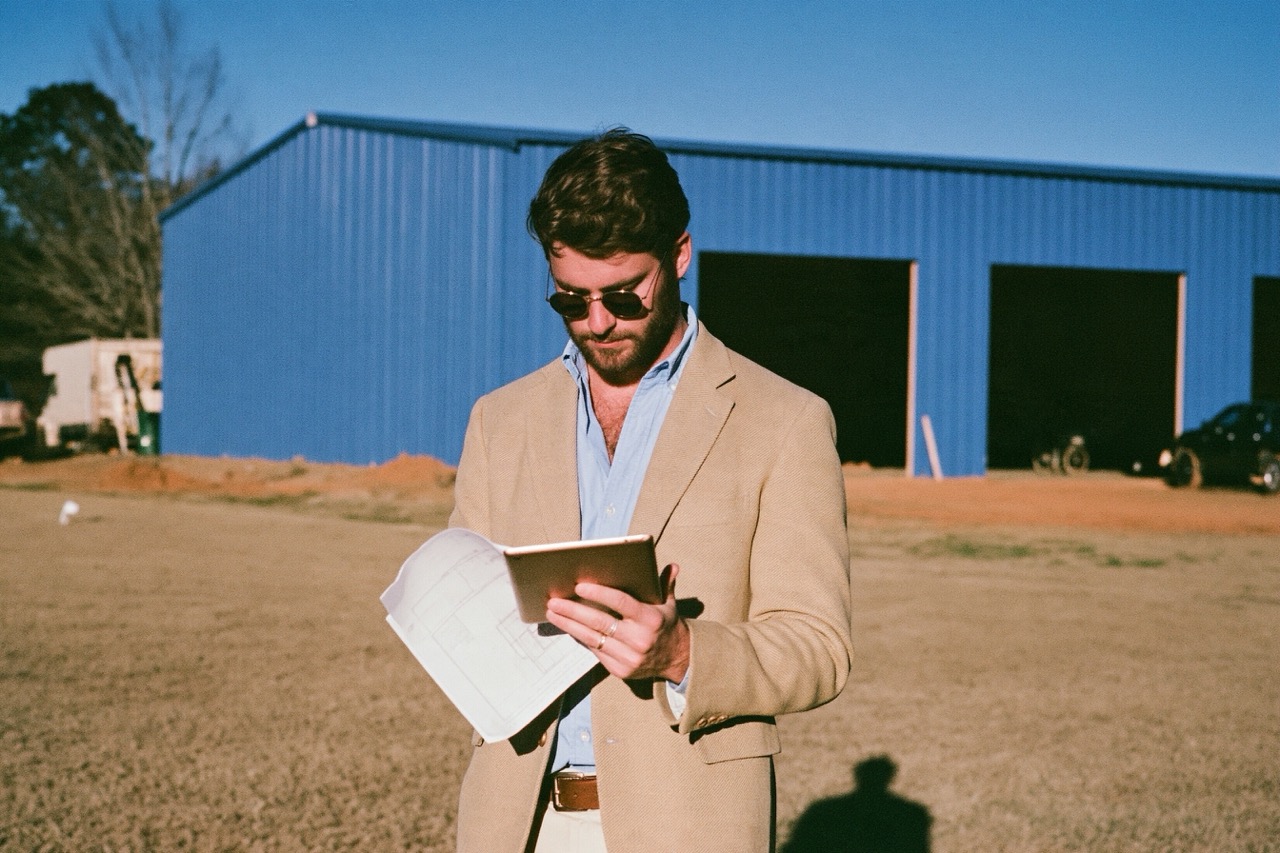
A new workshop or storage space is a major asset for any property. Success depends on a solid plan and a focus on long-term utility. Many homeowners choose metal structures because steel offers a level of strength that wood cannot match. A well-prepared site and a clear vision for the interior layout lead to a smooth project. Every detail from the foundation to the roof pitch matters when the goal is a permanent and safe facility for vehicles and tools.
Many people select prefab garage kits to save time and reduce labor costs. These packages arrive with every component ready for a fast setup. However, a few common errors can stall progress or lead to extra expenses. This article highlights the most frequent pitfalls to avoid and provides a clear path to a successful build.
1. Avoid Inadequate Size and Space Planning
A common error is the choice of a footprint that is too small for future requirements. A garage must hold more than just a car. It often serves as a home for lawn equipment, seasonal decorations, and workbenches. If the dimensions are too tight, the interior becomes a cluttered and unsafe environment.
- Measure the length and width of every vehicle with the doors open.
- Leave at least three feet of space between the wall and the workbench.
- Plan for vertical storage to keep the floor clear of small items.
- Factor in the space needed for a furnace or a water heater.
2. Prevent Legal Issues with Permit Research
Every municipality has specific rules about where a structure can sit on a lot. These setback laws prevent disputes with neighbors and ensure access for emergency vehicles. A failure to check these codes before the start of a project can result in a legal order to move the building. It is also vital to confirm the snow load and wind speed requirements for the region. A structure must be tough enough to handle the local climate without any risk of collapse.
3. Bypass Foundation and Anchor Bolt Errors
The slab of concrete is the most critical part of the entire project. If the foundation is not perfectly level, the steel frame will not align correctly. This leads to gaps in the walls or a roof that does not seal. Precision is essential when the team sets the anchor bolts into the wet concrete. If these bolts are even an inch out of place, the columns will not fit. A professional contractor with experience in metal structures is a great asset during this phase of the work.
4. Eliminate Climate Control and Ventilation Oversights
A steel structure needs to breathe to prevent moisture buildup on the interior surfaces. Condensation can damage tools and vehicles over time. Many prefab garage kits offer options for roof vents and wall louvers to keep air moving. Insulation is another important factor if the space will serve as a workshop during the winter months. High-quality panels keep the heat inside and reduce the noise from heavy machinery or rain. These additions make the space a comfortable place to work all year round.
A successful metal building project brings a sense of pride and a lot of extra space. By avoiding these common mistakes, a property owner ensures that the new structure is a perfect fit for every need. Steel remains the best choice for a durable and low-maintenance facility that stands the test of time. A clear plan and a focus on detail lead to a professional result that serves the household for many years. This proactive approach turns a simple project into a valuable and lasting investment for the future.

Strategic Career Moves: How Top Talent Stays Ahead in a Fast-Changing Market

Building an Enterprise Mobile App: What Separates the Ones People Keep From the Ones They Delete

The Hidden Vulnerabilities of Small Business IT (And How Managed Services Fix Them)

What to do when you are busy and nothing is moving

How AI and Tech Are Quietly Reshaping the Way Students Learn

5 Ways For Startups To Succeed Making Acquisitions

77 Inspirational Quotes That Will Change Your Life
57 Memorable Kobe Bryant Quotes

(Images) 52 Motivational Picture Quotes For An Epic Year Of Success
40 Rare Motivational and Inspirational Picture Quotes

3 Prince EA Videos To Change Humanities Path To Greatness

(Video) What Is Success? An Entrepreneurial Story To Inspire You

(Inspirational Video) What If Today You Knew You Were Going To Take Your Last Breath?

How To Make Enough Money From A Blog To Quit Your Job – Kate McKibbin

How Finding Your Passion And Becoming An Entrepreneur Can Lead To Happiness – Chiquita Searle
-
 Life2 years ago
The 5 Stages of a Quarter-Life Crisis & What You Can Do
-

 Did You Know1 year ago
7 Surprising Life Lessons Video Games Taught Me That School Never Did
-
 Success Advice1 year ago
Stephen Covey’s 8 Leadership Habits That Will Change How You Lead Forever
-

 Life1 year ago
How to Stop the War in Your Head and Find Peace
-

 Featured2 years ago
The Psychology of Motivation: How to Keep Moving Forward Every Day
-
 Personal Development1 year ago
The Three-Second Pause That Changes How People Perceive You
-
 Explode Your Social Media1 year ago
Want More Views? Master These 6 YouTube Growth Tactics
-
 Change Your Mindset1 year ago
You Become What You Absorb: How Input Shapes Your Life