Real Estate
What a $150,000 budget actually buys in Thailand property


If you run a location-independent business, a $150,000 property budget in Thailand is real money. It is not “starter” money in the way a lot of Instagram posts make it sound. It is enough to own something in every major market. It is not enough to own the same thing twice.
Thailand currently has 3,237 listings starting at $117,000. Your budget clears the entry point with room to spare. What it does not do is buy the same product in Phuket, Pattaya, Samui and Bangkok. Anyone comparing Thailand real estate for sale prices quickly sees the gap has almost nothing to do with construction quality and everything to do with land, supply and how each market grew up.
Entrepreneurs who treat this like a lifestyle purchase first and an asset second usually get the sequence backwards. Decide the trade-off before you fall in love with a brochure.
The inventory is not evenly spread
Pattaya has the deepest stock and the softest prices. Of the 1,903 apartments listed nationwide, 1,237 sit in Pattaya. Phuket has 405. Bangkok has 202. Samui has 35.
That concentration matters more than any headline average. A market with a thousand comparable units gives you leverage, alternatives and a reference price. A market with thirty-five gives you none of those. The asking price starts to look like a fixed number rather than an opening position.
Phuket sits at the other extreme. The island lists 888 properties across all types. By the first quarter of 2026 its condominiums averaged above 85,000 baht per m² — about $2,400 — after adding more than 14% in two years. Bangkok is a different calculation again. It is priced as a working capital city, not a resort. You can still find projects from $85,000 in the outer districts, while branded residences in the centre run past $1.2 million.
What the same $150,000 actually reaches
On Phuket that figure lands in the one-bedroom band of most new projects. A unit 500 m from Porto de Phuket in Bang Tao starts at $88,000. A Kamala project starts from $126,000. A Surin scheme with a co-working floor starts from $131,000. A Nai Yang building 400 m from the beach starts from $118,000.
Two-bedrooms in the same buildings start at $199,000, $243,000, $229,000 and $222,000. They are out of reach.
In Pattaya the budget stretches further. A high-rise near Jomtien Beach starts at $121,000. A green-belt project with a co-working area starts from $96,000. A seafront tower starts from $150,000. You can get one or two bedrooms, some of them close to the water.
Samui and the villa market are a different conversation. Houses on the island start around $300,000. Nothing in this budget reaches them.
| Market | What $150,000 reaches | Depth of stock | Trade-off |
| Pattaya | One or two bedrooms, some near the sea | 1,237 apartments | Volume of competing resale later |
| Phuket | One bedroom in a new project, off-plan | 405 apartments | Highest price per m², strongest demand |
| Bangkok | One bedroom outside the central districts | 202 apartments | City rhythm, not a resort |
| Samui | Below the entry price for a house | 35 apartments | Thin stock, little room to compare |
The honest version is simple. $150,000 is a one-bedroom budget in the strong markets and a two-bedroom budget in the deep ones. You do not get both the resort and the extra bedroom in the same place.
The number on the listing is not the cost of the purchase
A transfer fee of 2% of the assessed value applies. It is usually split between buyer and seller, though the split is negotiable and worth agreeing in writing. The temporary reduced rate of 0.01% that ran until 30 June 2026 applied only to Thai nationals. Foreign buyers were always paying the standard figure.
Ownership structure is the larger issue. A foreign buyer can hold a condominium unit freehold, but only within the 49% of a building’s total floor area that the law allows foreigners to own. That quota is measured by area, not by unit count.
Land and the houses on it cannot be held directly. That is why villas are structured through a lease or a Thai company. The lease route changed in March 2025. A Supreme Court ruling removed the automatic enforceability of the 30+30+30 renewals that guides had promised for years. A 30-year term is a 30-year term. Any extension beyond it is a commercial expectation, not a legal guarantee.
Off-plan dominates the entry segment. Colliers expects new condominium supply on Phuket to slow to 6,000–8,000 units in 2026 after almost 25,000 in two years. That eases some of the price competition. It does nothing for a buyer already committed to a building that completes in 2029.
The checks that actually change the arithmetic
These are the questions that separate a clean purchase from an expensive lesson:
- Confirm the remaining foreign quota in the specific building, not the project. A scheme can sell out its foreign allocation in one tower while another still has room.
- Read the completion date on the contract rather than the brochure. Check what the developer owes if it slips.
- Ask what the monthly common-area fee is per m². Two buildings with identical prices can differ by a third in running costs.
- Compare price per m² inside one district before you compare across districts. A Bang Tao figure and a Nai Yang figure answer different questions.
- Budget for furniture in projects sold bare. In the entry segment that can add 10–15% to the total.
- Check who manages the building after handover. The developer and the manager are often unrelated companies.
Comparing the four markets side by side is easier when the listings carry their prices, completion dates and unit counts in the same format. The Thailand section on Tranio filters by region, type and price band. That makes the difference between a Pattaya tower and a Phuket project visible before anyone books a viewing trip.
$150,000 is a real budget in Thailand. It is not a magic number that delivers the same outcome everywhere. Decide first whether the priority is the resort or the size of the home. Then check the quota, the lease and the completion date before the deposit leaves the account. The number on the listing will be a lot closer to the number the purchase actually costs.








A probate home can seem like a good way to buy a home at a fair price. Yet a sale tied to an estate can have risks that do not show up at first glance. A fake will, a bad deed, or a conflict over who has the right to sell can put the deal at risk. If a buyer has a fear of fraud, will fraud solicitors can help check the facts and set out the next step. The key is to act with care. You should not send a large sum or sign a deal just on trust. A few smart checks can help you spot a risk, helping you make the right decisions.
In this article, we will discuss in detail how you can watch for potential risks when buying probate property.
Understanding Probate Property and Will Fraud
A probate home is one that forms part of a deceased person’s estate and is dealt with by a will or by the rules of no will. The key point for a buyer is simple. The sale must be done by a person who has the legal right to deal with the home. If a will is there, the named representative may need a grant of probate to show they have the right to act for the estate. If there is no valid will, a grant of letters of admin may be used in some cases.
Remember, will fraud can take many forms. It may mean a will was made with a fake signature. It may be a fake document. It may also mean a real will was changed in a way that was not valid. A buyer does not need to be a will law professional to spot a risk. The first step is to ask who has the right to sell. Moreover, ask for proof of death, will, grant, seller’s role, title for the home, and any key court act tied to the sale. If the sale is made by more than one person, check that all who need to act are part of the deal.
Major Red Flags to Avoid
Fraud does not always look like a fake document. Some signs may be small but still worth a pause. You should take care if the seller is keen to rush you. Keep in mind that it is a good sign to slow down and check the file. You must look out for:
- A will that has no clear date
- Odd or poor sign marks
- A will that is hard to read or has key edits
- A sale price far below the fair home value
- A new will that cuts out a close family member
- A title that does not fit the sale story
However, none of these facts alone proves fraud. A low price may have a sound reason, a late will may be valid, and a title may have a past issue that can be fixed. The point is to ask more questions when the facts do not line up.
Legal and Financial Consequences
The worst time to spot a will fraud is after you have paid a large sum. If a will is said to be fake or is under a court case, the sale may face a delay. In some cases, the right to sell may be in doubt until the case is dealt with. That can lead to extra costs, and you may face:
- Extra legal fees
- A late moving date
- Loan cost
- Survey cost
- Rent on your old home
- Loss of a good loan deal
How to Protect Yourself
A safe sale starts with good care. You should use your own legal representative and do not rely only on the seller who acts for the estate. Your legal team can check the title, sale terms, and proof of the right to sell. Moreover, ask for key proof early. It is far easier to deal with a red flag before you sign than once cash has moved.
Key Takeaways
Buying a probate home can work well, but the estate side needs as much care as the bricks and land. Do not let a low price push you past key checks. You must find out who can sell. Then, check the will and grant. Also, look at the title, and ask key questions when facts are not clear. Moreover, if a will is said to be fake, pause the deal and get legal help. A short delay at the start can be far less costly than a long fight after cash has been paid.
Legal Disclaimer:
Please be advised that this article is for informational purposes only and should not be used as a substitute for advice from a trained legal professional. Probate, land sale, title, and will law can vary with the facts of each case. This guide does not give legal, tax, or home-buying advice. A buyer who is dealing with a will fraud or a fake will should seek advice from a qualified legal professional before taking any key step.
Bakersfield broke from the rest of California’s housing market in 2026. The median home price is $418,000, up just 0.8% year over year, and homes still sell in about 33 days. That combination pulled in buyers who had spent years priced out of coastal markets, and builders answered with hundreds of new communities across the city.
Many of those buyers walked in expecting a straightforward deal. Nationally, 74% of first-time homebuyers say they’d take a 50-year mortgage just to make a payment work. In Bakersfield, the sign out front looked like the easier path. Then they sat down at the closing table, where the number on the sign turned out to be just the starting point.
The Sticker Price Doesn’t Include Everything
The price on the sign rarely reflects what you will pay. New construction buyers end up 15% to 25% above the advertised base price once lot premiums, upgrades, and add-ons stack up at closing. As per Houzeo’s housing market data, 33.33% of Bakersfield homes sold above the asking price in 2026, up from 32.79% last year.
Every new home in California carries a cost many buyers don’t expect. Title 24, the state’s building energy code, requires solar panels on all newly built homes. The California Energy Commission puts the added cost at roughly $9,500 per home. Lot premiums add further cost, and builders often leave landscaping out of the sale.
Model homes exist to sell you on upgrades. According to the National Association of Home Builders, 64% of builders are now offering incentives because the base price alone isn’t closing deals.
Also, the monthly HOA fee follows the buyer for the life of ownership. Around 67.9% of the newly constructed homes carry one. The national median for HOA fees reached $135 a month in 2025. Together, these costs can push a home priced in the high $300,000s well past the number on the sign. None of that touches the mortgage rate itself, which is where builders make their next move.
That Builder Buydown Is Real, But So Is The Trap
Builders in Bakersfield know buyers are watching rates. New construction communities across the city now advertise “2/1 buydowns” to draw people in. Builders like KB Home, D.R. Horton, and K. Hovnanian offer structures that push the first-year rate down to 2.99%. That’s a legitimate tool. It can make a new build cheaper than a same-priced resale home with no incentives attached.
However, the real issue isn’t the buydown itself. It’s who is using it. A 2/1 structure works if your income grows or you plan to refinance. It becomes risky if you’re buying at your financial limit while counting on that lower rate to hold up your budget. If you haven’t run the numbers at the full rate, you don’t know what you’re actually signing up for.
The builder’s representative has a job to sell the house, and they won’t do that calculation for you. Platforms like Houzeo let buyers compare new construction pricing against resale homes in the same ZIP code before signing anything.
This is why bringing an independent agent into the purchase matters. You need someone whose paycheck depends on you, not on moving the builder’s inventory. That same independence matters just as much once you look at where these homes actually sit on the map
Location Is Doing The Real Pricing Here
When you actually map Bakersfield real estate, the pattern becomes clear. Affordable new construction concentrates in the southeast and southwest parts of the city. That’s far from the established northwest corridor, where buyers find stronger school districts and neighborhoods with decades of resale history.
The price data reflects this division. Northwest homes average $454,800, while southwest homes average $389,900. That $75,000 gap reflects the school performance and the equity growth a first-time buyer can expect. Buying in the southwest is a different investment, not a worse one.
For a first-time buyer building equity from scratch, that difference matters. That gap also changes who gets called a first-time buyer here in the first place.
The New Math Behind Entry-Level
The “entry-level” label has moved out of reach in Bakersfield. New construction here is not expensive by California standards, but builders have changed what it means to be a first-time buyer. A move-in-ready new build in the high $300,000s now requires solid credit, a saved down payment, and a cash cushion to cover the solar mandate and upgrades.
Renters in Bakersfield with decent income are not priced out, but the market keeps pushing them to its edges. Bakersfield is supposed to be one of California’s last affordable options, and this trend threatens that status. Buying a home here means looking past the price on the sign and doing the math on your life after closing.
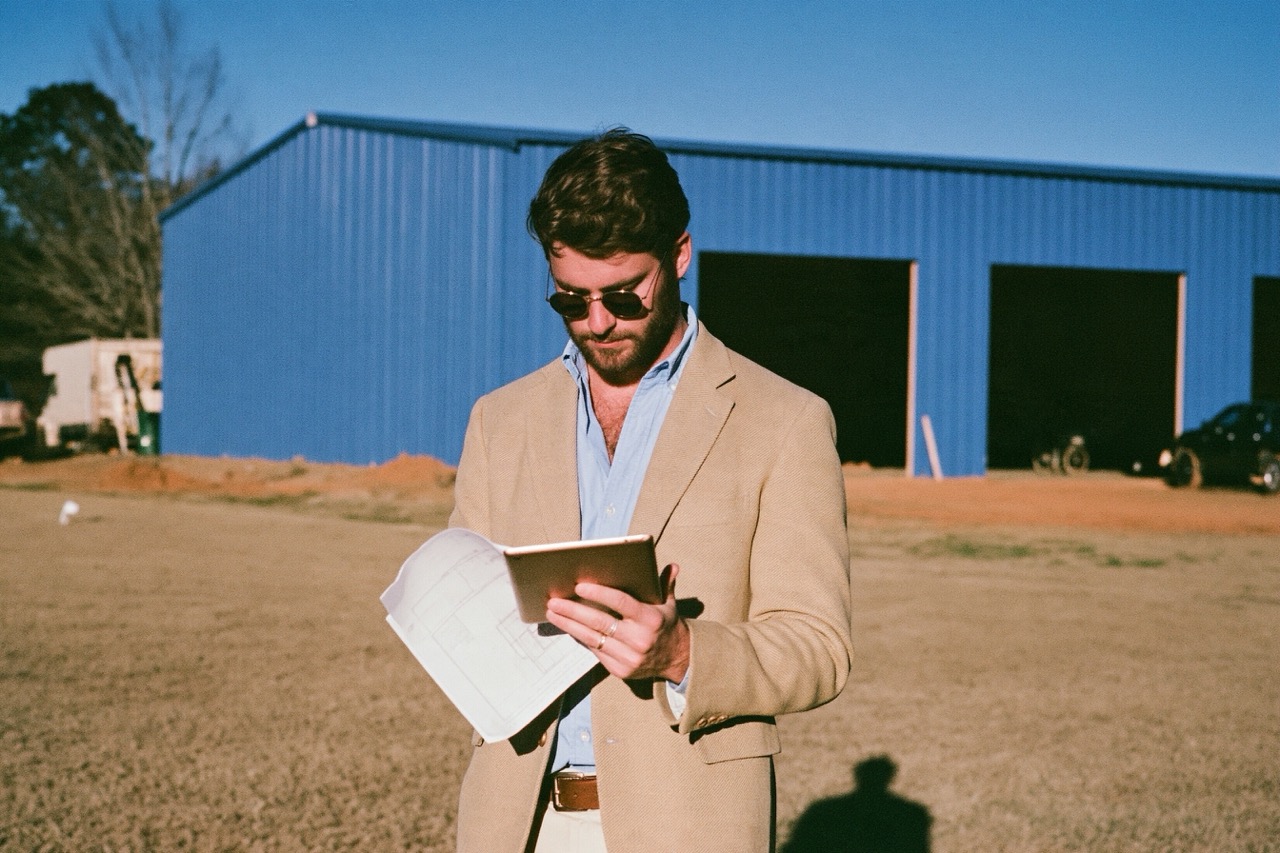
A new workshop or storage space is a major asset for any property. Success depends on a solid plan and a focus on long-term utility. Many homeowners choose metal structures because steel offers a level of strength that wood cannot match. A well-prepared site and a clear vision for the interior layout lead to a smooth project. Every detail from the foundation to the roof pitch matters when the goal is a permanent and safe facility for vehicles and tools.
Many people select prefab garage kits to save time and reduce labor costs. These packages arrive with every component ready for a fast setup. However, a few common errors can stall progress or lead to extra expenses. This article highlights the most frequent pitfalls to avoid and provides a clear path to a successful build.
1. Avoid Inadequate Size and Space Planning
A common error is the choice of a footprint that is too small for future requirements. A garage must hold more than just a car. It often serves as a home for lawn equipment, seasonal decorations, and workbenches. If the dimensions are too tight, the interior becomes a cluttered and unsafe environment.
- Measure the length and width of every vehicle with the doors open.
- Leave at least three feet of space between the wall and the workbench.
- Plan for vertical storage to keep the floor clear of small items.
- Factor in the space needed for a furnace or a water heater.
2. Prevent Legal Issues with Permit Research
Every municipality has specific rules about where a structure can sit on a lot. These setback laws prevent disputes with neighbors and ensure access for emergency vehicles. A failure to check these codes before the start of a project can result in a legal order to move the building. It is also vital to confirm the snow load and wind speed requirements for the region. A structure must be tough enough to handle the local climate without any risk of collapse.
3. Bypass Foundation and Anchor Bolt Errors
The slab of concrete is the most critical part of the entire project. If the foundation is not perfectly level, the steel frame will not align correctly. This leads to gaps in the walls or a roof that does not seal. Precision is essential when the team sets the anchor bolts into the wet concrete. If these bolts are even an inch out of place, the columns will not fit. A professional contractor with experience in metal structures is a great asset during this phase of the work.
4. Eliminate Climate Control and Ventilation Oversights
A steel structure needs to breathe to prevent moisture buildup on the interior surfaces. Condensation can damage tools and vehicles over time. Many prefab garage kits offer options for roof vents and wall louvers to keep air moving. Insulation is another important factor if the space will serve as a workshop during the winter months. High-quality panels keep the heat inside and reduce the noise from heavy machinery or rain. These additions make the space a comfortable place to work all year round.
A successful metal building project brings a sense of pride and a lot of extra space. By avoiding these common mistakes, a property owner ensures that the new structure is a perfect fit for every need. Steel remains the best choice for a durable and low-maintenance facility that stands the test of time. A clear plan and a focus on detail lead to a professional result that serves the household for many years. This proactive approach turns a simple project into a valuable and lasting investment for the future.
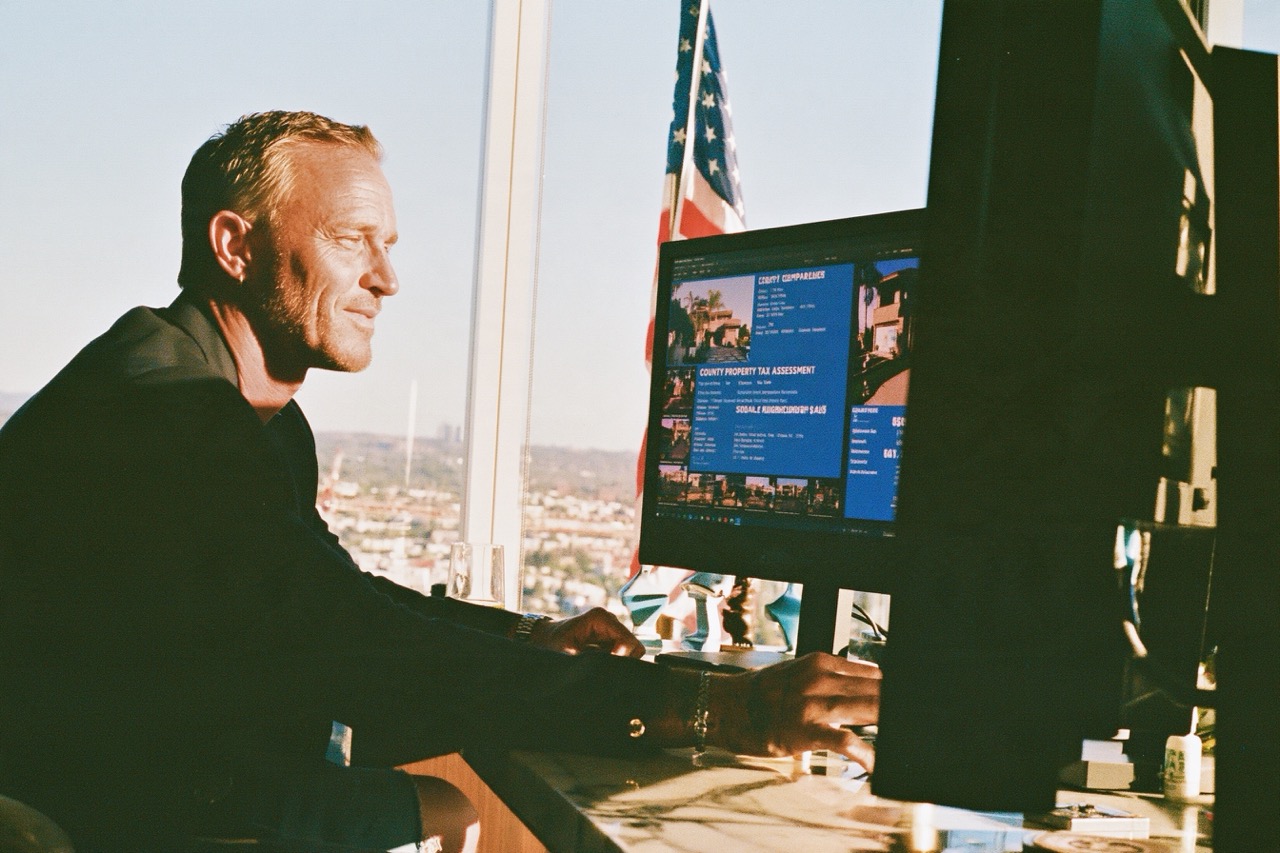
Most homeowners treat their property tax bill like bad weather. It shows up, you complain, you pay it, you forget it. That habit quietly costs people thousands over ten or twenty years.
Here is the thing. Your county appraisal district mails you a number, and almost nobody checks whether that number is right. Roughly half of appealed assessments get adjusted in the homeowner’s favor. If you have owned a home for a decade and never looked at your assessment, you are probably leaving money on the table without realizing it.
This is not about dodging taxes or gaming a system. It is about treating one of your biggest annual expenses like a business line item. You check it, you question it, and you use it. This piece covers how a bill that feels like a burden can become a planning tool.
Why Your Assessment Is the Real Number to Watch
Your tax rate gets all the attention, but the assessed value does most of the damage. A county can hold the rate steady and still raise your bill by bumping your valuation. That is the lever they pull, and it is the one you can actually challenge.
Pull your notice and read the line that says market value or assessed value. Then check the sales data for homes similar to yours in your neighborhood, same square footage, same age, same condition. County records are public. Many appraisal districts post them online. If three comparable homes sold for less than what your place is valued at, you have a case worth filing.
Filing a protest is not dramatic. In most states it means submitting a form, attaching your comps, and either attending a short hearing or sending someone with the paperwork. The window to file is narrow, usually a month or two after notices go out, so calendar it now. Homeownership support resources at USA.gov can point you to your local assessment office if you are not sure where to start.
The filing process is boring, and that is exactly why it works. Most people skip it. The ones who do not tend to see their number move. I would rather spend two hours assembling comps once a year than hand over several hundred dollars I did not owe.
Then There Is the Question Every Homeowner Eventually Asks
Once you have fought the assessment, a different question shows up. Can any of this bill actually work in your favor on your federal return?
Yes, within limits. That is where knowing how much of your property taxes are tax deductible pays off. Deducting a portion of what you paid can offset other income, and for homeowners with larger bills, that deduction is meaningful. The trick is that you have to itemize to claim it, and itemizing only beats the standard deduction once your total deductions clear a certain threshold.
So run the math before you assume. Add up your mortgage interest, your property taxes, charitable giving, and any state income or sales taxes you already paid. If that pile beats the standard deduction, itemizing wins. If it does not, take the standard deduction and stop chasing it.
Here is the trap I see constantly: people fight hard for a bigger deduction when their real problem is a bloated assessment. Shrinking the assessed value lowers what you pay every single year. A deduction only softens the blow once a year, and only if you clear the threshold. Fix the assessment first. Optimize the return second.
A Framework for Ordering the Moves
I call this the Bill, Baseline, Benefit, Backup sequence, and it keeps you from doing expensive things in the wrong order. Run it every year around the same time, ideally right after your assessment notice arrives.
- Bill. Read the actual notice. Know your assessed value, your rate, and the date your protest window closes.
- Baseline. Gather three to five comparable sales. Save the addresses, sale prices, and dates in a folder on your phone.
- Benefit. Run a quick itemize-vs-standard check before filing. Estimate your total deductions rather than guessing.
- Backup. Keep every payment receipt and your year-end tax statement. If anyone questions a number later, you can produce the paper.
That is the whole game. No software subscription required. A manila folder and a Saturday afternoon will do more than most people manage in a lifetime of homeownership.
The Receipt Habit That Pays Off Every April
Deductions live and die on documentation. Keep your closing disclosure, your annual mortgage interest statement, and proof of every payment toward your county bill. If you paid through an escrow account, your servicer sends a summary each January, and that summary is your friend.
What you cannot deduct matters just as much. Special assessments for a new sidewalk, penalties for a late payment, and one-time service fees do not qualify. Only the portion of your bill based on assessed property value counts. Split those line items out so you are not claiming something that does not belong on your return. The Internal Revenue Service publishes the current rules and deduction limits, and its wording is the version to trust when advice from a neighbor conflicts with it. Start a labeled folder in January and drop receipts in as they land. Future you, sitting at a kitchen table in April, will be grateful. Trust me on that one.
How This Ties Into a Bigger Wealth Picture
A house is the largest asset most people will ever own, and most owners manage it with less attention than they give a retirement account. That asymmetry leaks money year after year.
Your assessment shapes what you pay. What you pay shapes your monthly budget and your cash flow. Your cash flow shapes what you can put toward savings or debt payoff. A single appeal that shaves a few hundred dollars off your valuation compounds quietly in the background for as long as you own the place.
Texas property owners, for instance, have a formal protest process that many residents never use simply because they do not know it exists. State resources like Texas.gov point to county appraisal districts where the paperwork lives.
Run this whole exercise once and the pattern sticks. You notice the notice. You question the number. You keep the receipts. Nothing about it feels clever, which is probably why so few people bother.
Your next assessment notice is already on a calendar somewhere, heading your way. Before it lands, put one reminder on your phone for the month it usually arrives, open that folder, and set aside an afternoon. Then tell me whether the number that shows up is one you actually earn.

10 Best Accident Attorneys in Denver, Colorado: Ranked by Experience and Results

How Healthcare Entrepreneurs Can Build Efficient Systems for Sustainable Growth

When a Serious Accusation Affects Your Career: Making Careful Decisions Under Pressure

Building Resilience When Life Throws You Off Course

Why Yoga Studios Need Dedicated Class Management Tools

5 Ways For Startups To Succeed Making Acquisitions

77 Inspirational Quotes That Will Change Your Life
57 Memorable Kobe Bryant Quotes

(Images) 52 Motivational Picture Quotes For An Epic Year Of Success
40 Rare Motivational and Inspirational Picture Quotes

3 Prince EA Videos To Change Humanities Path To Greatness

(Video) What Is Success? An Entrepreneurial Story To Inspire You

(Inspirational Video) What If Today You Knew You Were Going To Take Your Last Breath?

How To Make Enough Money From A Blog To Quit Your Job – Kate McKibbin

How Finding Your Passion And Becoming An Entrepreneur Can Lead To Happiness – Chiquita Searle
-
 Life2 years ago
13 Meaningful Ways to Show Someone They Matter
-
 Life2 years ago
The 5 Stages of a Quarter-Life Crisis & What You Can Do
-

 Did You Know1 year ago
7 Surprising Life Lessons Video Games Taught Me That School Never Did
-
 Success Advice1 year ago
Stephen Covey’s 8 Leadership Habits That Will Change How You Lead Forever
-

 Life1 year ago
How to Stop the War in Your Head and Find Peace
-
 Featured2 years ago
The Psychology of Motivation: How to Keep Moving Forward Every Day
-
 Personal Development1 year ago
The Three-Second Pause That Changes How People Perceive You
-
 Explode Your Social Media1 year ago
Want More Views? Master These 6 YouTube Growth Tactics