Wealth
This Should Be a Core Part of Your Wealth Strategy
Investment growth gets the attention, but the real secret to lasting wealth is protecting what you’ve already built.


Many conversations about wealth focus on growth. Investment portfolios. Real estate. Business ventures. These are all important pieces of financial progress.
But growth is only half of the equation. The other half is protection. Without safeguards, years of financial progress can disappear quickly. A lawsuit, natural disaster, or medical emergency can create sudden financial pressure.
Risk protection helps prevent these events from undoing what someone has worked hard to build. For individuals who take wealth planning seriously, protection is not optional. It is a core part of a long-term strategy.
What Risk Protection Means in Wealth Planning
Risk protection refers to strategies that safeguard assets from unexpected financial loss. These strategies are designed to limit the damage caused by unpredictable events.
Financial planning often emphasizes accumulation. Saving more. Investing more. Increasing income. These steps matter. However, they do not address the reality that financial setbacks happen.
Protection strategies fill that gap. They focus on resilience rather than growth. When combined with smart investing, risk protection creates a more balanced wealth strategy.
The Difference Between Wealth Creation and Wealth Preservation
Wealth creation is the process of building financial assets. People usually associate it with investments, businesses, or career advancement. Wealth preservation focuses on protecting those assets.
This difference is simple but important. Someone may spend decades growing their wealth through consistent effort. Yet one unexpected event can threaten those gains.
Protection tools such as insurance, liability coverage, and legal structures help preserve wealth once it has been built. Growth creates opportunity. Protection ensures that opportunity lasts.
Common Risks That Can Threaten Personal Wealth
Financial risks appear in many forms. Some are small inconveniences. Others can create significant financial strain.
Common examples include property damage, liability claims, medical emergencies, and natural disasters. Loss of income can also create pressure if someone is not prepared. These events rarely arrive with warning. That is why protection strategies must exist before they are needed.
Why Wealth Strategies Fail Without Risk Protection
Some financial plans focus almost entirely on investment performance. Market returns receive attention while potential risks are overlooked. This approach creates a weak foundation.
One Major Loss Can Erase Years of Financial Progress
A single financial shock can undo years of careful planning. A house fire. A legal dispute. Major storm damage. These situations can result in significant expenses. Repair costs. Legal fees. Temporary relocation.
Without protection in place, people may need to sell investments or drain savings to recover. Even everyday financial habits reflect the need for stability.
At times, people find themselves searching for practical answers to small financial questions, such as how to move money from savings to checking when unexpected expenses appear. That simple moment highlights a broader truth.
Liquidity and protection matter as much as long-term growth. Financial resilience depends on preparation.
High Net Worth Individuals Focus on Asset Protection
Wealthy households often prioritize protection strategies. They understand that financial success increases exposure to risk. Higher asset levels can attract legal claims or liability concerns. Valuable property may also require stronger insurance coverage.
As a result, many financially successful individuals use layered protection strategies. Insurance coverage. Legal structures. Estate planning tools. These layers help protect wealth from unexpected disruption.
Key Risk Protection Tools That Support Wealth Strategy
Several tools help individuals reduce financial risk. Each plays a different role within a broader strategy.
Insurance as a Financial Safety Net
Insurance is one of the most effective forms of financial protection. It spreads risk across a large pool of policyholders and provides financial support when unexpected losses occur.
Several types of insurance support wealth protection.
Homeowners’ insurance protects property from damage caused by storms, fires, or accidents. Health insurance reduces the financial impact of medical expenses. Disability insurance replaces income if someone becomes unable to work.
Life insurance protects family members and dependents. Umbrella liability coverage adds an additional layer of protection against lawsuits.
Together, these policies create a financial safety net.
Asset Protection Strategies
Insurance alone cannot address every risk. Legal and structural strategies also play an important role.
Trusts, estate planning tools, and business structures can help protect assets from certain legal risks. Diversification also reduces exposure to market volatility by spreading investments across different asset classes.
These strategies work best when they are part of a coordinated financial plan.
Emergency Funds and Liquidity
Cash reserves remain one of the simplest forms of risk protection. An emergency fund provides immediate liquidity during financial disruptions.
This prevents individuals from selling investments prematurely or taking on expensive debt. Even a modest reserve can create valuable financial flexibility.
The Role of Insurance in Long-Term Wealth Protection
Insurance protects assets that often represent the largest portion of personal wealth.
For many households, this includes their home, personal belongings, and future income. When these assets are protected, financial recovery becomes much easier after unexpected events. Insurance also protects against liability risks.
A lawsuit or accident can produce costs that exceed personal savings. Proper coverage helps prevent these situations from becoming financial disasters. Rather than viewing insurance as an expense, it helps to see it as a financial safeguard.
It preserves stability when circumstances change.
How to Integrate Risk Protection Into a Wealth Strategy
Building a protection strategy does not require complicated financial planning. It begins with awareness.
Assess Your Financial Risks
Start by identifying potential vulnerabilities. Property ownership, professional responsibilities, and family obligations all introduce different types of risk. Understanding these exposures helps guide protection decisions.
Build a Protection Framework
Once risks are identified, the next step is building a structure that addresses them.
This may include reviewing insurance policies, increasing liability coverage, and ensuring that major assets are properly insured. Emergency savings also play a role in this framework.
Review Protection Plans Regularly
Financial circumstances evolve over time. Income levels rise. Homes are renovated. Families grow.
Protection strategies should evolve as well. Reviewing insurance coverage and asset protection measures every few years helps ensure they remain aligned with current financial realities.
Common Mistakes in Risk Protection Planning
Several mistakes appear frequently in personal financial planning.
Some individuals underestimate the value of their property and purchase insufficient insurance coverage. Others overlook liability protection until a problem occurs.
Another common mistake is failing to update policies after major life changes, such as home renovations or increased income. Protection strategies should grow alongside financial success.
The Balance Between Risk and Opportunity
Wealth strategy requires balance. Growth remains important. Investments, entrepreneurship, and innovation all drive financial progress.
However, opportunity always carries risk. Protection strategies do not limit growth. Instead, they create stability. When assets are protected, individuals can pursue opportunities with greater confidence.
Financial security depends on both sides of the equation. Building wealth is important. Protecting it is essential.


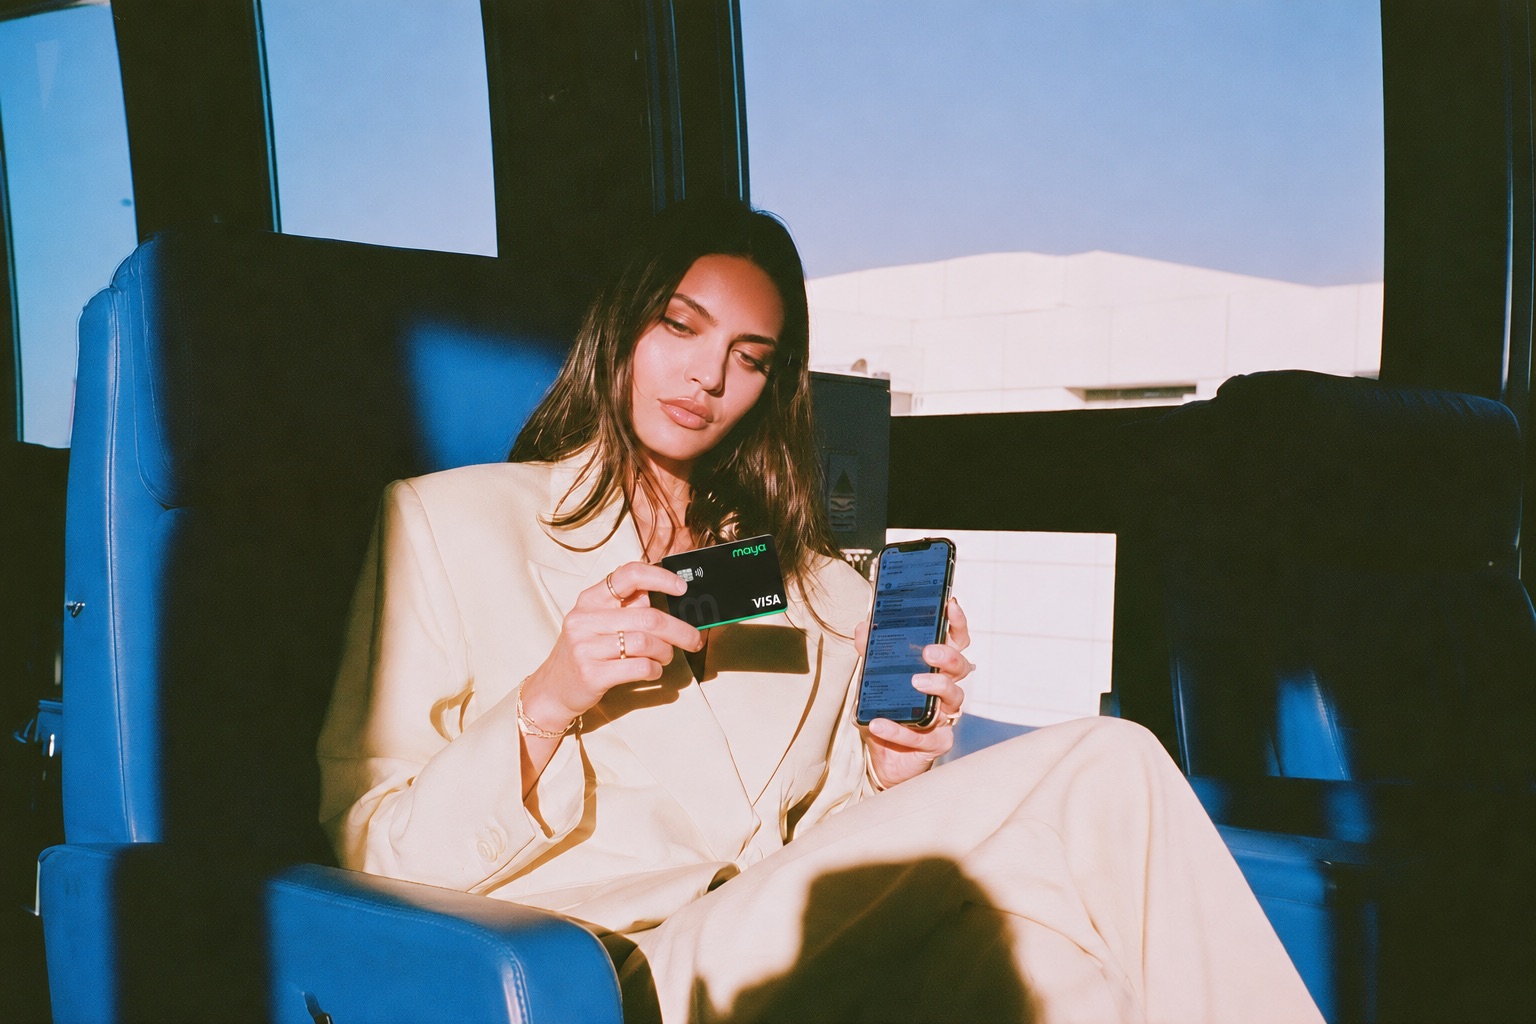
The rapid adoption of digital wallets has changed how people make payments and track their finances. Thanks to their ability to store and transfer funds digitally, e-wallets provide a convenient and secure way to manage everyday transactions. This shift towards digital solutions has also led to innovative ways to simplify financial management, with one such advancement being the ability to link your card to your e-wallet.
Merging the functionality of a physical card with the accessibility of a digital wallet will definitely offer you greater flexibility in managing both your online and offline transactions. It’s no surprise that many others are embracing this combined approach. Nevertheless, some still question whether getting a card that’s linked to a digital wallet is worth any of the perceived hassle. Here are some reasons why this integration can be beneficial for your day-to-day financial activities:
1) Unified Management of Finances
Upon getting a card that can be linked to your e-wallet, you’ll gain the ability to manage all your finances from a single point of access. Instead of switching between different apps or platforms, you’ll be able to see your card transactions alongside your e-wallet activity in real time. This unified approach allows you to keep track of your spending, view your balances, and review all your transaction histories in one place. As a result, you’ll gain a clearer picture of your financial health, which will make budgeting and financial planning much easier.
2) Easier Transfers and Withdrawals
Next, having a card that links to your e-wallet makes managing your funds much simpler. Whenever you need to transfer money between your e-wallet and bank account, you can complete the transaction with just a few taps on your smartphone.
If your card and digital wallet are made by the same digital bank, this process becomes more seamless. Having both the card and e-wallet integrated within the same ecosystem eliminates the need for multiple apps or services.
Take the Maya Card as an example. Since this card is offered by Maya—the #1 digital bank in the Philippines—you can use it alongside your Maya account. Linking this card to your account gives you direct access to your savings without any complicated setup. That means that whenever you need to top up your wallet, you can simply transfer money from your Maya Savings to your Maya Wallet for free.
In addition to easier and faster access to your funds, you can use your Maya Card to withdraw from any BancNet ATM and any ATM that accepts VISA and MasterCard. That means that you can withdraw cash from a wide range of locations and take advantage of greater flexibility and convenience whenever you need it.
3) Increased Payment Flexibility
Even though e-wallets are accepted in many stores, there are situations in which card payments are more convenient. For instance, if you’re shopping at a major grocery store chain, you can use your card to simply tap or dip at the payment terminal. This is quicker than using cash or scanning a QR payment code and may streamline the checkout process significantly for you.
Another example is when you’re purchasing from an international online store. Since cards are more universally accepted, most global retailers prefer card payments over digital wallets. Having a card linked to your e-wallet allows you to shop seamlessly across borders, thus expanding your purchasing power.
4) Global Accessibility
A major advantage of getting a physical card that can link to your e-wallet is that it lets you access your funds even outside the Philippines. With most cards powered by VISA or MasterCard, you can easily pay for purchases at millions of stores, restaurants, and hotels abroad. This way, you won’t have to rely solely on carrying cash or making overseas bank withdrawals. Plus, your purchases are automatically debited from your digital wallet, giving you better control over your spending wherever you are.
5) Better Security
Linking your physical card with your e-wallet lets you benefit from the protections provided by digital banks. These financial institutions employ a range of security features to safeguard your transactions, so you can rest assured that your money and personal information are protected, whether you’re using your digital bank or linked card.
For instance, digital banks use advanced encryption to ensure that your data remains private and secure when making payments or transferring funds. Many also offer two-factor authentication (2FA) to block unauthorized access to your account. Additionally, a reputable digital bank will enable you to quickly lock or suspend your card via the app. In the event of loss or theft, you can immediately disable your card to prevent any unauthorized transactions. With these security measures in place, you’ll have greater control over your finances and enjoy full peace of mind when making purchases both online and in-store.
One practical step many users overlook is setting up spending alerts and category tracking inside the same app. When your card and e-wallet live together, you can turn on notifications for every transaction over a set amount and tag purchases by type (groceries, transport, subscriptions). Over a few weeks this creates a simple, real-time picture of where money actually goes without exporting spreadsheets or waiting for a monthly statement. That visibility makes it easier to catch subscription creep or small leaks early, and it turns the combined card-and-wallet setup into an active budgeting tool rather than just a payment method.
Ultimately, being able to link your card to your digital wallet can add a lot of convenience to your financial routine. With both tools integrated within the same ecosystem, you’ll have an easier time handling payments and managing your finances, and you can expect that same setup to help you adapt to today’s quickly evolving financial trends.
Starting a business involves more than having a good idea or knowing how to attract customers. The decisions you make about money before launching a company can affect how prepared you are to handle the responsibilities that come with running one. From managing expenses to deciding when to take financial risks, many of the skills needed in entrepreneurship are developed through everyday financial experiences.
Your personal financial situation doesn’t have to be perfect before you start a business. However, understanding where your money goes, how much you can afford to invest and what financial commitments you already have can make the process considerably easier. Entrepreneurs who pay attention to these details are often better prepared to deal with unexpected costs, changing income and the demands of growing a company.
The connection between personal finance and entrepreneurship becomes especially clear when you consider how many business decisions depend on the owner’s financial circumstances.
Why Personal Financial Stability Matters When Starting a Business
Financial stability gives entrepreneurs greater flexibility when making important decisions. A person who has manageable living expenses, some savings and a clear understanding of their financial obligations may find it easier to concentrate on developing a business without constantly worrying about covering household bills.
This becomes particularly important during the early stages of entrepreneurship, when revenue can be unpredictable. Even businesses with promising products or services may take months to establish a steady customer base. During that period, owners still need to pay for housing, groceries, transportation and other personal necessities.
Without adequate financial preparation, these expenses can create pressure to withdraw money from the business before it has developed a reliable income stream.
Maintaining financial stability doesn’t necessarily require a large amount of savings. It begins with understanding existing expenses, reducing unnecessary commitments and establishing realistic expectations about how much personal income the business can initially provide.
Someone who knows they need a certain amount each month to cover essential expenses can use that information to develop a more practical business plan. This approach also makes it easier to determine whether starting a company immediately is realistic or whether additional preparation would be beneficial.
How Budgeting Skills Translate Into Better Business Decisions
Managing a household budget and managing business expenses involve many of the same principles. Both require individuals to understand their income, monitor spending and make decisions about how to use limited resources.
When people develop consistent budgeting habits in their personal lives, they become familiar with evaluating expenses rather than making decisions based entirely on what they can afford at a particular moment.
For example, someone who regularly reviews household spending may already understand the importance of distinguishing essential expenses from optional purchases. That same judgment becomes valuable when deciding whether a business needs new equipment, additional software or a larger workspace.
Entrepreneurs also need to recognize that available cash isn’t necessarily money that can be spent freely. Some funds may be needed for upcoming bills, taxes or other commitments.
According to the U.S. Small Business Administration, financial management is an important part of running a business, with budgeting and cash flow planning helping owners understand their financial position and prepare for ongoing expenses.
Developing these skills before launching a company can reduce the learning curve associated with managing business finances. It also encourages entrepreneurs to make spending decisions based on actual needs rather than short-term enthusiasm.
The Importance of Building Savings Before Taking Financial Risks
Entrepreneurship involves uncertainty, and savings can provide valuable financial protection when circumstances don’t develop as expected.
A business may experience slower sales during certain months, encounter unexpected repair costs or require additional investment before becoming profitable. When the owner has no personal financial cushion, these situations can quickly affect household finances.
Establishing an emergency fund can help separate temporary business difficulties from personal financial emergencies. It may also reduce the likelihood of relying on expensive credit to cover routine living expenses.
The appropriate amount to save depends on several factors, including household costs, existing financial obligations and the stability of other income sources.
Entrepreneurs leaving traditional employment may need to plan more carefully because they are giving up a predictable paycheck. Someone who continues working while developing a business may have more flexibility, although they still need to consider the financial demands of both responsibilities.
Savings also influence how business owners approach opportunities. Having funds available can make it easier to invest in necessary equipment, professional services or improvements without placing immediate pressure on household finances.
However, maintaining a personal emergency fund separately from money reserved for business operations is important. Each serves a different purpose, and combining them can make it difficult to understand how much financial protection is actually available.
Understanding Credit and Making Responsible Borrowing Decisions
Credit management is another personal financial skill that can influence entrepreneurship. Business owners may eventually need financing for equipment, inventory, workspace improvements or expansion, making it useful to understand how borrowing works before taking on additional obligations.
Personal credit history can also matter when applying for certain forms of small business financing, particularly when a company has a limited operating history.
Paying bills on time, monitoring outstanding balances and avoiding unnecessary debt can help individuals maintain a stronger personal financial position.
Still, responsible credit management involves more than maintaining a favorable credit score. Entrepreneurs need to consider whether borrowing supports a meaningful financial objective and whether future income will comfortably cover repayment obligations.
For instance, purchasing equipment that improves productivity may provide a measurable business benefit. Borrowing to fund unnecessary upgrades, on the other hand, can increase monthly expenses without improving revenue.
Credit cards can also be useful for organizing certain purchases, provided spending remains controlled. Some consumers compare card features to understand how they can earn reward points based on their regular purchasing patterns. While rewards may offer additional value, interest charges and annual fees can quickly outweigh those benefits when balances aren’t managed carefully.
Business expenses should also be kept separate from personal purchases whenever possible. Maintaining that distinction simplifies recordkeeping, supports more accurate financial reporting and helps owners understand how their companies are performing.
How Personal Spending Habits Affect Business Growth
An entrepreneur’s relationship with spending can influence the decisions they make after their company begins generating revenue.
Some people are naturally cautious about spending, while others are more comfortable making purchases when money becomes available. Neither approach guarantees success, but understanding these tendencies can help business owners recognize potential problems.
For example, an owner who is accustomed to spending most of their personal income may be tempted to treat increasing business revenue as money available for immediate personal use.
However, business revenue isn’t the same as profit. Operating costs, taxes, debt payments and future investment needs must be considered before determining how much money can reasonably be withdrawn.
Owners who understand this distinction are better positioned to protect working capital and prepare for periods when expenses exceed incoming payments.
Personal spending habits can also affect decisions involving business growth. Expanding too quickly may create financial pressure, especially when new expenses are based on expected sales rather than established demand.
At the same time, avoiding every expense can prevent a business from improving its services or reaching new customers.
The objective is to develop balanced spending habits that encourage thoughtful investment while protecting the company’s financial resources.
Final Thoughts
Your approach to personal finances can influence nearly every stage of your entrepreneurial journey, from deciding when to start a business to managing its growth over several years.
Budgeting, saving, responsible credit use and long-term planning are not exclusively personal financial concerns. They also help develop the judgment needed to handle business expenses, assess opportunities and respond to financial uncertainty.
Although strong personal financial habits cannot guarantee entrepreneurial success, they can provide a more dependable foundation for making important decisions. By developing these habits early and adapting them as circumstances change, aspiring business owners can approach entrepreneurship with greater financial awareness and a clearer understanding of the responsibilities ahead.
Most people think financial progress comes from big moves: a raise, a new side business, a lucky investment. Those matter, but they are rare. What actually decides whether money builds up or slips away is a set of small, repeated habits that most people never think about.
The difference between someone who always seems to have a cushion and someone who is always a little short often comes down to how they handle the ordinary money that passes through their hands every week.
The good news is that these habits are learnable. None of them require a finance degree, a big income or hours of spreadsheet work. They require attention, a few simple systems and the discipline to stop leaving value on the table.
Treat Every Dollar Like It Has a Job
The first habit is mental. People who build wealth tend to see money as a tool with a purpose, not a pool to dip into. A paycheck is not just income. Part of it pays the bills, part of it protects the future and part of it funds the life you actually want.
When every dollar has a job, it becomes much harder to waste. A small purchase is no longer “just ten dollars.” It is ten dollars that was supposed to go toward an emergency fund, a debt payment or a goal you care about. This shift does not mean never spending. It means spending on purpose.
Find the Money You Already Have
One of the most overlooked sources of savings is money you already own but are not using. Almost every household has some: a forgotten subscription still charging a card, a refund that was never claimed, store credit from a return, or a gift card sitting in a drawer.
Gift cards are a perfect example of how small amounts add up. They arrive as birthday presents, holiday gifts and workplace rewards, and many of them are never fully spent. A twenty-five dollar card here and a fifty dollar card there may not feel like much, but together they can easily cover a month of groceries or a utility bill.
Make it a habit to gather every card and credit you own once or twice a year. Check the balances, note any expiration dates and decide what to do with each one. Use the ones that match your regular spending. Regift the ones that suit someone else. For the ones you will never use, peer-to-peer marketplaces now make it easy to turn unused gift cards into cash and move that money where it can do real work.
Plan Big Purchases Before You Make Them
Impulse spending gets the blame for a lot of financial trouble, but unplanned big purchases often do more damage. A broken appliance, a home repair or a weekend project that keeps growing can wipe out months of careful saving.
The fix is simple: plan large purchases in advance whenever you can. If you know the deck needs new boards next spring or the kitchen faucet is on its last legs, start setting money aside now and research the best time and place to buy.
Planning also opens the door to savings that impulse buyers miss. Home improvement stores run regular sales and promotions, and some have loyal followings for good reason. Menards, for example, is well known in the Midwest for its periodic rebate events. Stacking a store promotion with a discounted Menards gift card bought below face value can cut the real cost of a project noticeably without changing what you buy. The same approach works at almost any retailer you already shop at regularly.
Automate the Boring Parts
Willpower is unreliable. The most consistent savers do not rely on remembering to save. They set it up so it happens automatically.
Schedule a transfer to savings on the same day your paycheck arrives. Set up automatic payments for fixed bills so you never pay a late fee. If your employer offers a retirement match, make sure you contribute at least enough to collect it, because that match is part of your pay.
Automation removes the daily decision, and fewer decisions means fewer chances to talk yourself out of a good habit.
Review, Do Not Obsess
Tracking spending matters, but there is a difference between staying aware and becoming anxious. You do not need to log every coffee. A short monthly review is enough for most people.
Once a month, look at where your money went. Notice the categories that surprise you. Cancel what you do not use. Ask whether your spending reflects what you actually value. Fifteen focused minutes a month will tell you more than a stressful daily routine you abandon after two weeks.
Protect Yourself From Costly Mistakes
Saving money is only half the job. Keeping it is the other half. Scams, fees and preventable mistakes quietly drain more money than most people realize.
Be cautious with anyone who pressures you to act fast, especially if they ask for payment in gift cards, wire transfers or other hard-to-trace methods. Read the terms before signing up for anything with a recurring charge. Keep an emergency fund so a surprise expense does not land on a high-interest credit card. Each of these habits protects the progress you have already made.
Small Habits, Big Results
Financial success rarely arrives in one dramatic moment. It is built gradually, through ordinary choices repeated over months and years. Giving every dollar a job, using the money you already have, planning big purchases, automating your savings, reviewing your spending and guarding against mistakes may not sound exciting, but together they change everything.
Start with one habit this week. Gather your forgotten gift cards, set up one automatic transfer or plan your next big purchase instead of reacting to it. Small wins build momentum, and momentum is what turns good intentions into lasting financial freedom.
Your Next Level of Success Starts With How You Handle Money
The path to a greater level of success is not often tied to working longer hours or making one successful decision. Most times, moving up to the next level will mean making significant changes in how you use and manage capital. Wealth creation does not lie in earnings but in discipline.
For most high achievers, the problem is not lack of earnings when they find themselves at a dead end. Instead, the problem is capital management and allocation. Unless there is proper management and allocation of capital, it is unlikely for you to experience any form of growth. It simply means that you need to move from personal finance to capital allocation strategies.
The Mechanics of Capital Efficiency
A lot of people look at money as a static means of providing security and for spending. But the key to sustainable leverage lies in capital efficiency, and capital efficiency is the relationship between utilization and friction. The money that is not actively managed in traditional deposits is eroded through inflation and missed opportunity costs.
In order to establish financial leverage, you have to organize your capital into different layers, and not treat it as an overall sum.
- Operational Capital: cash set aside for working expenditures and short-term commitments.
- Reserves: liquid funds allocated for any unforeseen circumstances to avoid the sale of productive resources.
- Growth Capital: discretionary liquidity allocated to purchase assets and develop operations in public and private markets.
By keeping them separate, you ensure that the operational requirements won’t take away your growth opportunities.
Modern Friction and Strategic Access
Moving beyond basic savings requires deploying capital through channels built for growth rather than mere storage. Establishing an account with a brokerage account online platform allows individuals to direct cash flows into productive financial instruments without intermediate administrative friction.
Access to diverse investment vehicles serves as the foundation for modern asset growth. The primary advantage of establishing targeted deployment structures is speed and access. When a market opportunity arises, the delay between analysis and execution often determines the magnitude of the return.
Asymmetric Risk Management
Real financial mastery is achieved not through excessive risks but through asymmetric risk management. Creation of top-tier wealth requires minimizing downside risks and leaving opportunities for upside gains.
With rising income, typical human psychology usually results in lifestyle inflation, which means a gradual increase in fixed expenses that consume increasing income. This process makes capital inefficient. Instead of expanding fixed costs along with growing revenues, the next level of wealth management implies instant conversion of extra money into non-correlated investments.
In case of downturns, people who rely only on active income are compelled to defend themselves by reducing expenses, selling assets at unfavorable prices, and halting growth projects. On the contrary, people who manage capital structurally exploit market disruptions to purchase troubled assets and invest in their businesses or increase their market share.
The Psychology of Capital Retention
Making money is totally different from saving it and growing it. Making money may require aggressiveness, confidence, and expert knowledge. Saving, however, may require humility, patience, and systematic limitations.
Many people who earn money cannot grow it simply because they have been using offensive methods to solve a defensive problem. They always look for better returns or even venture into risky businesses to escape from poor cash management skills. The real growth will occur once you are able to create an automated way of saving.
Building Strategic Liquidity
Liquidity is commonly misconceived as having money. Liquidity strategy refers to the readiness to access money swiftly while suffering minimal losses or avoiding the payment of unnecessary taxes and penalties. Having cash is part of the process, but also the ease with which your other assets are able to convert to cash becomes important.
Different assets lie at different ends of the spectrum. For example, a high-yield savings account, money market fund, or short-term Treasury bills purchased through TreasuryDirect can be cashed out in days with minimal risk of losing principal. The proceeds from the sale of your holdings in your brokerage account with your index funds can be accessible in a couple of days, although a downturn in the market will mean a loss and capital gain tax. Your 401(k) and traditional IRA are less liquid than the aforementioned, since withdrawal before age 59½ will lead to a 10% penalty on top of ordinary income tax.
In the absence of a conscious liquidity cushion, there are basically two extremes that individuals will end up facing. First, they may have virtually everything invested in their retirement plans or in their property; hence, any unexpected cost ends up requiring them to incur debt or liquidate their investments at inopportune moments. Alternatively, they may hang on to too much money for too long, causing them to underperform against inflation. With a proper strategy in place, one will have allocated enough in their available accounts for short-term requirements, and the remaining part is invested based on its time frame.
The Shift from Income to Equity
Salary is how most individuals generate their initial wealth and is the key driver for many years. The ratio, however, shifts with the passing of time. While salary is based on the time spent and the individual’s capacity to continue generating it, equity or ownership in assets is something that continues to grow even when the individual is away from their desk.
If you want to make financial progress, then you must dedicate a certain percentage of your excess cash flow to asset investments that will appreciate even when you are not actively involved in their management. This could involve investing in equity mutual funds, debt instruments, real estate, or business ventures. Each of these comes with its own risks and requirements.
An effective means of starting would be to create the habit. Dedicate a certain percentage of each paycheck, and of every raise and bonus that you receive, to being invested in your investments before it ever hits your checking account. The principle is universal no matter how you decide to proceed to make your money work for you.
Capital Allocation as a Core Competency
Having the attitude that you are running your own financial business will do some good. Each dollar that enters must have a definite purpose to play, be it supporting operations, managing risks, or growing for the future. An easy method is to classify all cash into three piles: the one for expenditures, the second for emergency and budget items, and the third for distant objectives.
Its usefulness lies in the fact that all the decisions are taken in advance, while you are calm, and not when the market falls or an attractive product catches your eye. Some written guidelines will come in handy, like which account gets your paycheck, what causes a rebalance of your portfolio, and how long you need to wait before a big purchase. You can periodically check your desired ratio once or twice per year.
Once there is a system rather than emotion, market volatility ceases to be a problem and becomes a normal state of affairs. Prices will move up and down, and the whole approach based on time frames takes into account such a possibility, but it does not eliminate the risk; it simply makes it bearable.
Ultimately, long-term success will be determined not by market timing or market trends, but by three key factors: good structure, managed liquidity, and a defined purpose for every dollar spent.

SEO Agency Best Practices: How to Scale Campaigns Without Dropping the ROI Ball

Why Seat-Based Pricing Is Breaking and What Founders Should Charge For Instead

How to Handle Industrial Fluids Safely

How Solo Creators and Side-Hustlers Use 3D AI to Turn Ideas into Sellable Digital Assets

Why More Founders Are Choosing AI-Native Schools for Their Kids
5 Ways For Startups To Succeed Making Acquisitions

77 Inspirational Quotes That Will Change Your Life
57 Memorable Kobe Bryant Quotes

Motivational Picture Quotes: 52 Images to Inspire a Successful Year
40 Rare Motivational and Inspirational Picture Quotes
3 Prince EA Videos To Change Humanities Path To Greatness
(Video) What Is Success? An Entrepreneurial Story To Inspire You
(Inspirational Video) What If Today You Knew You Were Going To Take Your Last Breath?
How To Make Enough Money From A Blog To Quit Your Job – Kate McKibbin
How Finding Your Passion And Becoming An Entrepreneur Can Lead To Happiness – Chiquita Searle
-

 Did You Know1 year ago
7 Surprising Life Lessons Video Games Taught Me That School Never Did
-
 Life2 years ago
The 5 Stages of a Quarter-Life Crisis & What You Can Do
-
 Success Advice1 year ago
Stephen Covey’s 8 Leadership Habits That Will Change How You Lead Forever
-

 Featured2 years ago
The Psychology of Motivation: How to Keep Moving Forward Every Day
-

 Life1 year ago
How to Stop the War in Your Head and Find Peace
-
 Personal Development1 year ago
The Three-Second Pause That Changes How People Perceive You
-
 Explode Your Social Media1 year ago
Want More Views? Master These 6 YouTube Growth Tactics
-
 Change Your Mindset1 year ago
You Become What You Absorb: How Input Shapes Your Life