Wealth
The Psychology of Wealth: A 3-Step Framework to Break Your Financial Ceiling


Hustle culture has sold us a massive lie: that the only way to build wealth is to grind harder, work longer, and sacrifice your sanity. But if sheer effort were the only variable, the hardest-working people on the planet would all be billionaires.
The reality is that profound financial transformations—like going from a few hundred dollars and foreclosed homes to running a $25 million Inc. 500 company… rarely start with a new business tactic. They start with a fundamental shift in your money mindset.
Most financial struggles boil down to a misunderstanding of what money actually is and how our brains process risk and reward. If you want to stop feeling like you are constantly chasing cash, you need to rewire the deeply ingrained beliefs that are silently sabotaging your success. Here is a practical, psychology-backed blueprint for building real wealth.
1. Stop Hoarding and Give Money a Purpose
Before we can change how much money we have, we have to change how we view it. At its core, money is just a tool. It is a medium of exchange designed to move. It’s not a coincidence that the financial system uses the word currency—like a current, it is meant to flow and facilitate action.
Money tends to follow a clear purpose. If your only goal is to “not be broke,” your brain is focused on survival, not growth. But when you have a specific, expansive vision—whether that’s funding a charitable cause, scaling a business, or securing your family’s future—your brain starts actively scanning your environment for the opportunities to make that happen.
Case Study: The $60,000 Shift
Consider this real-world example of how a shift in focus creates tangible results. An entrepreneur (who later built a $25M company) realized he was capping his own wealth by believing he could only earn money through his primary business.
To break this mental block, he set a hyper-specific goal in March: “I will generate an extra $60,000 by the end of the year from a source entirely outside my business.” He didn’t know the exact mechanism yet; he just set the target and kept his eyes open.
Months later, a casual lunch led to an unconventional opportunity to buy into a startup for $23,000. The startup was chaotic, and by October, he realized it wasn’t a good long-term fit. The founders offered to buy back his shares. After a brief negotiation, the final contract was signed on December 28th.
The payout? His original $23,000 investment back, plus exactly $60,000 in profit.
When you give your brain a specific target, it stops filtering out opportunities. Here is how to remove the psychological friction that keeps you from setting and hitting those targets.
2. Dismantle Your Subconscious Financial Blueprint
If building wealth is just about math and strategy, why are so many smart people broke? Because we operate on subconscious scripts.
Your brain is an efficiency machine. It operates on a loop: your beliefs dictate your thoughts, your thoughts drive your emotions, your emotions dictate your actions, and your actions produce your results. Psychologists call this confirmation bias—we subconsciously act in ways that prove our existing beliefs right.
To find your hidden financial friction, complete this sentence with the very first thing that pops into your head:
“When I was growing up, money was ____________.”
Did you say hard to come by? The reason my parents fought? Only for people who got lucky?
If you subconsciously believe money is hard to make, you will naturally feel stressed about it. When you feel anxious, your cognitive bandwidth shrinks. You overlook investment opportunities, you avoid asking for raises, and you play it dangerously safe in business. The result? Financial stagnation—which “proves” to your brain that money is, indeed, hard to make.
| The Scarcity Loop | The Growth Loop |
| Belief: “Money is scarce and hard to get.” | Belief: “Capital is available for good ideas.” |
| Thought: “I can’t afford to take risks.” | Thought: “How can I increase my value today?” |
| Emotion: Anxiety, fear, overwhelm. | Emotion: Curiosity, focus, determination. |
| Action: Hoarding, playing small, avoiding negotiation. | Action: Networking, creating, asking for the sale. |
| Result: Missed opportunities, stagnant income. | Result: Scalable income, business growth. |
To break the scarcity loop, you have to consciously interrupt it. You must actively challenge your childhood assumptions about money and look for daily evidence to prove to your brain that wealth is accessible.
3. Disarm the “Not Enough” Trap
This is the ultimate sticking point that keeps millions of people trapped in financial anxiety.
Most people try to accumulate wealth to protect themselves against the fear of not having enough in the future. They want to build a fortress against financial ruin.
Here is the problem: when you are driven by the fear of running out, you operate in a state of chronic stress. In a fight-or-flight state, your brain prioritizes short-term survival over long-term strategy. You make reactive decisions rather than proactive ones.
To fix this, you have to look at the objective data of your life.
- Have you always had enough to survive? Things may have been painfully tight, and you might have faced real hardships, but you figured it out. You made it to today.
- Do you have enough right now? In this exact second, reading this screen, you are okay.
- Will you figure it out tomorrow? Yes, because you always have.
When you desire wealth out of the fear of lacking it, you make desperate business decisions. Desperation repels clients, partners, and investors.
To make high-level financial decisions, you need a calm, rational baseline. Ground yourself in this reality:
“I have navigated every financial challenge in my past. I am okay right now. I have the skills to handle whatever comes next.”
When you truly internalize that you are capable of handling the downside, the desperation vanishes. You stop clinging to pennies out of fear and start making strategic, high-ROI moves out of confidence.
The Bottom Line
You do not need to work 100-hour weeks to build wealth. You simply need to align your psychology with your goals.
Set a clear, exciting purpose for your money so you can recognize opportunities when they appear. Ruthlessly identify and rewrite the limiting beliefs you adopted as a child. And most importantly, let go of the illusion that you are one bad month away from ruin. When you realize that you are highly capable and resilient, you remove the psychological friction—and building real, sustainable wealth becomes a matter of strategy, not survival.
Joel Brown speech about How to Create More Abundance In Your Life
Follow me Joel Brown on Instagram for more insights








There are roughly two months left in the 2026 tax year, and for a one-person business that window is worth more than most founders realize. Once December 31 passes, many of the decisions that shape your tax bill are locked in. Before it passes, you still have room to time purchases, fund retirement accounts, tidy up contractor paperwork, and make sure you aren’t heading into a penalty for underpaying through the year.
This year also carries more change than usual. The tax law signed on July 4, 2025, which the IRS now refers to as the Working Families Tax Cuts and which many people still call the One Big Beautiful Bill, rewrote several rules that matter to solo founders, freelancers and small online businesses. Some of those changes apply for the first time to payments you make in 2026. The year-end tax moves below are written for US-based solo operators. They’re a framework for a better conversation with your accountant, not a substitute for one, because the right move always depends on your entity type, your income, and your state.
Close Your Books Before You Make Any Decisions
Every good year-end decision starts with knowing where you actually stand. Before you buy equipment or move money into a retirement account, get your books current through October. Reconcile every business bank and card account, categorize the transactions that have been sitting in a suspense folder, and chase down receipts for anything significant. Then build a simple projection for November and December based on contracts you’ve signed, invoices you expect to collect, and costs you know are coming.
That projection gives you an estimated profit for the year, and almost everything else in this article depends on that number. A founder heading for a strong year has very different options from one who had a slow first half. Guessing at this figure is how people end up buying a laptop they didn’t need to save tax they didn’t owe, or skipping a contribution they could easily have made.
If you want to understand the business provisions of the new law in more depth, the IRS published a recorded webinar on its official YouTube channel walking through the business tax provisions.
Check Your Estimated Tax Position Now, Not in April
Most solo founders don’t have an employer withholding tax from their pay, which means the responsibility for paying through the year sits with them. The IRS explains on its estimated taxes page that most taxpayers avoid the underpayment penalty if they owe less than $1,000 after withholding and credits, or if they paid at least 90% of the current year’s tax or 100% of the prior year’s tax, whichever is smaller. The IRS also notes special rules for certain higher-income taxpayers, so check which threshold applies to you.
Run the numbers against your projection now. If revenue jumped this year, your earlier quarterly payments may have been based on a much smaller tax bill, and the final payment of the year is your chance to close the gap. If you’re short, you’ll know while there’s still time to set the cash aside. If you’re ahead, you can stop worrying and keep that money working in the business. Either way, finding out in late October is far better than finding out when you file.
Time Equipment Purchases Around When They Go Into Service
One of the most significant changes in the new law is the return of full expensing for many business assets. The IRS states that the law provides a permanent 100% additional first-year depreciation deduction, often called bonus depreciation, for qualified property acquired after January 19, 2025. It also raised the Section 179 expensing limit to $2,500,000 for property placed in service in tax years beginning after December 31, 2024, with that amount indexed for inflation in later years.
For a solo business, the practical point is simpler than the code sections suggest. If you were already planning to buy a computer, camera gear, studio equipment or other qualifying property in the next few months, buying it and putting it into use before December 31 can bring the deduction into 2026 instead of spreading it over several years. The IRS’s guidance for gig economy workers notes that for property such as vehicles or certain computers, business use must be more than 50% of total use to deduct up to the full cost of the business-use percentage in the first year.
The key words are “already planning.” Spending a dollar to save a fraction of that dollar in tax is still spending money. Buy what the business genuinely needs, keep the receipts and the date it was first put into service, and let your accountant decide whether expensing it all now or depreciating it over time makes more sense for your situation.
Use the Retirement Plan Window While It’s Open
For many profitable solo founders, a retirement plan is the single biggest lever available, and it also happens to build long-term wealth instead of just reducing a bill. The IRS announced that for 2026 the 401(k) elective deferral limit rises to $24,500, the catch-up contribution for people 50 and over rises to $8,000, and a higher catch-up of $11,250 applies to those aged 60 to 63. The IRA limit rises to $7,500, and the overall limit for defined contribution plans is $72,000.
Those numbers matter because a one-person business can often contribute in two capacities. The IRS explains that in a one-participant 401(k), the owner can make elective deferrals as the employee and also make employer nonelective contributions, subject to the overall limit, with special calculation rules for self-employed people. A SEP is the simpler alternative. According to the IRS, a business of any size, including a self-employed person, can establish a SEP plan as late as the due date, including extensions, of the business tax return for the year, with contributions of up to 25% of each employee’s pay.
Because the deadlines and paperwork differ between plan types, don’t leave this until the last week of December. Talk to your plan provider or accountant in November about which plan fits, what has to be in place by year-end, and what can wait until you file. If you’ve been treating retirement savings as something you’ll get to once the business is bigger, this is the year to reconsider. The habits you build around money now have a lot to do with how your business turns out, and how you approach personal finances can influence your entrepreneurial journey far more than most founders expect.
Get Ahead of Contractor Paperwork
If you pay freelancers, designers, editors or developers, the new law changes your January workload. The IRS confirms that the Form 1099-NEC threshold has increased to $2,000 for payments made in 2026, up from the $600 threshold that applied for decades. Starting in 2027, that amount can be adjusted for inflation. That means some smaller contractor relationships that used to require a form no longer will.
Don’t let the higher threshold make you sloppy, though. You still need to know exactly how much you paid each contractor during the year to decide who crosses the line, and the IRS notes that a 1099-NEC is still required for anyone from whom you withheld federal income tax under backup withholding rules, regardless of the amount. The smart year-end move is to pull a payee report now, collect any missing W-9 forms while people are still responsive, and fix incomplete names or tax ID numbers before the January filing rush. If you’ve already built a system for how you handle contracts and payments without a team, make W-9 collection part of contractor onboarding so this becomes a non-event next year.
Know What Payment Platforms Will Report About You
Many online businesses get paid through payment apps and marketplaces, and the rules for what those platforms report have also changed. The IRS explains that the law retroactively reverted the Form 1099-K reporting threshold for third-party settlement organizations to its earlier level, so these platforms are required to issue a 1099-K when payments in the calendar year exceed $20,000 and the number of transactions exceeds 200.
The important part is what the IRS says next. You must report all of your income when you file, whether or not you receive a 1099-K or any other information return. A higher reporting threshold changes the paperwork you receive, not what you owe. Make sure your own records capture every stream of revenue, including smaller platforms that may never send you a form, so your return reflects the business as it really is.
Don’t Leave the Qualified Business Income Deduction to Chance
Many owners of sole proprietorships, partnerships and S corporations have been able to use the qualified business income deduction for tax years beginning after 2017, and the new law made it permanent. The IRS describes it as allowing eligible taxpayers to deduct up to 20% of their qualified business income, subject to limitations, and notes that it’s available whether you itemize or take the standard deduction. For tax years beginning after 2025, the IRS also lists a new minimum deduction for active qualified business income. Income earned through a C corporation, or as an employee, isn’t eligible.
The deduction interacts with your taxable income, your type of business, and for higher earners, factors like wages paid and property held. That’s exactly why it belongs in your year-end conversation rather than as a surprise at filing time. Your projection, your retirement contributions and your equipment purchases all change your taxable income, and that in turn can change how much of this deduction you keep.
Set Up 2027 Before the Year Even Starts
The best year-end tax move is making next year’s year-end boring. Open a separate account for tax money if you don’t have one, and move a fixed percentage of every payment you receive into it. Put the quarterly estimated payment dates in your calendar now. Decide which bookkeeping tool you’ll use and commit to reconciling monthly rather than in a panic every December. Book a planning session with your accountant for mid-2027, when there’s still time to act on what you learn.
None of this is glamorous, but it’s the kind of discipline that separates a business that grows on purpose from one that keeps being surprised by its own numbers. Spend a few focused hours on these year-end tax moves over the next few weeks, bring your projection and your questions to a qualified professional, and you’ll go into 2027 with more cash, fewer surprises, and a much clearer picture of what your business really earns.
Wealth
The Hidden Cost of Staying Cash-Only: Why Accepting Cards Is a Growth Strategy for Solo Entrepreneurs

Twenty-two dollars. That’s the average transaction I walked away from on a single Saturday at a farmers market because my card reader was dead and I had no backup plan. I found out later the customer had come straight from the ATM and still wanted to buy. They just didn’t have bills, and I couldn’t take a card.
Most solo sellers treat card acceptance as a nice-to-have they’ll get to eventually. That framing is backwards. Every cash-only booth quietly filters out buyers, and the filter gets tighter every year as fewer people carry paper money. mobile credit card processing closes that gap, and I’m not being dramatic when I say it saved more of my own bookings than any ad I ever ran.
Here’s what I want to cover: the real cost of the cash-only habit, a simple framework for deciding when to add cards, and the exact setup steps that took me one afternoon to finish. If you sell at markets, pop-ups, or from your car, this is for you.
What does cash-only actually cost you?
The answer isn’t just the sales you lose at the moment. It’s the repeat business that never starts, the awkward “do you have cash?” fadeout, and the friends of that customer who hear “they don’t take cards” and skip your booth next weekend. I keep a notebook from my first season and the pattern is ugly. On days I only took cash, my average sale was noticeably smaller than on days I had a reader. It wasn’t the product that changed. It was the friction. When a customer has to hunt for an ATM, they either buy less or buy nothing, and I never got a vote.
There’s a second cost most sellers ignore: point-of-sale disputes. According to the Federal Trade Commission, consumers have dispute rights on card purchases, and that’s actually good for your reputation. Card transactions leave a trail. Cash transactions leave you with a “he said, she said” and a bad review if a customer forgets what they paid.
Bottom line: cash-only isn’t a money-saving strategy. It’s a quiet discount you give to your competitors who already swipe.
The Three-Strike Rule for adding card payments
I built a simple test after a brutally slow June, and I still use it. I call it the Three-Strike Rule, and it requires nothing more than a tally sheet.
Strike one: you turn away a customer who wants to pay by card. Tally it.
Strike two: a customer at a booth or event asks if you accept cards before asking about prices. Tally it.
Strike three: you finish a market day and the cash in your pocket doesn’t match the number of people who browsed your table. Tally it.
When any of those tallies hits five in a month, it’s time. Not next season. Now. Five strike-marks means you’ve already done enough research to know card acceptance is a real gap, and the reader you buy pays for itself faster than most sellers expect. That’s the number that finally got me out of my own way.
I’d pick a mobile reader on a phone or tablet over a countertop terminal if I were starting over. You carry it, it fits in a tote, and it works at a table, a tailgate, or a client’s front step. The big fixed terminals are great for storefronts. They’re dead weight for anyone who moves.
The one-afternoon setup
Getting set up is less mysterious than most sellers assume. Here’s how I’d walk you through it if you were standing at my table.
Write down how you actually get paid today. Cash, checks, Venmo, invoices, and any online orders. Know the shape of your revenue before you pick a tool.
Pick a reader that fits your workspace. Confirm it pairs with the phone or tablet you already own, and check that you can run it from a battery if there’s no outlet at your spot.
Test a real transaction before your first market. Swipe your own card for a low amount, watch the receipt land, and refund it. Now you know the whole loop works.
Set up a text or email receipt option. Buyers who get a receipt in their inbox are easier to bring back, and you get a contact for the next event.
Give yourself a printed fallback. A small sign that says “cards welcome” pulls people in faster than you’d think.
The step most people skip is number three. I’ve watched sellers show up with a reader fresh out of the box and no idea if it holds a charge. Don’t be that seller. Do the boring test on a Tuesday.
Where card acceptance pays off most for small operators
Every solo business I’ve watched grow has a story about one channel that unexpectedly opened up. For me, card acceptance did two things at once: it made the in-person sale easier, and it gave me a record I could show when applying for bigger opportunities. That second part matters more than people realize. Small businesses are a huge share of the American economy. The U.S. Census Bureau tracks businesses with no paid employees, and that group is enormous. When you want to grow beyond a single booth, buyers and partners want to see proof you move money. Card records are that proof.
The compounding effect: a single change in how you take payments shows up in four places at once. Larger average tickets, less abandoned interest, a clean paper trail, and a story you can tell on a website or application. That’s a lot of return for one piece of equipment.
Make the switch now, before the next market
The cash-only habit feels safe because it’s familiar. It isn’t safe. It’s expensive, and the expense hides in plain sight, one walkaway customer at a time. If you’ve been waiting for a sign to add card payments to your booth, this is it. Run the Three-Strike tally this week. Set up the reader before your next event. Test it on a Tuesday, so Saturday runs smoothly. Here’s the question I’d ask yourself: how many $22 opportunities are you willing to hand to the seller at the next table? If the answer is fewer than the ones you’ve already lost, you know what to do next.

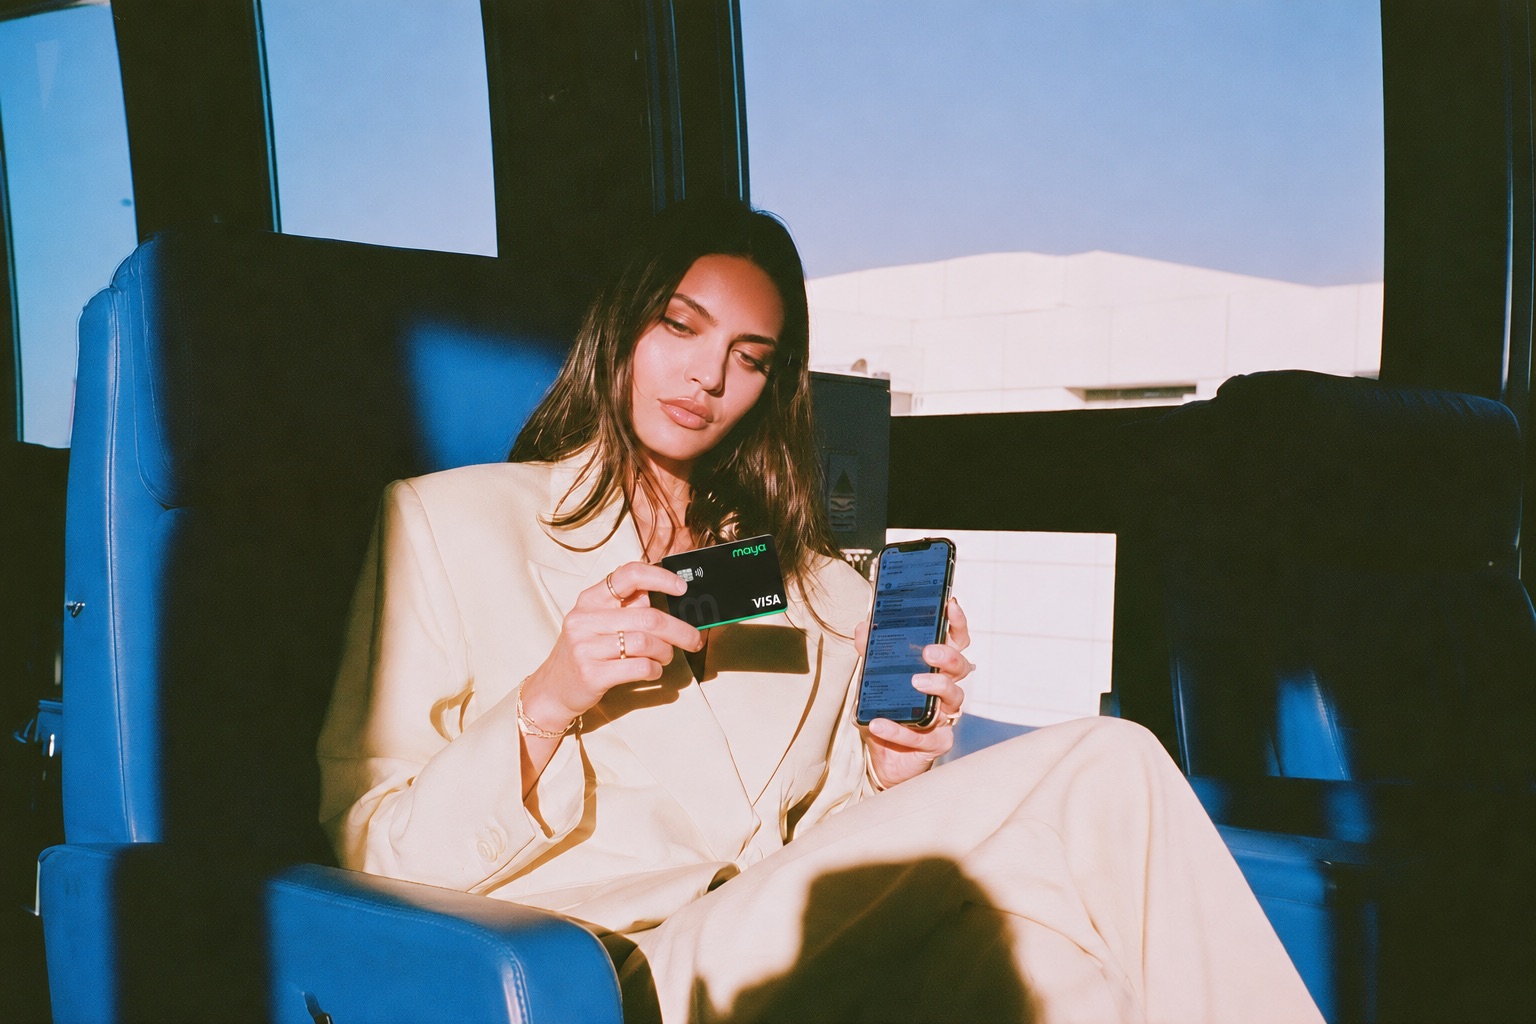
The rapid adoption of digital wallets has changed how people make payments and track their finances. Thanks to their ability to store and transfer funds digitally, e-wallets provide a convenient and secure way to manage everyday transactions. This shift towards digital solutions has also led to innovative ways to simplify financial management, with one such advancement being the ability to link your card to your e-wallet.
Merging the functionality of a physical card with the accessibility of a digital wallet will definitely offer you greater flexibility in managing both your online and offline transactions. It’s no surprise that many others are embracing this combined approach. Nevertheless, some still question whether getting a card that’s linked to a digital wallet is worth any of the perceived hassle. Here are some reasons why this integration can be beneficial for your day-to-day financial activities:
1) Unified Management of Finances
Upon getting a card that can be linked to your e-wallet, you’ll gain the ability to manage all your finances from a single point of access. Instead of switching between different apps or platforms, you’ll be able to see your card transactions alongside your e-wallet activity in real time. This unified approach allows you to keep track of your spending, view your balances, and review all your transaction histories in one place. As a result, you’ll gain a clearer picture of your financial health, which will make budgeting and financial planning much easier.
2) Easier Transfers and Withdrawals
Next, having a card that links to your e-wallet makes managing your funds much simpler. Whenever you need to transfer money between your e-wallet and bank account, you can complete the transaction with just a few taps on your smartphone.
If your card and digital wallet are made by the same digital bank, this process becomes more seamless. Having both the card and e-wallet integrated within the same ecosystem eliminates the need for multiple apps or services.
Take the Maya Card as an example. Since this card is offered by Maya—the #1 digital bank in the Philippines—you can use it alongside your Maya account. Linking this card to your account gives you direct access to your savings without any complicated setup. That means that whenever you need to top up your wallet, you can simply transfer money from your Maya Savings to your Maya Wallet for free.
In addition to easier and faster access to your funds, you can use your Maya Card to withdraw from any BancNet ATM and any ATM that accepts VISA and MasterCard. That means that you can withdraw cash from a wide range of locations and take advantage of greater flexibility and convenience whenever you need it.
3) Increased Payment Flexibility
Even though e-wallets are accepted in many stores, there are situations in which card payments are more convenient. For instance, if you’re shopping at a major grocery store chain, you can use your card to simply tap or dip at the payment terminal. This is quicker than using cash or scanning a QR payment code and may streamline the checkout process significantly for you.
Another example is when you’re purchasing from an international online store. Since cards are more universally accepted, most global retailers prefer card payments over digital wallets. Having a card linked to your e-wallet allows you to shop seamlessly across borders, thus expanding your purchasing power.
4) Global Accessibility
A major advantage of getting a physical card that can link to your e-wallet is that it lets you access your funds even outside the Philippines. With most cards powered by VISA or MasterCard, you can easily pay for purchases at millions of stores, restaurants, and hotels abroad. This way, you won’t have to rely solely on carrying cash or making overseas bank withdrawals. Plus, your purchases are automatically debited from your digital wallet, giving you better control over your spending wherever you are.
5) Better Security
Linking your physical card with your e-wallet lets you benefit from the protections provided by digital banks. These financial institutions employ a range of security features to safeguard your transactions, so you can rest assured that your money and personal information are protected, whether you’re using your digital bank or linked card.
For instance, digital banks use advanced encryption to ensure that your data remains private and secure when making payments or transferring funds. Many also offer two-factor authentication (2FA) to block unauthorized access to your account. Additionally, a reputable digital bank will enable you to quickly lock or suspend your card via the app. In the event of loss or theft, you can immediately disable your card to prevent any unauthorized transactions. With these security measures in place, you’ll have greater control over your finances and enjoy full peace of mind when making purchases both online and in-store.
One practical step many users overlook is setting up spending alerts and category tracking inside the same app. When your card and e-wallet live together, you can turn on notifications for every transaction over a set amount and tag purchases by type (groceries, transport, subscriptions). Over a few weeks this creates a simple, real-time picture of where money actually goes without exporting spreadsheets or waiting for a monthly statement. That visibility makes it easier to catch subscription creep or small leaks early, and it turns the combined card-and-wallet setup into an active budgeting tool rather than just a payment method.
Ultimately, being able to link your card to your digital wallet can add a lot of convenience to your financial routine. With both tools integrated within the same ecosystem, you’ll have an easier time handling payments and managing your finances, and you can expect that same setup to help you adapt to today’s quickly evolving financial trends.
Starting a business involves more than having a good idea or knowing how to attract customers. The decisions you make about money before launching a company can affect how prepared you are to handle the responsibilities that come with running one. From managing expenses to deciding when to take financial risks, many of the skills needed in entrepreneurship are developed through everyday financial experiences.
Your personal financial situation doesn’t have to be perfect before you start a business. However, understanding where your money goes, how much you can afford to invest and what financial commitments you already have can make the process considerably easier. Entrepreneurs who pay attention to these details are often better prepared to deal with unexpected costs, changing income and the demands of growing a company.
The connection between personal finance and entrepreneurship becomes especially clear when you consider how many business decisions depend on the owner’s financial circumstances.
Why Personal Financial Stability Matters When Starting a Business
Financial stability gives entrepreneurs greater flexibility when making important decisions. A person who has manageable living expenses, some savings and a clear understanding of their financial obligations may find it easier to concentrate on developing a business without constantly worrying about covering household bills.
This becomes particularly important during the early stages of entrepreneurship, when revenue can be unpredictable. Even businesses with promising products or services may take months to establish a steady customer base. During that period, owners still need to pay for housing, groceries, transportation and other personal necessities.
Without adequate financial preparation, these expenses can create pressure to withdraw money from the business before it has developed a reliable income stream.
Maintaining financial stability doesn’t necessarily require a large amount of savings. It begins with understanding existing expenses, reducing unnecessary commitments and establishing realistic expectations about how much personal income the business can initially provide.
Someone who knows they need a certain amount each month to cover essential expenses can use that information to develop a more practical business plan. This approach also makes it easier to determine whether starting a company immediately is realistic or whether additional preparation would be beneficial.
How Budgeting Skills Translate Into Better Business Decisions
Managing a household budget and managing business expenses involve many of the same principles. Both require individuals to understand their income, monitor spending and make decisions about how to use limited resources.
When people develop consistent budgeting habits in their personal lives, they become familiar with evaluating expenses rather than making decisions based entirely on what they can afford at a particular moment.
For example, someone who regularly reviews household spending may already understand the importance of distinguishing essential expenses from optional purchases. That same judgment becomes valuable when deciding whether a business needs new equipment, additional software or a larger workspace.
Entrepreneurs also need to recognize that available cash isn’t necessarily money that can be spent freely. Some funds may be needed for upcoming bills, taxes or other commitments.
According to the U.S. Small Business Administration, financial management is an important part of running a business, with budgeting and cash flow planning helping owners understand their financial position and prepare for ongoing expenses.
Developing these skills before launching a company can reduce the learning curve associated with managing business finances. It also encourages entrepreneurs to make spending decisions based on actual needs rather than short-term enthusiasm.
The Importance of Building Savings Before Taking Financial Risks
Entrepreneurship involves uncertainty, and savings can provide valuable financial protection when circumstances don’t develop as expected.
A business may experience slower sales during certain months, encounter unexpected repair costs or require additional investment before becoming profitable. When the owner has no personal financial cushion, these situations can quickly affect household finances.
Establishing an emergency fund can help separate temporary business difficulties from personal financial emergencies. It may also reduce the likelihood of relying on expensive credit to cover routine living expenses.
The appropriate amount to save depends on several factors, including household costs, existing financial obligations and the stability of other income sources.
Entrepreneurs leaving traditional employment may need to plan more carefully because they are giving up a predictable paycheck. Someone who continues working while developing a business may have more flexibility, although they still need to consider the financial demands of both responsibilities.
Savings also influence how business owners approach opportunities. Having funds available can make it easier to invest in necessary equipment, professional services or improvements without placing immediate pressure on household finances.
However, maintaining a personal emergency fund separately from money reserved for business operations is important. Each serves a different purpose, and combining them can make it difficult to understand how much financial protection is actually available.
Understanding Credit and Making Responsible Borrowing Decisions
Credit management is another personal financial skill that can influence entrepreneurship. Business owners may eventually need financing for equipment, inventory, workspace improvements or expansion, making it useful to understand how borrowing works before taking on additional obligations.
Personal credit history can also matter when applying for certain forms of small business financing, particularly when a company has a limited operating history.
Paying bills on time, monitoring outstanding balances and avoiding unnecessary debt can help individuals maintain a stronger personal financial position.
Still, responsible credit management involves more than maintaining a favorable credit score. Entrepreneurs need to consider whether borrowing supports a meaningful financial objective and whether future income will comfortably cover repayment obligations.
For instance, purchasing equipment that improves productivity may provide a measurable business benefit. Borrowing to fund unnecessary upgrades, on the other hand, can increase monthly expenses without improving revenue.
Credit cards can also be useful for organizing certain purchases, provided spending remains controlled. Some consumers compare card features to understand how they can earn reward points based on their regular purchasing patterns. While rewards may offer additional value, interest charges and annual fees can quickly outweigh those benefits when balances aren’t managed carefully.
Business expenses should also be kept separate from personal purchases whenever possible. Maintaining that distinction simplifies recordkeeping, supports more accurate financial reporting and helps owners understand how their companies are performing.
How Personal Spending Habits Affect Business Growth
An entrepreneur’s relationship with spending can influence the decisions they make after their company begins generating revenue.
Some people are naturally cautious about spending, while others are more comfortable making purchases when money becomes available. Neither approach guarantees success, but understanding these tendencies can help business owners recognize potential problems.
For example, an owner who is accustomed to spending most of their personal income may be tempted to treat increasing business revenue as money available for immediate personal use.
However, business revenue isn’t the same as profit. Operating costs, taxes, debt payments and future investment needs must be considered before determining how much money can reasonably be withdrawn.
Owners who understand this distinction are better positioned to protect working capital and prepare for periods when expenses exceed incoming payments.
Personal spending habits can also affect decisions involving business growth. Expanding too quickly may create financial pressure, especially when new expenses are based on expected sales rather than established demand.
At the same time, avoiding every expense can prevent a business from improving its services or reaching new customers.
The objective is to develop balanced spending habits that encourage thoughtful investment while protecting the company’s financial resources.
Final Thoughts
Your approach to personal finances can influence nearly every stage of your entrepreneurial journey, from deciding when to start a business to managing its growth over several years.
Budgeting, saving, responsible credit use and long-term planning are not exclusively personal financial concerns. They also help develop the judgment needed to handle business expenses, assess opportunities and respond to financial uncertainty.
Although strong personal financial habits cannot guarantee entrepreneurial success, they can provide a more dependable foundation for making important decisions. By developing these habits early and adapting them as circumstances change, aspiring business owners can approach entrepreneurship with greater financial awareness and a clearer understanding of the responsibilities ahead.

The Year-End Tax Moves Every One-Person Business Should Make Before December 31

How to Work With a Proactive AI Agent Without Losing Control of Your Day

How to Successfully Prepare for a Criminal Trial

The Hidden Cost of Staying Cash-Only: Why Accepting Cards Is a Growth Strategy for Solo Entrepreneurs

The Hidden Infrastructure Upgrade: How a Reliable Well System Supports Property Value
5 Ways For Startups To Succeed Making Acquisitions

77 Inspirational Quotes That Will Change Your Life
57 Memorable Kobe Bryant Quotes

Motivational Picture Quotes: 52 Images to Inspire a Successful Year
40 Rare Motivational and Inspirational Picture Quotes
3 Prince EA Videos To Change Humanities Path To Greatness
(Video) What Is Success? An Entrepreneurial Story To Inspire You
(Inspirational Video) What If Today You Knew You Were Going To Take Your Last Breath?
How To Make Enough Money From A Blog To Quit Your Job – Kate McKibbin
How Finding Your Passion And Becoming An Entrepreneur Can Lead To Happiness – Chiquita Searle
-

 Did You Know1 year ago
7 Surprising Life Lessons Video Games Taught Me That School Never Did
-
 Life2 years ago
The 5 Stages of a Quarter-Life Crisis & What You Can Do
-
 Success Advice1 year ago
Stephen Covey’s 8 Leadership Habits That Will Change How You Lead Forever
-

 Featured2 years ago
The Psychology of Motivation: How to Keep Moving Forward Every Day
-

 Life1 year ago
How to Stop the War in Your Head and Find Peace
-
 Personal Development1 year ago
The Three-Second Pause That Changes How People Perceive You
-
 Explode Your Social Media1 year ago
Want More Views? Master These 6 YouTube Growth Tactics
-
 Change Your Mindset1 year ago
You Become What You Absorb: How Input Shapes Your Life