Wealth
Is a Tesla with a Novated Lease Right for Your Budget?

Key Highlights
- A Tesla with a novated lease can reduce your taxable income through salary packaging and make lease payments easier to budget.
- Eligible electric vehicle models may qualify for an FBT exemption, which can improve your overall cost.
- Most lease packages can include running costs like charging, insurance, maintenance, and roadside assistance.
- Your employer, you, and a lease provider all play a role in setting up the lease agreement.
- The right fit depends on your financial situation, lease term, and the purchase price of the Tesla model.
- A novated lease calculator helps you estimate monthly payments before you commit.
Introduction
Considering a Tesla with a novated lease but unsure about affordability? You are not alone. The purchase price of a Tesla is an important factor to consider when assessing affordability. A novated lease lets you pay through your salary, potentially improving cash flow and tax benefits. The key question: Is it better for your finances than buying outright?
Understanding Tesla Novated Lease Options in Australia
In a novated lease in Australia, you choose a Tesla with a novated lease and sign an agreement with a lease provider for a fixed term. Instead of paying the full price upfront, you make lease payments over time through salary packaging, and it’s important to consider interest rates associated with the lease.
This can make electric cars more affordable. Eligible EVs may also receive tax benefits, making novated leasing more attractive compared to many petrol cars. Here’s how it works:
What Is a Novated Lease and How Does It Work for Teslas?
A novated lease is a three-way agreement between you, your employer, and a lease provider. You choose a Tesla model, and it’s financed over a set term—usually one to five years.
Your employer typically deducts the novated lease costs through salary packaging, which may include both pre-tax and after-tax contributions for the vehicle and eligible running costs. This setup can lower your taxable income and reduce your tax bill, which in turn affects the tax you pay each pay cycle.
The Role of Salary Sacrifice in Novated Leasing
Salary packaging is central to novated leasing. Instead of paying vehicle costs from your after-tax income, your employer deducts lease payments from your pre-tax salary, lowering your taxable income.
This can help if you’re managing a tight budget—fixed deductions make expenses predictable and simplify planning. For some households, this frees up money for other needs.
Eligibility Criteria for a Tesla Novated Lease
Not every worker or vehicle setup will qualify in the same way, so it is smart to check the basics early. A lease provider will usually look at your employment setup, the lease agreement terms, and whether salary packaging is available through your employer to access the latest technology.
Your financial situation also matters because you need to support the lease term and ongoing deductions, especially at the time of writing. If you are comparing novated lease offers for a Tesla model, focus on eligibility before you get too far into pricing.
Requirements for Employees and Employers
To use salary packaging, your employer must support payroll deductions; otherwise, a novated lease isn’t possible. You should also be comfortable with the lease terms and ensure your income can cover regular pre-tax deductions.
Approval depends on factors such as your employer’s salary-packaging arrangements, the lease terms, and your ability to meet the required repayments. In reality, it depends on whether your employer can handle the setup and if your finances can sustain fixed deductions, which can affect your income tax obligations.
Can You Lease Used Teslas with a Novated Lease?
The information focuses on new Tesla models like the Model 3 and Model Y, but also covers used cars. Check with your lease provider about available novated lease options in Australia.
A used Tesla may have lower lease costs, but its eligibility for tax benefits depends on the vehicle and the specific requirements that apply to the novated lease.
If considering a used Tesla, check with the lease provider whether the vehicle is eligible for a novated lease and separately confirm whether any applicable tax benefits are available.
Exploring Tesla Models Available for Novated Lease
For many buyers, the main question is: which Tesla model is available? The Model 3 and Model Y are the most popular EV novated lease options.
Both are accessible through novated lease providers. When comparing packages in Australia, your best choice depends on cost, features, and how each model fits your budget.
Comparing Tesla Models for Lease Suitability
Choosing the right Tesla for a novated lease involves considering the vehicle’s price, running costs, practicality, and how well it fits your needs over the lease term.
A quick comparison can narrow your options. The Model 3 and Model Y are popular choices, with the Model Y RWD often searched as a specific variant.
| Tesla Model | Lease Suitability Notes |
| Model 3 | Ideal for drivers seeking new cars, tax savings, and predictable regular payments. |
| Model Y | Great for those needing more space and meeting EV criteria; a common leasing option. |
| Model Y RWD | A frequently compared version if you want to evaluate lease costs within the same model line. |
The Tesla Novated Lease Process Step-by-Step
If the idea appeals to you, the next step is understanding the order flow. The process is straightforward, and knowing each stage can make a novated lease less intimidating.
Typically, you choose a vehicle, work with a lease provider, complete the agreement, and get financial approval before delivery. Using a novated lease calculator early on helps estimate affordability before starting the paperwork.
Ordering Your Tesla Through a Lease Provider
First, choose your Tesla model and confirm the vehicle you want. Compare novated lease offers and see how the sale price impacts your package.
Next, the lease provider structures your arrangement, including the car and any optional running costs. The goal is a clear payment plan, so you’re never left guessing.
Documentation and Financial Approval
Once you select a vehicle, the paperwork starts. You will need a lease agreement between you, your employer, and the provider to ensure correct salary deductions.
Financial approval confirms affordability. While a novated lease calculator offers an estimate, approval verifies that lease payments suit your income and payroll.
Financial Benefits of Leasing a Tesla via Novated Lease
For many drivers, the strongest reason to consider this option is the money side. A novated lease can combine tax savings, salary packaging, and bundled running costs in a way that changes the overall cost of driving a Tesla.
That does not mean it is automatically right for everyone. Still, when fringe benefits rules and government incentives line up for eligible EVs, the numbers may look far better than expected. Here is where those savings usually show up.
Tax Advantages and FBT Exemptions
Leasing a Tesla through a novated lease can offer tax benefits, notably the FBT exemption for eligible electric vehicles, which can significantly increase savings.
However, federal rules are specific. Eligibility for the EV FBT exemption depends on specific requirements, including the vehicle type and its value in relation to the relevant luxury car tax threshold.
Calculating Your Monthly Lease Cost
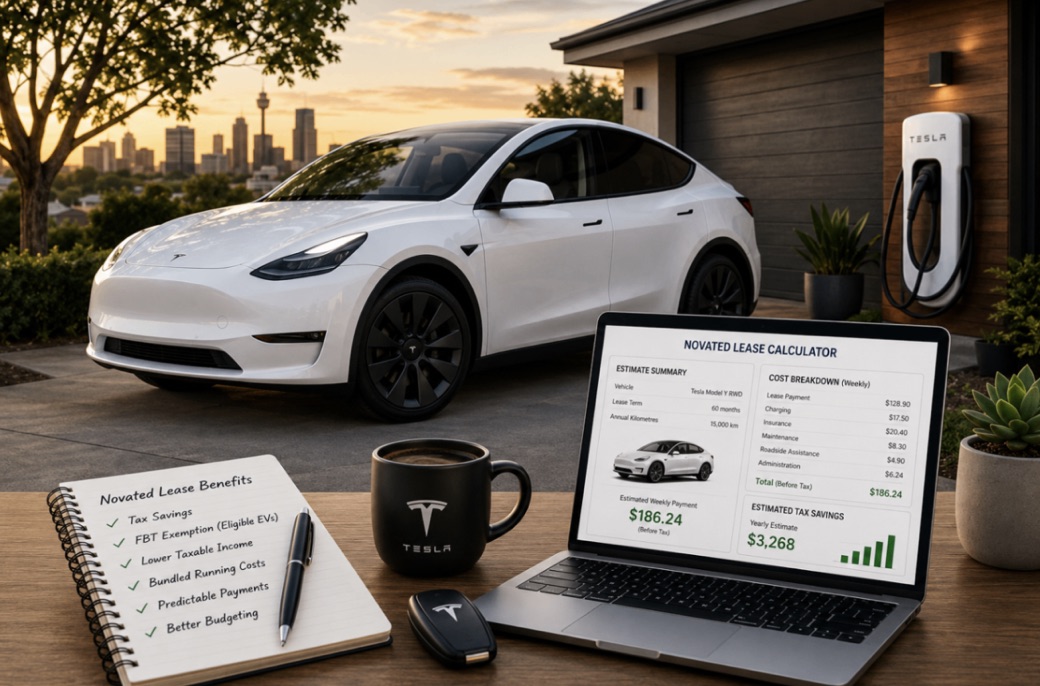
A novated lease calculator estimates your monthly payments based on the vehicle cost and package structure. It helps you gauge overall costs before applying.
Your exact payment depends on the lease details and term length; shorter terms or added costs may increase monthly payments.
Salary Packaging Scenarios Explained
The main pros and cons of a Tesla novated lease come down to structure. The upside is that salary packaging can reduce taxable income and simplify vehicle budgeting, making it an attractive option for many. The trade-off is that the arrangement still needs to suit your personal circumstances.
Managing Ongoing Expenses with a Tesla Novated Lease
Budgeting for the car is just the beginning. You also need to consider ongoing driving expenses.
A well-structured novated lease can cover selected running costs, turning unpredictable bills into regular payments. For Tesla drivers, this often includes charging, insurance, maintenance, and roadside assistance.
Included Running Costs: Charging, Maintenance, Insurance
A key benefit of a novated lease is bundling running costs into one plan, reducing bill shock and making budgeting easier.
This is especially useful for Tesla buyers, who often overlook day-to-day expenses. Including these costs in your lease makes ownership more predictable.
Made with AI
Conclusion
A Tesla novated lease may offer tax and budgeting benefits, depending on your individual financial circumstances and eligibility. By understanding salary sacrifice, eligibility, and ongoing costs, you can make an informed decision. Enjoy tax advantages and bundled expenses for greater convenience and potential savings. Ready to learn more? Get a free consultation to see if a novated lease fits your financial goals.
Frequently Asked Questions
Is it worth getting a Tesla on a novated lease in Australia?
A novated lease can be worthwhile if it lowers your taxable income, offers predictable payments, and fits your finances. For eligible Tesla models, tax savings on electric cars can make this option more affordable than many expect.
What ongoing costs are covered under a Tesla novated lease?
A Tesla novated lease can cover running costs like charging, maintenance, insurance, and roadside assistance. Bundling these into your lease payments gives you a clearer monthly budget and reduces separate car-related bills.
Are there tax benefits to leasing a Tesla through a novated lease?
Yes. The main tax benefits of novated leasing are salary packaging and, for eligible EVs, possible FBT exemption. If the Tesla qualifies, avoiding fringe benefits tax can significantly increase the lease’s value.









A money blueprint is the set of beliefs about money you absorbed from the house, culture, gender and faith you grew up in, and it quietly decides how much you let yourself earn and keep. To change your money blueprint, you trace each belief back to where it came from, keep the ones that still serve you and deliberately retire the ones you’ve outgrown.
I first heard Lisa Nichols break this down on my podcast in 2016. She’d just launched her book Abundance Now, and I wanted to know how she went from food stamps and $11.42 in the bank to running a multimillion dollar business. I figured she’d hand me a list of hustle tips. She did. But the part I still think about is the moment she admitted she’d been putting the brakes on her own income without knowing it.
What is a money blueprint?
Here’s how Lisa described it: “We all have a money blueprint that comes from the house you were raised in. How did they relate to money? Because that’s an unconscious reaction to money that you will have.”
Notice the word unconscious. She wasn’t saying you’ll copy your parents. She said it straight: “Not that you’re going to react to money the same way. You just have to be aware of it.” The blueprint isn’t a sentence you’re serving. It’s a default setting, and defaults run the show until somebody changes them.
Financial psychologists call the same idea money scripts. In a 2011 study in the Journal of Financial Therapy, Brad Klontz and colleagues asked 422 people how strongly they agreed with 72 money beliefs. They found four distinct belief patterns, and three of them were significantly linked to income and net worth. The beliefs you carry show up in your numbers.
The $975,000 story that shows how a money blueprint caps your income
This is the bit that made me stop and lean in. Lisa grew up in South Central Los Angeles, living paycheck to paycheck with her mom. Years later, her company had made $975,000 by October. “I slowed down. I took the rest of the year off,” she told me. She thought she was just tired.
The next year it happened again, only faster. She had $985,000 by August and wanted to take the rest of the year off again. That’s when it clicked for her: “It wasn’t the fact that I was tired. It was the fact that I wasn’t comfortable being an African-American woman from South Central Los Angeles, raised a Christian, a Baptist. I wasn’t comfortable in all of my money blueprint. I wasn’t comfortable making a million dollars in one year.”
If you run a business, read that twice. She didn’t hit a market ceiling. She hit a comfort ceiling, twice, a few thousand dollars short of seven figures. And she called it fatigue.
That’s how a money blueprint usually shows up. Not as a belief you’d say out loud, but as a sudden urge to coast right before the number that would change how you see yourself.
The four money blueprints you’re carrying
Lisa didn’t stop at the house you grew up in. She broke it into layers, which gives you somewhere specific to look.
| Blueprint | Where it comes from | What Lisa said about it | Question to ask yourself |
|---|---|---|---|
| Family | The house you were raised in | “How did they relate to money?” | What did money feel like at the dinner table? |
| Culture | Your environment, “not necessarily your race” | “Is money the root of all evil… or is money the access to all prosperity?” | What did people around you say about rich people? |
| Gender | What you were taught a man or woman should want | Women told “service first,” men judged by “how big are your toys” | What did you learn money says about you as a man or woman? |
| Spiritual | The faith you were raised in | “If it serves you great, bring it to the forefront” | Do you secretly believe having more makes you less good? |
The gender one is where we got into it. Lisa said, “You and I, Joel, have a different relationship to money because I’m a woman and you’re a man.” As a woman, she said, she was taught “service first and just don’t worry about money. Just get a good man who makes money.” As a man, I was handed a different pressure: “how much you make and what are you driving and how big are your toys.”
Neither version is healthy. One tells you money isn’t your business. The other tells you money is your whole worth. Lisa’s answer for herself was blunt: “I have the right to be in the top 1% income earners and I’m still feminine.”
Where Sister Brown comes in
When Lisa mentioned being raised Baptist, I asked whether somebody at church had planted the idea that money wasn’t the way to go. She lit up. “Oh, you just named it. It was Sister Brown.”
Sister Brown was, in Lisa’s words, “an angel on earth,” and she’d say it all the time: “Baby, you don’t need much to get to heaven. You don’t need much to get to God.” Lisa loved her, which is exactly why it stuck. “When I started having much, I began to think I was less godly. I was less spiritual. I was less giving. I was less serving.”
This is why I don’t buy the idea that money blocks come from bad people. Most of the beliefs holding you back were handed to you by people who loved you and meant well. That’s what makes them so hard to question. It can feel like you’re arguing with grandma.
How to change your money blueprint in 5 steps
Lisa’s fix wasn’t to rip out her faith or her history. It was to look at each piece and decide what stays. Here’s how I’d put her approach into practice.
- Write down the house rules. List every money phrase you heard growing up, word for word. “Money doesn’t grow on trees.” “Rich people are greedy.” “You don’t need much.”
- Sort them into the four blueprints. Family, culture, gender, spiritual. For Lisa, the spiritual one did the most damage.
- Find your slow-down point. Look back at your best months or years. Where did you coast, get sick, start a pointless project or “need a break”? Lisa’s tell was taking the rest of the year off right before a million. Yours might be smaller. It’s still a tell.
- Thank it, then retire it. This is Lisa’s line, and I love it: “If you’ve outgrown it, say, thank you so much, blueprint. You got me to this point and I’ve outgrown you.” You’re not calling your upbringing wrong. You’re saying it was built for a smaller life.
- Give money a new job description. Lisa calls money “a tool and a team member,” and she said, “Money just gives me access to better memories.” For her, that meant surfing and jumping out of a plane with her son on the Gold Coast for his 21st birthday. Write down what money is actually for in your life, in specifics.
Then make it real. If you run a business and still feel weird every time you pay yourself, that’s the blueprint talking. Getting clear on how to pay yourself as a business owner is one of the fastest ways to turn a new belief into a new habit.
Signs your money blueprint is holding you back
Watch for these:
- You hit a new income high and then drift back down the following months.
- You feel guilty, not proud, when a client pays you well.
- You undercharge people you like and resent it later.
- You talk about rich people the way your family did, even though you want to be one.
- You spend your best hours on low-value work because it feels safer than selling.
That last one matters more than people think. Lisa runs her company on a rule she called spending “dollar time on dollar tasks.” Everyone, from the receptionist to her CFO, aims for “the highest revenue generating activity… that only you can do.” If you keep finding reasons to hide in the spreadsheet instead of making the offer, it’s worth asking honestly what your time is worth and why you keep pricing it like pennies.
Why good people should do very well
Here’s where I land. A lot of generous people carry a quiet belief that wanting more money makes them less good. Lisa spent years with that belief and it nearly kept her under a million twice.
What turned it around was deciding the two things weren’t in conflict. “My spirituality is unquestionable. My service is unquestionable,” she said, “and I can do more good in the world because I run a multimillion dollar business now.” Then she said the line I want you to take with you: “I believe good people like you should do very, very well.” Her reason was simple: “When good people do well, good people do more good in the world.”
So do the work this week. Write the house rules down. Find your slow-down point. Thank the old blueprint for getting you here, and then stop letting it decide what you’re allowed to earn.
FAQ
What is a money blueprint?
A money blueprint is your set of unconscious beliefs about money, picked up from your family, culture, gender and faith. It shapes how much you earn, keep and feel comfortable having, often without you noticing until you hit a ceiling.
Can you change your money blueprint?
Yes. Start by writing down the money beliefs you grew up with and where each came from. Keep the ones that serve you, consciously retire the rest, and back the new belief with a concrete habit, like paying yourself on a schedule.
What is the difference between a money blueprint and a money script?
They describe the same idea. “Money script” is the term financial psychologists Brad and Ted Klontz use in research. “Money blueprint” is the more common self-development phrase for the beliefs about money you learned early and still act on.
How do I know if my money blueprint is holding me back?
Look for patterns: coasting right after a record month, guilt when you’re paid well, undercharging, or talking about rich people the way your family did. Lisa Nichols noticed she kept taking months off just before reaching a million dollars in a year.
What did Lisa Nichols say about money blueprints?
On my podcast in 2016, Lisa Nichols said we all carry a money blueprint from the house we were raised in, plus culture, gender and spiritual blueprints. Her advice: if you’ve outgrown one, thank it for getting you here and let it go.
“You will never earn your way to a fortune” means a bigger income alone is not a wealth-building plan: some of what you earn has to become something you own. In my 2015 conversation with Tony Robbins, that distinction connected an extraordinary UPS employee’s story with a much more personal question: what should the money, and the platform I was building, actually do for other people?
I opened by admitting I was only about three chapters into Money Master the Game. I was working through it, not presenting myself as someone who had already mastered everything inside. I wanted to understand the mechanics, but I also wanted to understand contribution.
Later, I told Tony that Addicted2Success was receiving around two million views a month at the time. I felt we could give back more. If he were in my shoes, how would he maximize the impact? His answer belongs beside his money advice, because both challenged the same habit: postponing the important action until you feel big enough to begin.
A bigger paycheck does not automatically make you an owner
Tony’s reason for writing the book started with the 2008 financial crisis. He described watching people lose homes and retirement savings, and wanting to use the access he had. He said he had coached Paul Tudor Jones for about 21 years and had sought out around 50 financial minds to understand what they had in common.
But the takeaway I would put first is not a hedge fund strategy. It is the distinction between earning money and retaining ownership of something that can grow.
Tony used Mike Tyson as his example of enormous earnings followed by bankruptcy. I am using it here as Tony’s illustration, not repeating his estimate of Tyson’s lifetime earnings as a verified number. His point was that a spectacular inflow does not protect you if the money keeps flowing out.
That does not make earning unimportant. Income pays for food, housing and the responsibilities that cannot wait. More of it can make an enormous difference. The mistake is expecting a higher income to make every other decision for you. You can improve the engine and still send everything it produces straight through the exhaust.
Theodore Johnson’s “wealth tax” changed the order
Tony told me about Theodore Johnson, who worked for UPS. In Tony’s account, Johnson never earned more than $14,000 in a year, eventually had $70 million in retirement and gave away $35 million while he was alive. Those are the figures Tony gave in our 2015 conversation, not an audited biography or a result readers should expect to reproduce.
The story turned on a friend challenging Johnson’s claim that he had nothing to invest. If the government imposed another 20% tax, the friend argued, he would protest but find a way to pay it. So the friend proposed a different kind of “wealth tax”: put 20% into an investment account, leave it alone and allow it to compound.
What interests me is the order. Johnson did not first have to feel wealthy enough to behave differently. In Tony’s telling, the money was directed toward ownership before it could disappear into everything else. Automation made the decision less dependent on a fresh burst of discipline every payday.
I would not turn that anecdote into a universal 20% instruction. Someone struggling with essentials or expensive debt needs a plan that fits reality. The useful question is whether there is a deliberate process at all, rather than a permanent promise to invest whatever happens to remain.
Compounding means gains can themselves generate gains over time. It does not mean investments rise without interruption, or that one person’s extraordinary outcome establishes your likely return. The habit and the outcome are different things. Tony’s story is a reason to learn about the first, not a guarantee of the second.
Earning more versus becoming an owner in practice
Here is how I would translate the distinction into questions you can actually ask. Neither column is a complete financial plan. The point is to notice when you are using an income goal to avoid making an ownership decision.
| The decision | Earning more alone | Becoming an owner in practice |
|---|---|---|
| A stronger month | Measure success by the larger deposit | Ask what remains after obligations and spending |
| The next pay increase | Let the whole increase become lifestyle | Decide deliberately what can support future ownership |
| Getting started | Wait until the income feels impressive | Learn the mechanics and assess a sustainable starting amount |
| An exciting opportunity | Focus only on the possible upside | Understand the risks, costs and possible losses |
For founders, that starts with separating how to pay yourself as a business owner from the temptation to treat every dollar in the company account as personal wealth. A business can hold cash that is already needed elsewhere. Ownership is not permission to ignore those commitments.
Tony also discussed Ray Dalio sharing an “All Seasons” approach for the book, and said 98% of the best investors, in his telling, sought asymmetric risk and reward. I would keep the principle of questioning downside, not turn this conversation into instructions for copying a portfolio. Access to an impressive name is not a substitute for understanding what you are doing.
The psychology is not separate from the money
Tony described mastering money as roughly 80% psychology and 20% mechanics. That was his teaching split, not a scientific measurement of every household. The mechanics still mattered. But how you feel about scarcity, spending and starting affects whether you use them.
You can understand an investment concept and still believe it is only for people richer than you. You can get a raise and immediately redefine what you need. This is where the difference between a high income and actual wealth becomes more than a definition: your next spending decision can either respect it or erase it.
Tony’s giving example made that psychological point uncomfortable in a useful way. If you will not give a dime out of a dollar, he said, you will not suddenly give a million out of ten million. In his explanation, giving now teaches your brain that there is more than enough, rather than keeping generosity locked behind a future milestone.
I do not read that as a promise that donating creates investment returns. Nor does it mean giving away money needed to keep your family safe. It means the habit of contribution can start before the grand version of your life arrives.
What the money buys matters as much as the number
Tony described research he had been reading in 2015. He mentioned an income threshold often around $65,000 in different countries, then emphasized how money was spent: experiences could keep giving through memory, removing drudgery could free time, and giving, he said, had the strongest biochemical effect.
I am sharing his summary from that conversation, not offering that dollar figure as a current happiness ceiling or presenting a new scientific review. What I find useful is the question it raises: are you buying a moment of excitement, an experience you value, relief from a recurring burden, or help that reaches someone else?
Those are different jobs for money. A larger income does not automatically tell you which one matters. If every increase only buys a more expensive version of your current frustration, you have improved the number without examining the life around it.
I asked Tony what Addicted2Success should do next
Tony’s contribution story began with his own family receiving food when he was 11. He said that experience showed him strangers cared. At 17, he fed two families, then expanded the effort and brought friends in.
During our conversation, he described a Feeding America effort and matching funds intended to feed 100 million people that year. That was his account of the scale he was pursuing in 2015, not a current charity report. But when I asked how Addicted2Success could contribute more, he did not tell me to start with that scale.
He suggested a roughly 90-day journey. Once a week, or about every ten days, go experience someone else’s contribution work. See what moves you. Then work out a first way to engage with the cause that connects emotionally, instead of trying to design the ultimate project before you have been involved.
“A belief is a poor substitute for an experience,” he told me.
That was a direct answer to my question as a founder. A traffic figure could tell me about reach. It could not tell me what form of service I would connect with, or what people doing the work actually needed. His advice was to go find out.
- Experience the work. Get involved with an existing effort rather than choosing a cause only because it sounds impressive.
- Notice what connects. Pay attention to what moves you and where there is a real need, not just a good story to tell.
- Start with a useful first contribution. Tony began with two families. Learn from the first version and iterate instead of making enormous scale the entry requirement.
Love is an act, not a future intention
When I asked for his hypothetical last 30-second speech to the world, Tony said the theme would be that life is love, and “love is an act. It’s not a thought.” He spoke about letting love and contribution guide decisions toward a meaningful life, not expecting everything to be easy or happy.
That brings me back to the fortune question. Earning is useful. Owning can give the money a future beyond the next payment. Contribution gives you a reason to care about that future beyond the number itself. None of those jobs gets done just because you intend to do it later.
This is education from our conversation, not personal financial, investment or tax advice. Match any decision to your circumstances with qualified help. But do not confuse needing a suitable plan with needing to become a millionaire before you can begin learning, retaining something or helping someone.
Frequently Asked Questions
Why did Tony Robbins say you will never earn your way to a fortune?
In my 2015 conversation, Tony distinguished earning income from becoming an owner or investor. His point was that even enormous earnings can disappear if nothing is retained. Ownership and compounding were the alternative he wanted people to understand.
What was Theodore Johnson’s wealth tax in Tony’s story?
Tony described a friend persuading UPS employee Theodore Johnson to direct 20% of his income into investments automatically. He attributed Johnson’s extraordinary later wealth to compounding. The story illustrates a process, not a guaranteed outcome or universal savings rate.
What did Tony mean by giving a dime out of a dollar?
He challenged the idea that generosity begins only after wealth arrives. Giving a small amount now, he explained, helps challenge scarcity thinking. He was describing a psychological practice, not promising that donations produce financial returns or remove real constraints.
What did Tony suggest when Joel asked about Addicted2Success’s impact?
He suggested roughly 90 days experiencing other people’s contribution work, perhaps weekly or every ten days. The aim was to discover what connected emotionally, then begin with a useful contribution and iterate rather than waiting to design an enormous initiative.
How did “love is an act” connect to the money conversation?
In his closing answer, Tony described love and contribution as guides for decisions that make life meaningful. Alongside the money discussion, that gives wealth a purpose beyond accumulation: what you actually do for others, not simply what you intend.
The fractional CFO vs full-time CFO decision comes down to how often your business needs senior financial judgment. Choose fractional leadership when the work fits an agreed schedule; choose a full-time CFO when daily decisions, team leadership and financial complexity require dedicated attention. If your main problem is inaccurate books, strengthen accounting before buying either title.
Picture a founder opening the bank app before approving a new hire. Sales look healthy. Payroll is covered today. But a customer is late, inventory needs paying for, and the founder cannot explain what cash will look like after the hire starts.
That is not automatically a bookkeeping failure. It is a decision-making gap. Here is the question I would ask: do you need someone to record what happened, or a thinking partner who can challenge what you are about to do?
When a bookkeeper and outside CPA are no longer enough
A bookkeeper typically records transactions and reconciles accounts. An outside CPA may handle tax work, financial reporting or other services within the engagement. Neither title tells you whether someone owns your forward-looking operating decisions. Some CPAs provide that support; many tax engagements do not include it.
A CFO connects the numbers to choices: whether to hire, change pricing, borrow, conserve cash or pursue an acquisition. The Bureau of Labor Statistics describes financial management as including forecasts, supervision and advice to management. The point is not another report. It is a better decision.
I would look for a recurring unanswered question. Can we fund growth before customers pay? Which product actually supports the overhead? What happens if our largest customer leaves? If reliable books exist but nobody can turn them into usable answers, senior finance leadership may be the missing layer.
If the books are months behind, start with accounting capacity and close discipline. A controller may be the better next hire. A CFO can help design the repair, but do not quietly turn a strategic engagement into an expensive reconciliation service.
Fractional CFO vs Full-Time CFO: the practical comparison
A fractional CFO is a senior finance leader working part-time under an agreed scope, often across several clients. A full-time CFO is dedicated to one business, usually as an employee; in a typical U.S. employment arrangement, that means a W-2 role. Neither structure guarantees competence.
| Decision factor | Fractional CFO | Full-time CFO |
|---|---|---|
| Availability | Scheduled involvement with negotiated response times | Daily executive involvement, with coverage still needed for absences |
| Typical work | Cash forecasts, planning, lender reporting and defined strategic projects | Those responsibilities plus sustained leadership of the finance function |
| Team support | Needs a clear internal owner for work between sessions | Can directly build, coach and manage the finance team |
| Cost structure | Agreed fees plus any separately priced work or accounting support | Salary, employer costs, benefits and any bonus or equity |
| Main risk | Urgent needs exceed the contracted capacity | Hiring the wrong person or buying capacity before it is useful |
| Best-fit pattern | Important decisions that can be prepared and reviewed on a defined cadence | Continuous complexity and decisions requiring daily senior ownership |
Pick a fractional CFO if…
Pick a fractional CFO if you have dependable accounting, someone to execute follow-through, and a senior finance agenda that fits reserved time. That might mean building a cash forecast, preparing lender updates, testing an expansion plan or making the first credible board reporting packet.
Picture an agency with a capable accountant but no view of project profitability. A part-time finance leader could help connect staffing commitments, client collections and margins to the founder’s hiring decisions. The assignment is specific, and the team can keep it moving between reviews.
Not if…
Not if every day produces urgent decisions that cannot wait for the next available session. Do not assume a retainer buys unlimited access. Ask who responds during a cash emergency, what happens during a financing deadline, and how extra work is approved and charged.
I would also reject an engagement built around sending dashboards without discussing decisions. A beautiful packet can still leave the founder carrying every difficult judgment alone.
Pick a full-time CFO if…
Pick a full-time CFO if financial leadership is a daily operating responsibility: leading a growing team, negotiating financing, managing risk and working alongside other executives as plans change. The role needs enough authority and recurring substance to justify a dedicated seat.
A manufacturer juggling inventory purchases, lender reporting, several entities and an acquisition may need that continuity. The important signal is not its revenue badge. It is how many consequential decisions compete for attention and whether the finance function needs a leader throughout the week.
Not if…
Not if you mainly want the reassurance of a senior title. If accurate accounting and a regular planning conversation solve the problem, a permanent executive may be premature. A full-time CFO also needs access, cooperation and decision rights; payroll does not create those automatically.
Use complexity triggers, not a magic revenue threshold
I would map these pressures before comparing candidates. One trigger does not dictate the answer; several overlapping demands can change how much senior attention you need.
- Multiple entities: Consolidated reporting, intercompany balances and separate obligations need clear ownership. Ask who coordinates entity-specific accounting and specialist advice.
- Fundraising: Models, investor questions and diligence can overwhelm a light engagement. Test capacity against the actual timetable, not the promise of general fundraising support.
- Lender reporting: Covenant calculations and reporting deadlines need reliable inputs, review and an accountable owner. Read the loan requirements before defining the role.
- Inventory and working capital: Growth can tie up cash in stock and unpaid invoices before collections arrive. Finance needs to connect purchasing and sales plans to cash timing.
- Audit readiness: Records, reconciliations and controls need preparation. A CFO can coordinate readiness; an independent auditor performs the audit.
- Exit preparation: Buyers may question earnings quality, customer concentration and forecasts. Preparation is more useful when someone can explain the assumptions behind the files.
A bounded preparation project can suit fractional support. A sustained combination of these demands can support a full-time hire. If a temporary crisis requires daily leadership, consider an interim CFO: temporary does not necessarily mean part-time.
Make finance serve owner pay and business value
Here is where I would bring the conversation back to the founder. You can build a company that looks successful while still treating its bank balance like a personal spending limit. A finance leader should help separate operating commitments from owner compensation and distributions.
Understanding how to pay yourself as a business owner starts with separating your personal needs from the cash the company must retain to operate.
That means showing planned owner payments explicitly in the cash forecast, alongside payroll, supplier bills, debt service and reserves. It does not mean labeling every payment an owner draw. The correct treatment depends on your structure and circumstances; coordinate it with your CPA.
The same discipline matters when you learn how to value a small business, because a credible earnings story needs more than an optimistic number from the founder.
A CFO should help explain recurring profitability, unusual expenses and the cash required to sustain operations. That does not guarantee a higher sale price or replace an independent valuation. It makes your decisions less dependent on a story only you can tell.
Test the thinking partner before buying the title
I would give candidates a clearly hypothetical case: a large customer delays payment while the team wants to hire and the owner wants a distribution. Ask what information they need, which assumptions they would challenge and what choices they would put in front of you.
Listen for questions about timing, restrictions and alternatives, not instant certainty. Then ask for relevant experience with your business model and a sample reporting packet stripped of confidential information. A candidate who cannot explain their own model simply is unlikely to make yours useful.
Compare the complete operating setup, not a retainer against a salary. Include the accounting team both options require, onboarding, additional project work and emergency coverage. I would rather compare actual written scopes than repeat online price ranges that describe different jobs.
Write a first-90-days decision brief
Before signing, I would put five expectations on one page:
- Decisions: Name the hiring, pricing, cash or financing choices the role must improve.
- Inputs: Identify who closes the books and who updates the forecast.
- Cadence: Reserve review time and define urgent-response arrangements.
- Authority: Document approval limits, access permissions and independent checks.
- Handover: Keep models and documentation accessible to the company and define a review point.
At that review, ask what changed because the finance leader was involved. Did you adjust purchasing before cash tightened? Decline a bad financing offer? Separate a sensible owner payment from money needed for operations?
Those are useful outcomes. More slides are not. The right CFO arrangement gives your ambition something stronger than optimism to stand on: judgment you can use, at the moment your business needs it.
This article is general business education, not individualized financial, tax or legal advice. Use qualified advisers for your company’s specific obligations.
Frequently Asked Questions
Can a fractional CFO replace my bookkeeper or CPA?
Usually not. A fractional CFO adds planning and decision support, while bookkeeping and tax work still need clear owners. Some engagements bundle services, so confirm who maintains the records, handles filings and checks the work before signing.
At what revenue should I hire a full-time CFO?
There is no universal revenue threshold. Look at the frequency of consequential financial decisions, the team needing leadership and the complexity of financing and reporting. Similar-sized businesses can need very different levels of daily senior finance involvement.
Can a fractional CFO help raise investment?
Yes, a suitably experienced fractional CFO can help prepare forecasts, organize financial information and answer investor questions. Define the workload and availability before starting. Hiring finance support does not guarantee funding, investor introductions or an acceptable financing deal.
How do I know we have outgrown fractional support?
Look for recurring delays in important decisions, persistent work beyond the agreed scope and a finance team that lacks daily leadership. Review whether those needs are temporary or sustained before expanding the engagement or recruiting a full-time executive.
What should a CFO deliver besides dashboards?
A CFO should translate financial information into choices: how much cash to preserve, which commitments to make and what risks to address. Expect clear recommendations, explicit assumptions and follow-through. Every recurring report should support a decision someone actually owns.
Section 179 vs bonus depreciation comes down to one question: do you want to decide exactly how much equipment cost to deduct this year, or are you happy with the default? Section 179 is an election you make item by item, and it is capped by your business income. Bonus depreciation, which the IRS calls the special depreciation allowance, applies automatically to qualified property unless you elect out by class of property.
If this year is profitable and you want to fine-tune the number, Section 179 gives you the steering wheel. If you want the full first-year write-off with less paperwork, or your purchases are bigger than this year’s business income, bonus depreciation usually does the heavy lifting. Many owners end up using both, in a set order.
This Page Is About the Choice, Not the Basics
If you need the fundamentals first, including the 2026 caps, what qualifies, and what “placed in service” means, start with my full guide to the section 179 deduction and come back here. This page assumes you already have a real purchase in mind and want to know which path to take.
Because here’s what most founders miss in December. The question is rarely “Can I write this off?” For qualified equipment bought and placed in service this year, the answer is often yes either way. The real question is how much control do you want over when the deduction lands?
That’s a timing decision. And timing decisions are where good founders quietly win or lose a lot of money.
The Real Difference: Default Setting vs Deliberate Decision
Here’s the simplest way I can put it: bonus depreciation is what happens if you do nothing. Section 179 is what happens when you decide.
According to IRS Publication 946, P.L. 119-21, commonly known as the One Big Beautiful Bill Act, reinstated the 100% special depreciation allowance for certain qualified property acquired and placed in service after January 19, 2025. Pub 946 is direct about how it works: unless you elect out, you must take it. You can elect out for any class of property, but that election covers all property in that class placed in service during the tax year.
Section 179 runs the opposite way. Nothing happens until you elect it on Part I of Form 4562. When you do, Pub 946 says you can allocate the deduction among your qualifying items in any way you want within the limits, and you don’t have to claim the full amount.
One is a switch. The other is a dial.
Section 179 vs Bonus Depreciation at a Glance
This table is built around the decision, not the definitions. Rules are summarized from IRS Publication 946, the Instructions for Form 4562, and IRS Tax Topic 704, all checked on November 7, 2026.
| Decision factor | Section 179 | Bonus depreciation |
|---|---|---|
| Default setting | Off until you elect it on Form 4562, Part I | On for qualified property unless you elect out |
| How precise you can be | Item by item, and you choose the amount | Class by class; an election out covers the whole class for the year |
| Business income limit | Yes; disallowed cost carries to the next year | Pub 946 does not apply the Section 179 business income limit |
| When the date matters most | The year you place the property in service | 100% depends on property acquired and placed in service after Jan. 19, 2025 |
| Used equipment | Must be acquired by purchase, not from certain related people | Qualified property can be new or certain used property |
| Order of application | Applied first, reducing depreciable basis | Applied after any Section 179, before regular MACRS |
| Changing your mind | Form 4562 instructions allow revoking the election by amended return within the time allowed | Revoking an election out requires IRS consent |
| Selling the asset later | Recapture rules can apply | Gain is generally recaptured as ordinary income up to the allowance taken |
| Who it fits | Owners who want to size the deduction to the year | Owners who want the full write-off without picking item by item |
Pick Section 179 If… / Not If…
Pick Section 179 if:
- You had a solid year and want to deduct a specific amount, not every dollar you spent.
- You bought several assets and want to expense some now and depreciate others over time.
- You want the option to adjust the decision later through an amended return, inside the IRS window.
- Your state follows Section 179 more closely than bonus depreciation. Ask your CPA, because states may treat these rules differently from the federal return.
Not if:
- Your business income this year is thin. Section 179 can’t exceed the taxable income from businesses you actively conduct, so part of the deduction just waits for next year.
- Business use of the asset is 50% or less. Section 179 requires more than 50% business use in the year you place it in service.
- You want the simplest possible return and the full write-off anyway. In that case, the default may already do the job.
Pick Bonus Depreciation If… / Not If…
Pick bonus depreciation if:
- Your qualified purchases are larger than this year’s business income and you still want the first-year deduction.
- You want the full write-off on an entire class of assets without making item-by-item elections.
- You bought qualified used equipment and it meets the IRS rules for used property.
- Your CPA has modeled the year and a large deduction now beats spreading it out.
Not if:
- You expect next year’s income, and your tax rate, to be meaningfully higher. Taking everything now can spend a deduction at a low value.
- You acquired the property before January 20, 2025. Older, phased-down rules apply to that property, so the 100% number may not be yours.
- You want to deduct only part of one class of assets. Bonus is not a dial; for that, Section 179 or regular depreciation is usually the tool.
Thin-Profit Year vs Big Year: Two Founders, Two Answers
Picture a founder who runs a two-person design agency. Year one of the agency was lean. She upgrades both workstations and a server in October because the old machines were costing them hours every week. Her business income is modest, and next year looks much bigger because of two retainer clients she just signed.
For her, the automatic full write-off might not be the smartest version of the deduction. Section 179 lets her expense just enough to match this year, and her CPA might suggest depreciating the rest so it lands in the stronger years ahead. Or the CPA may suggest electing out of bonus for that class and using a precise Section 179 number instead. Either way, the point is she decides.
Now picture a founder who runs a specialty coffee roaster. It was a record year. He replaces a roaster that had been breaking down every few weeks and buys a used packaging line from an unrelated seller. Both were already planned. He doesn’t need precision; he needs the full deduction against a big year. Bonus depreciation may cover everything automatically, and his CPA can still layer Section 179 on top where it helps.
Same tax code. Opposite answers. The difference wasn’t the equipment. It was the year.
Here’s the rule I’d follow: decide which year you want the deduction to land in before you decide which tool to use.
Using Both: The Order the IRS Applies Them
This isn’t a pick-one-forever choice. The Instructions for Form 4562 describe the special depreciation allowance as an additional deduction you take after any Section 179 expense deduction and before you figure regular MACRS depreciation. Pub 946 says the same thing from the other side: any Section 179 deduction reduces the depreciable basis first.
So the sequence is:
- Section 179 on the items and amounts you choose.
- Bonus depreciation on the remaining basis of qualified property, unless you elected out of that class.
- Regular depreciation on whatever is left.
That order is why “Section 179 vs bonus depreciation” is really a question about who’s driving. If you don’t elect Section 179 and don’t elect out of bonus, the default can take the whole thing in year one. If you want a different outcome, you have to act on purpose.
Electing Out of Bonus: The Switch That’s Hard to Flip Back
This is the part I’d slow down on. Pub 946 says the election out is made by attaching a statement to your return naming the class of property. Generally it has to be on a timely filed return, including extensions. If you filed on time without it, there is a 6-month window to make it on an amended return.
Once you elect out for a class, Pub 946 says you can’t revoke it without IRS consent, and a request to revoke is a request for a letter ruling. That’s not a quick fix.
Compare that with Section 179. The Form 4562 instructions say a Section 179 election, or any specification in it, can be revoked without IRS approval by filing an amended return within the time prescribed by law for that tax year. Once made, the revocation itself is irrevocable.
That’s the control gap in one sentence: Section 179 lets you adjust the dial later. Electing out of bonus is a switch you should treat as permanent.
One more practical note. In a partnership or S corporation, Pub 946 says the election out is made separately by each person owning the qualified property, such as by the partnership or the S corporation itself. If you’re a co-owner, this decision may not be yours alone to make.
Questions to Bring to Your CPA Before December 31
This choice belongs in the same conversation as the other year-end tax moves a one-person business should run before the year closes. Walk in with these:
- What does our income look like this year versus what we expect next year?
- Which purchases were acquired and placed in service after January 19, 2025, and do we have the dates documented?
- Are any of these assets used property, or used partly for personal purposes?
- Should we let bonus apply by default, elect Section 179 on specific items, or elect out of a class entirely?
- How does our state treat each option?
- If we sell this asset in a few years, what does recapture look like?
Notice what’s not on the list: “What should I buy to lower my tax bill?” If the purchase doesn’t make sense without the deduction, the deduction doesn’t make it smart. It just makes it cheaper.
The Real Lesson
Most founders treat depreciation like a form to fill out. The smart ones treat it like a lever. Bonus depreciation is powerful because it’s automatic. Section 179 is powerful because it isn’t.
Buy what the business needs. Get it in service. Then decide, deliberately, which year that deduction should help. That’s the whole game.
This article is for education only and is not tax advice. Tax rules change, states may treat these rules differently from federal law, and your situation is unique. Talk to a qualified CPA before you make a purchase or a tax election based on anything here. Rules cited were checked on IRS.gov on November 7, 2026.
Frequently Asked Questions
Can I use Section 179 and bonus depreciation in the same year?
Yes. IRS instructions apply Section 179 first, which reduces the asset’s depreciable basis. Bonus depreciation then applies to the remaining basis of qualified property, and regular depreciation covers anything left. Many owners use both on different assets or even the same asset.
Does bonus depreciation apply automatically?
Yes. IRS Publication 946 says that unless you elect out, you must take the special depreciation allowance on qualified property. You can elect out by attaching a statement to your return for a class of property, which covers all property in that class for the year.
Which is better if my business has little taxable income this year?
Section 179 can’t exceed taxable income from businesses you actively conduct, so the excess carries forward. IRS Publication 946 doesn’t apply that limit to bonus depreciation. Whether a bigger deduction now helps depends on your loss rules and next year’s income, so model it with a CPA.
Can I undo an election out of bonus depreciation?
Not easily. IRS Publication 946 says revoking an election out requires IRS consent through a letter ruling request. A Section 179 election, by contrast, can generally be revoked by amended return within the time allowed. Treat electing out of bonus as a one-way decision.
Does the 100% bonus rate apply to everything I place in service this year?
No. IRS Publication 946 ties the 100% rate to certain qualified property acquired and placed in service after January 19, 2025. Property acquired earlier follows older, phased-down rules, and some property is excepted. Confirm acquisition dates with your CPA.

Why Hard Work Can’t Beat the Thermostat Effect

Why Deeper Connection Starts With Asking Permission

The 2026 Addicted2Success Quote Index: Who the World Turns to for Motivation

Why You Need More Than One Purpose

Why You’re Not Sabotaging Yourself
5 Ways For Startups To Succeed Making Acquisitions

77 Inspirational Quotes That Will Change Your Life
57 Memorable Kobe Bryant Quotes

Motivational Picture Quotes: 52 Images to Inspire a Successful Year
40 Rare Motivational and Inspirational Picture Quotes
3 Prince EA Videos To Change Humanities Path To Greatness
(Video) What Is Success? An Entrepreneurial Story To Inspire You
(Inspirational Video) What If Today You Knew You Were Going To Take Your Last Breath?
How To Make Enough Money From A Blog To Quit Your Job – Kate McKibbin
How Finding Your Passion And Becoming An Entrepreneur Can Lead To Happiness – Chiquita Searle
-

 Did You Know1 year ago
7 Surprising Life Lessons Video Games Taught Me That School Never Did
-
 Life2 years ago
The 5 Stages of a Quarter-Life Crisis & What You Can Do
-
 Success Advice1 year ago
Stephen Covey’s 8 Leadership Habits That Will Change How You Lead Forever
-

 Featured2 years ago
The Psychology of Motivation: How to Keep Moving Forward Every Day
-

 Life1 year ago
How to Stop the War in Your Head and Find Peace
-
 Personal Development2 years ago
The Three-Second Pause That Changes How People Perceive You
-
 Explode Your Social Media1 year ago
Want More Views? Master These 6 YouTube Growth Tactics
-
 Change Your Mindset1 year ago
You Become What You Absorb: How Input Shapes Your Life