Business Advice
I Built the Company With No Life Insurance. That Was Not Brave.

For a long stretch I had a company and nothing written down that would help anyone if I was gone.
I did not sit around deciding that. I just kept moving. There was always a launch, a hole in the week, a reason the forms could wait. Looking at term life felt like stopping in the middle of a job that already used up the nerve I had. So I did not look.
People around me would have been the ones left holding the rent and the brand and whatever mess was in the accounts. I called that focus. It was closer to not wanting to picture the week after.
I have sat at a table at night with the site open on one side and the ordinary life of the house on the other and still told myself this was not the night. The night was never going to feel like the right one. That is the trick. The business trains you to wait for a cleaner calendar. The calendar does not get cleaner. It just fills with more of the same heat.
The quote is what I was avoiding
Not dying. The ten minutes of questions.
Height. Smoke or not. A number that makes the worst day expensive in a boring, official way. I could sell. I could not sit still for that screen. It felt like inviting a subject I did not want in the room.
I kept saying after the next good month. After the next launch. After the account looked less embarrassing. The good months came and went. None of them arrived with a feeling that now it was safe to deal with dying. They just became more months with the same gap under them.
There is a pride version of this that sounds almost moral. You are the engine. Engines do not buy policies. Engines keep running. I have heard that in my own head. It is a nice sentence until you imagine the person who would have to keep the lights on with no check and a brand they did not ask to operate.
A spouse does not need your philosophy. They need a number that hits a bank account while they are still trying to figure out the passwords.
What I was protecting
The story that I was indispensable and also fine.
Those two ideas do not travel together. If the company needs you that badly, the household needs a policy that badly. If you are fine either way, you would have filled out the form on a Tuesday and forgotten it. I was not fine with the form. That should have been the tell.
I also did not want a premium I would have to see every month. Another line item next to hosting and ads. It felt like paying for a future I refused to rehearse. The rehearsal is the point. You pay a small, ugly amount so the ugly day does not take the house.
Founders are good at spending on tools that make them look busy. We are late to spend on the thing that only matters if we are not in the chair.
The comparison I still use
When somebody already has people who would be stuck, I send them to Policygenius.
I do not need a favorite carrier. I need quotes next to each other so the decision stops being a mood. Twenty years or thirty. Enough to cover the house and a stretch where the company would have to run without me in it.
Ethos will tell you they are faster. Ladder will tell you they are built for people who hate agents. Haven Life will keep it simple. Fabric will talk like a family brand. SelectQuote will get on the phone. If one of those is the only tab you will finish, finish it. I keep sending people here because I have watched founders open five windows, get tired, and close all of them. The unpaid year costs more than a slightly worse premium.
You can spend a Saturday becoming an amateur actuary. That Saturday is how the policy stays unbought.
An LLC does not fix this. You can have a clean name on the filing and still leave a spouse with letterhead and no check. The company paperwork and the policy are different jobs. Doing one and skipping the other is how you look official and stay exposed.
How big the number needs to be
Ugly enough that the month still works.
House. A few years of the business being slower because you are not in it. Kids if you have them. That is term. It is not a legacy speech. It is “if I get hit, they are not scrambling in week one.”
Whole life, riders, and a two-hour talk about permanent coverage can wait. Those conversations are how people stall inside a product they do not need yet. Term is the adult version. You can convert or add later if the life gets more complicated. First you need something in force.
You cannot pick that number off a feeling. You pick it off what the bills would actually do. If you have never looked at the household and the company as one stack of obligations, the death benefit will be a round number you liked the sound of. Round numbers that sound good are usually short.
I wanted the application to make me look like I had always been this responsible. It did not. It sat there. The first quote was higher than I wanted. That was information, not a sign I should wait another year. If they ask for a medical exam, do the exam. If they decline a piece of it, that is still a starting point.
The week you actually do it
Pick one comparison. Run the quote. Put a real beneficiary on it, not a blank you will “fix later.” Later is how policies get issued with the wrong person attached.
Tell the person who would have to use it that it exists. A policy nobody knows about is a scavenger hunt on the worst week of their life.
Then leave it alone. Do not reopen the tabs every time a headline talks about markets. Term is boring on purpose.
If you sell this
Policygenius is already named. You know why you are here.
Say something a founder who is scared of the form could use. A rate grid in the first paragraph will not go up. Neither will a speech about peace of mind. The reader is trying to stop leaving their family on the hook while they build. Help with that or stay off the domain.
I did not become a different man. I got a policy on the life the company was already using. That was the part I had been skipping. The business was real. I had been treating myself like I was optional.








An 83b election is a choice to include the value of restricted property, usually stock, in your gross income in the year it’s transferred to you, instead of waiting until it becomes substantially vested. You include the excess, if any, of the property’s fair market value at transfer over the amount you paid for it. The election has to be filed no later than 30 days after the transfer date, on IRS Form 15620 (Rev. 4-2025) or a written statement that meets the same requirements. There is no extension of that 30-day clock.
You’ll also hear it called a section 83b election or an 83b filing. Same election. If you make it, later appreciation generally is not treated as compensation when the shares vest. If you skip it, you include the spread at vesting, when the shares may be worth a lot more. This is education, not tax or legal advice, and it is not a reason to file automatically. Talk to a CPA or startup counsel before you sign anything.

When an 83b election even comes up
The election applies when substantially nonvested property is transferred to you in connection with performing services, as an employee or an independent contractor. In a startup, that usually means restricted common stock you receive as a founder or early hire, or shares you get by early-exercising options that are still subject to vesting.
It does not apply to the option itself. IRS Publication 525 (2025) is explicit: you can’t make this choice for a statutory or nonstatutory stock option. The choice is about the restricted stock (the property) once it’s been transferred to you. If you’re early-exercising incentive stock options, alternative minimum tax and the ISO holding-period rules can change the analysis. That’s a question for your CPA, not a shortcut in this article.
Vesting itself is a separate conversation from this filing. If you and a co-founder are still working out the founder equity split and the vesting schedule, settle that first. The 83b election is what you may need to file in the 30 days after those unvested shares actually transfer.
What you include in income if you file
Form 15620 walks through the math. You report the fair market value of the property at the time of transfer, determined without regard to lapse restrictions, minus the amount you paid. That difference, if any, goes into your gross income for the tax year that includes the transfer date.
Here’s a simple teaching example, with made-up numbers. You receive 1,000,000 shares of restricted common stock. You pay $0.0001 a share, or $100 total. A recent independent appraisal puts fair market value at $0.001 a share, or $1,000. If you file a timely 83b election, you include $900 in income ($1,000 minus $100). If the company later succeeds and those shares are worth much more when they vest, that later appreciation is not included as compensation at vesting. Your basis for a later sale is what you paid plus what you included as compensation, according to Publication 525.
Fair market value is not a guess you jot in a notebook. For private company stock, it often comes from a 409A valuation. Use the value your counsel or CPA tells you belongs on the form, and describe the shares and the vesting restrictions clearly. Form 15620 asks for the quantity, the transfer date, the tax year, the restrictions, the value, the amount paid and the income to include.
The 30-day deadline is the whole game
Form 15620 says the election must be filed no later than 30 days after the date the property was transferred. If the 30th day falls on a Saturday, Sunday or legal holiday, IRC section 7503 lets you treat it as timely if it’s postmarked by the next day that is not a Saturday, Sunday or legal holiday. That’s the only flexibility the form’s instructions give you.
There is no “I’ll catch it on next year’s return” version of this. A late 83b election is generally not an 83b election. If the transfer already happened, count the days today. If the transfer hasn’t happened yet, build the filing into the closing checklist so you’re not starting the clock and then looking for a form.
How to file Form 15620
Publication 525 for 2025 says you can make the choice by filing a written statement or Form 15620 with the Internal Revenue Service Center where you file your return, no later than 30 days after the transfer. The Form 15620 instructions (Rev. 4-2025) describe mailing a completed, signed form to the IRS office where you file your federal income tax return. A written statement that satisfies Treasury Regulation section 1.83-2 is still an alternative.
The IRS has also published Form 15620 as a form you can complete on IRS.gov. Before you file, check the current Form 15620 page and Publication 525 for the submission method that applies to you, including any online option. Don’t send the same election twice. Keep proof that you filed on time, whether that’s a mailing receipt or an online confirmation.
A copy still has to go to the company (the person for whom you performed the services). If you and the transferee of the property are not the same person, a copy has to go to the transferee too. The form itself includes an agreement to provide those copies. Keep a signed copy for your own records. Filing with the IRS is not the same as telling payroll or your cap table administrator.
What happens if you miss the deadline
If you don’t make a timely election, the default rule in Publication 525 applies. You generally don’t include the value in income at transfer. When the property becomes substantially vested, you include its fair market value at that time, minus any amount you paid, as compensation. Your holding period, under that default rule, begins when the property becomes substantially vested.
Go back to the teaching example. If you never file, and four years later 1,000,000 shares vest when they’re worth $1 a share, the spread that can show up as compensation is $1,000,000 minus the $100 you paid. That’s a different outcome from including $900 in the year of transfer. Whether filing would have been smart depends on the real value at transfer, the risk that you’ll forfeit the shares, and your tax situation. It is not automatically “file, always.”
What happens if you file and later forfeit the shares
This is the risk people skip past. An 83b election may not be revoked except with IRS consent. Publication 525 says consent will be given only if you were under a mistake of fact as to the underlying transaction. Changing your mind, or leaving the company, is not that.
If you forfeit the property after you’ve already included its value in income, Publication 525 says your loss is the amount you paid for the property minus any amount you realized on the forfeiture. In plain terms, you generally don’t get back the compensation income you already included. If you paid little or nothing for the shares and you get nothing back when you leave, there may be no loss to claim. Form 15620 points to Treasury Regulation section 1.83-2(f) and Revenue Procedure 2006-31 for revocation guidance, and section 83b(1) is the statute behind the forfeiture rule.
That’s why “the shares are cheap today” is not, by itself, a complete reason to file. Cheap shares and a high chance you’ll be gone before they vest can still produce a tax bill you can’t recover. Walk through both sides with a CPA.
What to do in the first 30 days
If restricted stock has just been transferred to you, or is about to be, do this in order:
- Confirm the transfer date and start counting 30 days from that date, not from the day you remembered to deal with it.
- Get the facts for the form: share class and quantity, restrictions, amount paid, and fair market value at transfer.
- Sit down with a CPA or counsel before you file, especially if the value isn’t tiny, you might leave, or ISOs are involved.
- File Form 15620 or a valid written statement on time, then give the required copies to the company (and the transferee, if that’s someone else) and keep proof.
I’m not your tax advisor, and this isn’t advice for your return. The sources for the rules in this article are Form 15620 (Rev. 4-2025) and Publication 525 (2025). Use them with a professional who can apply them to your grant, your filing status and your state.
Frequently asked questions
What is an 83b election?
An 83b election is a choice to include restricted property in your income at transfer, equal to fair market value minus what you paid, instead of waiting until the property becomes substantially vested.
How long do I have to file an 83b election?
You must file no later than 30 days after the property is transferred. If day 30 is a Saturday, Sunday or legal holiday, the Form 15620 instructions treat it as timely if it’s postmarked by the next business day. There is no general extension.
What form do I use for an 83b election?
IRS Form 15620, Section 83b Election (Rev. 4-2025), or a written statement that satisfies Treasury Regulation section 1.83-2. Publication 525 says either can be filed with the IRS service center where you file your return.
What happens if I miss the 83b deadline?
A late election generally doesn’t count. You then follow the default rule and include the fair market value minus what you paid as compensation when the property becomes substantially vested, which can be a much larger number.
Can I revoke an 83b election if I leave the company?
No, not on your own. The election can’t be revoked without IRS consent, and Publication 525 says consent is given only for a mistake of fact as to the underlying transaction.
Do I get a loss if I filed an 83b election and later forfeit the shares?
Usually not for the income you already included. Publication 525 says your loss is the amount you paid minus any amount you realized on the forfeiture, which can be zero if you paid little or nothing.
A cap table explained simply is a ledger of who owns the company, in what form, and what their ownership looks like if every promised share actually existed. “How to read a cap table” means looking past the issued-share column and checking fully diluted ownership: outstanding common and preferred, granted options, the unallocated option pool, and a model for unconverted SAFEs or notes. That fully diluted percentage is the number that usually matters before you take the next round.
You’ll also hear it called a capitalization table, a cap table, or a fully diluted ownership schedule. Same document. If you only look at the shares already issued, you will feel richer than you are. The dilution is already sitting in the other rows.

What a cap table is actually showing you
At a minimum, a cap table lists each holder, the kind of security they have, the number of shares or share equivalents, and their percentage of the company. The two percentage columns that matter are issued (sometimes called outstanding) and fully diluted.
Issued ownership is shares that already exist, divided by shares that already exist. Fully diluted ownership is a holder’s shares, plus anything they’re treated as owning on an as-converted or as-exercised basis, divided by a larger denominator: all those issued shares, plus options and warrants, plus the unallocated option pool, plus, if you’re doing this honestly, a conversion model for open SAFEs and convertible notes.
Preferred stock is usually shown on an as-converted-to-common basis, because that’s how it counts in an ownership discussion. You don’t need to memorize every preferred right to read the ownership math. You do need to know which denominator someone is using when they quote a percentage.
Issued vs fully diluted: the first number founders misread
Here’s a teaching example with made-up round numbers. Two co-founders and a small option pool:
| Holder | Shares | Issued % | Fully diluted % |
|---|---|---|---|
| Founder A (common) | 8,500,000 | 89.5% | 85.0% |
| Founder B (common) | 1,000,000 | 10.5% | 10.0% |
| Option pool (unallocated) | 500,000 | n/a | 5.0% |
| Total issued | 9,500,000 | 100% | |
| Total fully diluted | 10,000,000 | 100% |
Founder A can look at the issued column and think they own almost 90%. On a fully diluted basis, they own 85%, because the 500,000 reserved but unissued option pool already sits in the denominator. The pool is not a rumor. It’s part of the company you’ve already promised to the future hiring plan.
If 200,000 of those pool shares had already been granted to an early hire, the issued column would change and the fully diluted total would not. Granted or unallocated, those pool shares belong in the fully diluted picture. That’s the first reading habit to build.
The option pool: always ask which denominator
People throw around “a 10% pool” as if everyone means the same thing. They don’t. Ten percent of current fully diluted shares is not the same as ten percent of the company after a new round closes. A term sheet that says the pool will be “refreshed to 10%” is unfinished until it says 10% of what, and whether that increase happens before or after the new money is counted.
There is no official standard size. I’ve seen term sheets ask for different pool figures in different deals, and anyone who tells you “it’s always 10%” or “always 15%” is repeating a habit, not a rule. The job is to get the percentage, the denominator and the timing in writing, then model what that does to your shares.
A pre-money pool refresh is the version that catches founders. The investor wants the pool topped up so that, after they invest, the pool is a set percentage of the post-money company, but the new pool shares are treated as outstanding before their money comes in. Existing holders, mostly founders and early employees, absorb that increase. The new investor does not.
Unconverted SAFEs and notes belong in the picture
A SAFE or convertible note is not a row of shares until it converts. If your cap table software only shows issued stock, that paper can be invisible, which is how founders walk into a priced round thinking they own 60% and walk out owning a lot less than the new money alone would explain.
You don’t have to turn this page into a lesson on the instrument. If you need the difference between the two, that’s the SAFE vs convertible note article. What you do need, when you read a cap table, is a conversion model for every open SAFE and note: the cap, the discount if there is one, and a clear assumption about how it converts in the next priced round.
A simple illustration, again with teaching numbers. A post-money SAFE for $1 million on a $10 million post-money cap is designed to deliver about 10% ownership at conversion. If you ignore it, Founder A’s 85% in the table above looks stable. If you model that 10%, existing holders are sharing a smaller pie before a venture round even shows up. The exact share count depends on the documents and the round, so treat this as a warning light, not a closing spreadsheet. Get the conversion modeled before you quote your percentage to anyone.
What a priced round plus a pre-money pool refresh does to your percentage
This is the math I want every founder to run before they get excited about a term sheet.
Keep the same starting company: Founder A 8,500,000, Founder B 1,000,000, unallocated pool 500,000, fully diluted 10,000,000. A new investor offers $2 million at an $8 million pre-money valuation, which is a $10 million post-money valuation, so they’re buying 20% of the company after the close. The term sheet also says the option pool must be 10% of the fully diluted post-money cap table, and the increase is required on a pre-money basis. These are teaching terms, not a recommendation.
Without any pool refresh, the fully diluted total after the round would be 12,500,000 shares. The new investor would hold 20%, the old pool would shrink to 4%, and Founder A would go from 85% to 68%.
With the pre-money refresh to a 10% post-money pool, the fully diluted total rises to about 13,571,429 shares. The new investor still holds 20%. The pool becomes 10%. Founder A lands at about 62.6%.
| Before the round | After, no pool refresh | After, pre-money refresh to 10% | |
|---|---|---|---|
| Founder A | 85.0% | 68.0% | 62.6% |
| Founder B | 10.0% | 8.0% | 7.4% |
| Option pool | 5.0% | 4.0% | 10.0% |
| New investor | n/a | 20.0% | 20.0% |
The new money cost Founder A 17 points. The pool refresh cost another 5 points, and none of those 5 points went to the new investor. If you only heard “we’re selling 20%,” you missed it. That’s why you read the cap table, and the term sheet’s pool language, together.
What to check before the next round
The starting common split is a different job. If you and a co-founder are still deciding the founder equity split, settle that first. The cap table is what happens after those shares exist, when later promises start stacking on top of them.
Before you negotiate or sign, work through this list:
- Recompute your percentage on a fully diluted basis, including the unallocated pool, not just issued shares.
- List every open SAFE, note, warrant and promised grant, and model the conversion or issuance, even if it hasn’t happened yet.
- Read the pool language in the term sheet. What percentage, of which denominator, and is the refresh pre-money or post-money?
- Rebuild the post-round cap table yourself (a spreadsheet is enough) and compare it to whoever sent you the model.
- Don’t treat a hanging promise as a footnote. An offer letter, an advisor grant or a convertible that “we’ll clean up later” is already in the fully diluted story.
This is education, not legal advice, and it’s not a reason to pick any particular cap table product. If the round is real, have startup counsel or an experienced advisor model the close with you before you sign. The point of learning to read the cap table is so you can see the dilution coming, while you still have a chance to negotiate it.
Frequently asked questions
What is a cap table?
A cap table, or capitalization table, is the company’s ownership ledger. It lists each holder, the security they own, the share count and their percentage, on both an issued and a fully diluted basis.
What does fully diluted ownership mean?
Fully diluted ownership is your shares divided by all shares that would exist if options, the unallocated pool, warrants and converted SAFEs or notes were counted. It is usually lower than your issued percentage.
Does the unallocated option pool dilute founders?
Yes, on a fully diluted basis. Reserved but unissued pool shares sit in the denominator, so they reduce founder percentages even before those options are granted or exercised.
How do SAFEs show up on a cap table?
A SAFE is not shares until it converts. You should still model it, using the cap and any discount, so your fully diluted percentage includes the ownership that SAFE is expected to deliver in the next priced round.
What is a pre-money option pool refresh?
It’s a term-sheet requirement that the option pool be increased, usually to a stated percent of the post-money company, with that increase treated as happening before the new money comes in, so existing holders, not the new investor, take the dilution.
How do I read a cap table before a priced round?
Start with fully diluted ownership, add a conversion model for every SAFE or note, then rebuild the post-round table using the term sheet’s valuation and pool language. Compare your model with the investor’s before you sign.
What do investors look for? A founder who genuinely believes every word of the pitch, a story that hits the problem in the first minute, a team that can actually execute, and a clear answer to where every dollar goes. Kevin Harrington, an original shark on Shark Tank, says the passion gets you in the room, but the team and the use of proceeds get you the check.
Kevin has taken thousands of pitches. His official bio credits him with creating the infomercial, pioneering the As Seen on TV brand, launching more than 500 products that produced well over $5 billion in global sales, and building 20 companies that each topped $100 million in revenue.
I wanted the inside advice a lot of entrepreneurs need right now. How do you approach investors, and what really matters when you’re presenting your business idea? Here’s what he told me.
What investors look for in the first 10 seconds
Before you’ve said anything useful, Kevin is already doing what he calls the old 10-second look. How confident are you? How do you present yourself? Are you delivering this in a powerful, passionate way?
Most of all, he wants to know you believe the words coming out of your mouth. “Too many people, someone’s written them a script.” He wants the real deal, not someone reciting a deck they didn’t build.
How to pitch to investors: tease, solve, seize
At one pitch contest, founders had eight minutes each. One guy took seven minutes to even mention his product. Kevin had to tell him straight: if you’re taking eight minutes of all these valuable people’s time, learn to deliver a reasonably good pitch. “You lost us.”
His structure is simple, and he slowed down to make sure I got it:
- Tease. Open with an attention-getting problem.
- Solve. Show how you solve it, with demonstrations, “magical transformations,” testimonials and documentation, plus a little competitive analysis.
- Seize. Close with an irresistible offer.
Kevin points out he hears pitches for a living, but most people you pitch don’t. If you don’t grab their attention with the problem first, you’re probably not going to land, “especially if you’re looking for money.”
Why investors stopped betting on the jockey
I asked Kevin whether he’d ever backed someone on attitude alone. Somebody who walks in with so much certainty that you just want to work with them. His answer surprised me. Not anymore.
He used to bet on the jockey, the entrepreneur. He’s been let down too many times. Plenty of gung-ho founders with all the passion in the world have driven a business into the ground because they couldn’t execute. Maybe they had one skill set, but no finance or operations, and they never surrounded themselves with people who did.
The person, their passion and their belief still weigh very heavily. But if someone wants half a million dollars, Kevin wants to see the right structure, the right team and the right expertise behind them first. “I’ve seen entrepreneurs run through the money real quick and say, ‘Well, sorry, we just didn’t make it.'”
Tony Robbins once told me your business will eat as much money as you throw at it. Kevin agreed. That’s exactly why investors want counterbalances around a passionate founder.
Use of proceeds: the question that kills deals
One of the big questions on Shark Tank was always: what’s the use of proceeds? In plain English, if I write you the check, where does the money go?
Kevin told me about a founder who wanted a quarter of a million dollars. The plan was a down payment on a building, office furniture, a copy machine and printers. That was the whole $250,000. Kevin was out. Where was the marketing plan? The rainy day fund? The budget for public relations, advertising or a launch? “You can tell pretty quickly that they really haven’t thought out how they’re gonna really launch this business.”
A good operations or finance person makes you think through the cost of hiring and the cost of weathering the opening months of cash flow, because cash flow doesn’t come out of the box. It builds.
Then there’s the office. Kevin once visited a company with about five employees in 7,000 square feet of expensive space, complete with a ping pong table and a Skee-Ball machine. “You don’t need a ping pong table until you become Facebook.” I see so many people trying to pimp out their office space. Get the profits coming in first, then deck it out later.
Same goes for the funding announcement. A lot of people celebrate millions in investment, money that isn’t theirs, without a plan for it. Kevin’s point: nobody wants to give you $5 million that’s supposed to last 18 months and see you back in six or eight months asking for more. Unless your numbers have changed dramatically, that second round gets very hard.
Get investor-ready before you ask
Kevin’s biggest early mistake was being a young, cocky entrepreneur who thought he could do it all himself. He started with $25,000 and assumed that once he was successful, people would throw money at him. It doesn’t work like that. He ran out of capital.
So he hired a former bank president who knew how to raise money. The first thing that man asked was, “Where’s your contract file?” Kevin didn’t have one. With 30 products on air and eight or ten contracts per deal, writers, producers, directors, hosts and inventors, they had 300-plus contracts scattered everywhere. A lender wants to see every one of them, and wants to know there are no contingent liabilities like possible lawsuits waiting out there.
They spent 90 days getting ready before they asked anyone for money. Then they raised $3 million, which Kevin says gave them enough capital to grow to $100 million in sales. Whether you’re raising on a SAFE, a convertible note or a priced round, the diligence starts the same way: show me what you’ve signed.
My takeaway? Ignorance isn’t always bliss. And if you don’t have a strength in a certain area, find someone who does. It’s the lesson almost every first-time founder learns the expensive way.
Bring in experts whose track record helps you raise
When Kevin launched a beauty business with the model Kathy Ireland, he admitted beauty wasn’t his world. He does gadgets, fitness and kitchen products. So he brought in an executive who had spent a decade running a major beauty company, first as a consultant and then as president and COO.
That hire did two jobs. The company got real expertise, and Kevin used the executive’s resume to go out and raise capital for the new venture. The right people help you run the business, and they help you get the right money to grow it.
Prove it before you bring investors in
Kevin likes being first to market, but he’s honest that pioneering is riskier. As an investor, he prefers to get in when something is safer and more proven. As an entrepreneur, he expects to fail more than he succeeds, so he tries to fail fast and fail cheap, then get to the big winner.
That’s why he’ll often keep 100% ownership of a new idea until he’s proven it, and only then bring in investors if he needs to raise big money. “I don’t have to write every check, but I’ve proven it out now, so it’s a little safer investment.” To me that’s calculated risk, the same way Richard Branson likes to negotiate the downside before he jumps.
And proof is exactly what investors are looking for. For every company of his that hit $100 million, Kevin says, two or three didn’t succeed. I love that he said it out loud, because it gives people permission to be okay with failing on the way to a win.
Run a dollars-per-minute check on your day
One more habit worth stealing: how you spend your time. Kevin learned it from Home Shopping Network, which schedules tomorrow’s airtime based on today’s sales per minute. If a product was expected to do $2,000 a minute and did $1,000, they’re not happy, and the schedule changes.
He runs his day the same way. If he’s got three things he could do in the next hour, which one has the highest profit potential for the time? Some people waste half their day on things that generate no revenue, then wonder why they’re out of cash. My view: a founder who manages minutes like that will probably manage an investor’s money the same way.
What investors look for: a pre-pitch checklist
- Can you say the problem in your first 30 seconds?
- Do you have a demo, a transformation or a testimonial that proves you solve it?
- Is there a clear, irresistible offer at the end?
- Who on your team covers finance and operations?
- Can you show line by line where every dollar goes, including marketing and cash flow?
- Are all your contracts in one file, with no surprise liabilities?
- What have you already proven with your own money?
Kevin closed with a quote from Paul J. Meyer that he lives by: “Whatever you vividly imagine, ardently desire, sincerely believe, and enthusiastically act upon, must inevitably come to pass.” I’d add one thing. Knowing what investors want won’t get you funded. Walking in with every answer on this list will.
FAQ
What do investors look for in a startup?
A confident founder who believes in the idea, a team that covers finance and operations, proof the product works, and a clear plan for the money. Shark Tank investor Kevin Harrington says passion alone no longer gets his check without the team to execute.
What do investors look for in a pitch?
Kevin Harrington wants a tease, solve, seize structure: open with an attention-getting problem, solve it with demonstrations, testimonials and competitive analysis, then close with an irresistible offer. Don’t wait seven minutes to say what the product is.
What does use of proceeds mean?
Use of proceeds is exactly where an investor’s money will be spent. Investors want it tied to your business and marketing plan, with room for marketing, hiring and early cash flow, not just buildings, furniture and equipment.
Why do investors bet on the team, not just the founder?
Passionate founders without finance or operations support often burn through capital before the business works. Harrington says he’s been let down too many times betting on the jockey alone, so he backs founders surrounded by people who can execute.
How do you prepare your business to raise money?
Organize every contract in one file, clear up possible liabilities, build a use-of-proceeds plan and bring in experienced help. Harrington’s company spent 90 days getting ready before raising $3 million.
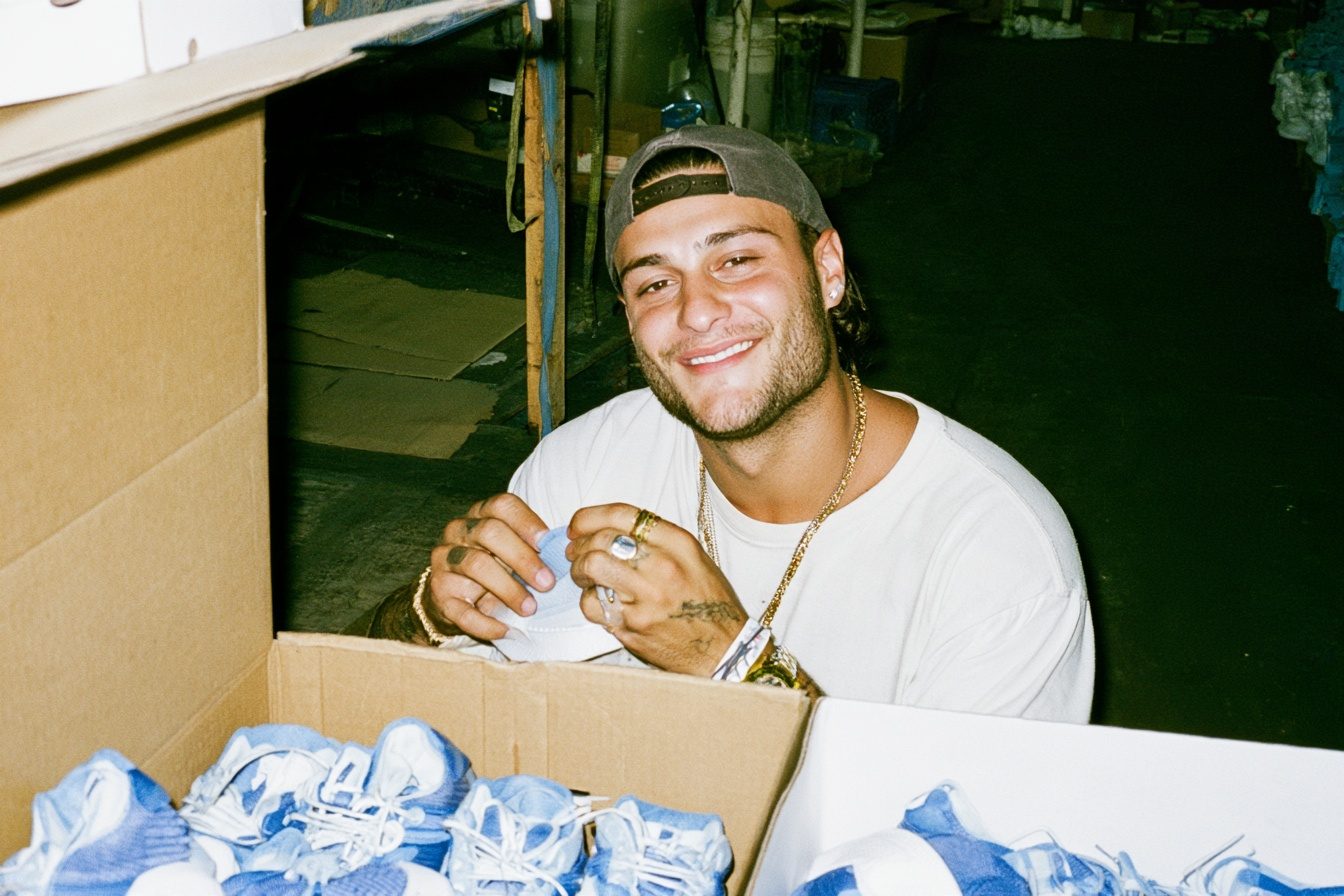
How to build a brand from scratch starts with a blunt question every buyer will ask you: why do I need you? Answer it by going straight to the end customer, earning proof from someone your market already trusts, and treating every no as information. That’s how Joe Foster took Reebok from a secondhand-machinery shoe shop to the world’s biggest sports footwear company, by his account.

Joe co-founded Reebok with his brother Jeff in 1958, and the family’s shoemaking goes back to their grandfather, who pioneered the spiked running shoe in 1895, according to Joe’s official site. His grandfather’s shoes were on the feet of Harold Abrahams, Eric Liddell and Lord Burghley, the athletes immortalized in Chariots of Fire.
A lot of people see the glory, but they don’t hear the story. Most guests give me tip number one, strategy two, principle three. Joe gave me the journey, and the lessons are all through it.
Start by refusing to let the business plateau
Reebok exists because the family company was dying. Joe’s father and uncle had inherited a world-class business and just kept it ticking over. No marketing. No plan. They fought more than they talked. “You need to drive a business forward. It can’t plateau. It will go down if you don’t drive it forward.”
Joe told his dad they had to change. His father’s answer was that when he and Uncle Bill were gone, the company would be theirs to run however they liked. Joe’s reply: “Dad, firstly, we don’t want you to go. But secondly, this business will be gone long before you.” After three years of trying to persuade him, Joe and Jeff walked out and started their own company.
Bootstrap the first version
They didn’t have investors. Before they left, they took evening classes in shoemaking, made friends in the trade and picked up advice. That network let them buy secondhand machinery, which was cheap once the industry’s technology moved on. Joe laughs that even their old machinery was newer than what the family firm had.
If you want to bootstrap a brand, that’s the lesson. Learn the craft, build relationships before you need them, and start with the gear you can afford. They called the company Mercury Sports Footwear and started making money.
Pick a name you can actually own
Eighteen months in, their accountant told Joe to register the name before someone else used it. Too late. A big shoe company had already registered Mercury and would sell it to them for 1,000 pounds. For two brothers who were barely afloat, that was impossible.
The trademark agent said bring me 10 names, not one, so we can test them all at once. Joe went to the Webster’s Dictionary he’d won in a running race as an eight-year-old. He liked the letter R because it felt like a strong start to a word. In the R section he found Reebok, a small South African antelope. Two syllables, strong, and it fit a running shoe company. He put Reebok at the top of the list and told the agent, “We’ve gotta be in love with this. It’s gotta be our passion.”
It was the only name on the list that came back free. Even then it went into part B of the register, because it was an animal’s name. Twenty years later the registrar moved it to part A, because by then everybody knew Reebok was a shoe, not an animal.
Answer the question “Why do I need you?”
This is the part I’d tattoo on every new founder. Joe would walk into sports stores with a bag of shoes and say, “I’m Reebok.” The store owner would say, “Reebok? Who?” Then, “I’ve got Adidas, and I’ve got Dunlop. Why do I need Reebok?”
Joe’s honest answer to himself: you don’t. Their shelves were full. So he realized he was selling to the wrong person. “I should be really selling my shoes to the athlete.” The retailer was just somewhere in between.
The UK’s Amateur Athletic Association had a handbook listing three or four hundred affiliated clubs, with the name and address of every club secretary. Joe wrote to them. He offered a 15% discount from retail, which a club member could keep as an agent or put toward club funds. He got a lot of agents and sold a lot of shoes.
Then the retailers started calling him, asking him to stop selling direct so they’d stock Reebok. He said no, he’d keep selling to clubs, but they could have it at wholesale. Joe says 60 to 70% of them started stocking the shoes anyway. Going direct raised the bar for the brand. “Our brand suddenly became a desirable brand.” Reebok stopped being just another name on a shoe.
What I love here is that Joe moved close to the heartbeat of the market. He went and found the people with influence instead of waiting for permission from the middleman.
Go where your brand can win, then keep showing up
Joe was honest that some doors were already closed. His grandfather once supplied 96 football and rugby clubs, but by the time Reebok started, Adidas owned football. Too expensive and too big to fight. So he looked at America, where every college had a running coach and athletics could get you into university.
His first trip to the big U.S. sporting goods trade show was 1968. People liked the shoes and asked where to buy them. “England.” “Is that New England?” Nobody wanted the hassle of importing. They’d try it when he had a U.S. distributor.
He went every year. He didn’t land his distributor until 1979. “That’s 11 years.” In that time he had at least six failed attempts with different partners.
Earn proof that someone else hands out
The break came from a magazine. Runner’s World was the bible of the U.S. running boom, and it ranked shoes. A number one ranking created demand nobody could supply, so the magazine moved to a star rating, with five stars at the top. Joe saw the opening immediately. “We’re a running company. What we need now is a five-star shoe.”
He designed the Aztec specifically to earn five stars. Kmart wanted 25,000 pairs, but Joe wanted a real distributor. Paul Fireman, who ran a small Boston outdoor goods distributor, was keen, but only if Reebok had a five-star shoe. Joe couldn’t guarantee it. When the shoe issue came out, he called Paul at 7am Boston time and told him to get to the kiosk. The Aztec got five stars. So did the Midas and the Inca. “That was our entry. That was the difference. That was the hook.”
For a new brand, borrowed trust beats anything you can say about yourself. Find the rating, the award, the review or the expert your buyers already believe, and build the product to win it.
Listen to the people closest to the customer
The move that made Reebok huge didn’t come from Joe. Arnold Martinez, a tech rep in Los Angeles, saw his wife coming home buzzing from aerobics classes. He went along and saw instructors and students in running shoes, plimsolls or bare feet. His idea: a soft glove-leather shoe with a cushioned sole.
Paul said no. Running was booming, so why play around with shoes for a dance class? Arnold didn’t take no. He went round the back to the production people and talked them into making 200 pairs, then handed them to instructors. Reebok suddenly became a fitness brand. Jane Fonda wore them in her workout videos. Sigourney Weaver wore Reebok high-tops. The competition called it a phase.
That phase took Reebok from $9 million to $30 million, $90 million, $300 million and then $900 million in successive years, Joe told me. By the time he retired, he says, Reebok was doing $3.8 billion and had overtaken both Adidas and Nike as the number one sports footwear company in the world. Timing helped too. Nike had hit a wall, so Reebok could fill factories in the Far East.
Treat every no as a learning curve
When I asked Joe what aspiring entrepreneurs need to get their head around, he went straight to the nos. “No is not an answer. No is only just a little hiccup on the way. No is something to get round.” Every problem means you’re learning something else. When retailers wouldn’t take him, it forced him to find another way to the customer, and that made the brand stronger.
If you’ve ever let rejection stop you, think about this. Someone once asked me: if you knew for sure all you needed was 10,000 nos to make a billion dollars, would you do it? Most people would say yes, because they’d know a yes was coming. Joe’s version is just as blunt. “An entrepreneur is another name for a risk-taker, because if it’s certain, everybody will do it.” His advice when people ask whether they should go for something? “Just go for it, because you’ll only regret it if you don’t. And if you fail, so what? Get up. Go on again.”
Know who’s the visionary and who’s the integrator
Jeff loved being in the factory and making the shoes. Joe did everything else: design, marketing, sales and all the travel. Joe was the visionary and Jeff was the integrator, and they played strength for strength.
That partnership got tested at the worst moment. Just as the five-star breakthrough hit and the volume problems started, Jeff got sick with stomach cancer and died very quickly. Joe had to do the Far East trip himself and bring in other people to run the factory. They got through it. Know your role, but build a team that can carry the business when life hits.
How to build a brand from scratch: the Reebok checklist
- Write down the honest answer to “Why do I need you?” before a buyer asks.
- Find a direct line to your end customer, the way Joe used the club secretaries list.
- Register a name you love and can own, early.
- Pick a market where the giants haven’t locked the door.
- Identify the rating, review or expert your buyers trust, and build to win it.
- Give your reps and front-line people a way to test ideas small, like 200 pairs.
- Count your nos as lessons, and keep showing up.
Joe’s parting advice was three words repeated: “Enjoy life. Have fun, fun, and fun.” I’d add one thing. Knowing his story won’t build your brand. Writing those letters, making that call and showing up for the eleventh year will.
FAQ
How do you build a brand from scratch?
Start with a clear answer to why customers need you, then reach your end customer directly, earn trusted third-party proof and keep testing. Reebok co-founder Joe Foster sold to running clubs, built a shoe to win five stars and treated every rejection as a lesson.
How did Reebok get its name?
The brothers’ first name, Mercury, was already registered. Joe Foster searched a Webster’s Dictionary he won in a childhood race and found the reebok, a small South African antelope. It was the only name on his list of 10 that was free to register.
Who founded Reebok?
Brothers Joe and Jeff Foster founded the company in 1958 as Mercury Sports Footwear and renamed it Reebok soon after. Their grandfather, Joseph William Foster, pioneered the spiked running shoe in 1895, according to Joe’s official site.
How do you get retailers to stock a new brand?
Create demand they can’t ignore. Joe Foster sold directly to athletic clubs at a 15% discount, and once customers wanted the shoes, he says 60 to 70% of the retailers who had passed started stocking them at wholesale.
How long does it take to build a brand?
Often longer than founders expect. Joe Foster went to the U.S. trade show every year for 11 years and had at least six failed partnerships before landing a U.S. distributor, then the brand’s growth accelerated quickly.

42 Motivational Quotes for Work to Fuel Your Team and Your Career

40 Quotes About Change to Help You Grow, Adapt and Start Again

The $2,000 1099 Threshold: When You Actually Have to Send a 1099-NEC

The 83b Election: The 30-Day Filing That Decides What You Owe on Your Shares

How to Build Business Credit From Zero: EIN, D-U-N-S and Tradelines That Report
5 Ways For Startups To Succeed Making Acquisitions

77 Inspirational Quotes That Will Change Your Life

57 Memorable Kobe Bryant Quotes

Motivational Picture Quotes: 52 Images to Inspire a Successful Year
40 Rare Motivational and Inspirational Picture Quotes
3 Prince EA Videos To Change Humanities Path To Greatness
(Video) What Is Success? An Entrepreneurial Story To Inspire You
(Inspirational Video) What If Today You Knew You Were Going To Take Your Last Breath?
How To Make Enough Money From A Blog To Quit Your Job – Kate McKibbin
How Finding Your Passion And Becoming An Entrepreneur Can Lead To Happiness – Chiquita Searle
-

 Did You Know1 year ago
7 Surprising Life Lessons Video Games Taught Me That School Never Did
-
 Life2 years ago
The 5 Stages of a Quarter-Life Crisis & What You Can Do
-
 Success Advice1 year ago
Stephen Covey’s 8 Leadership Habits That Will Change How You Lead Forever
-

 Life1 year ago
How to Stop the War in Your Head and Find Peace
-

 Featured2 years ago
The Psychology of Motivation: How to Keep Moving Forward Every Day
-
 Personal Development2 years ago
The Three-Second Pause That Changes How People Perceive You
-
 Explode Your Social Media1 year ago
Want More Views? Master These 6 YouTube Growth Tactics
-
 Change Your Mindset1 year ago
You Become What You Absorb: How Input Shapes Your Life