Entrepreneurs
Entrepreneurs Are Job Creators, Not Job Seekers: Meaning and Examples

“Entrepreneurs are job creators, not job seekers” means that instead of competing for someone else’s opening, an entrepreneur builds a business that creates paid work, first for themselves and then for other people. The data backs it up: according to the SBA Office of Advocacy, small businesses created 20.7 million net new jobs from 1995 to 2024, about 61 percent of all net new jobs in the US. But the title is earned with the first hire, and most businesses never make one.

The phrase gets thrown around as a slogan. Muhammad Yunus, who shared the 2006 Nobel Peace Prize with Grameen Bank, has told young audiences to be job creators, not job seekers, including in the talk above. I agree with him. I also think the slogan hides the hard part, so let’s look at what it actually means, what the numbers say and what it takes to become one.
What “job creators, not job seekers” actually means
A job seeker looks at the market and asks, “Who will hire me?” A job creator looks at the same market and asks, “What problem can I solve that people will pay for, and who do I need to help me solve it?”
That shift matters more than any business plan. A job seeker’s income depends on someone else’s budget. A job creator’s income depends on whether customers keep buying. That’s scarier, and it’s also the only path where you decide how big the thing gets.
Here’s how the two mindsets compare in practice:
- Starting question: a job seeker asks who’s hiring; a job creator asks who’s buying.
- Source of income: one employer’s payroll versus many customers’ decisions.
- Risk: losing one job versus losing the business, which is why job creators have to manage cash so closely.
- Upside: a raise someone approves versus growth you build.
There are really three levels to it:
- You create your own job. You leave the application line and build income from customers.
- You create jobs for others. You make your first hire and someone else’s paycheck depends on your sales.
- You create an ecosystem. Your business grows enough that suppliers, contractors and the local economy around you grow too.
Why entrepreneurs are job creators: the data
The SBA Office of Advocacy’s February 2026 Frequently Asked Questions About Small Business is the cleanest source here. It defines a small business as an independent business with fewer than 500 employees. Here’s what it reports:
- There are 36,207,130 small businesses in the US.
- Small businesses employ 45.9 percent of private sector employees, or 62.3 million people.
- From January 1995 to December 2024, small businesses created 20.7 million net new jobs while large businesses created 13.2 million.
- Small businesses have accounted for 61 percent of net new job creation since 1995.
The report also explains a detail most people miss. When a small firm grows past 500 employees, its later job gains get counted as large-firm employment. So some of the “big business” jobs started life as somebody’s small business.
Churn is part of the picture too. The report says that in 2023, 1.3 million business establishments opened for the first time and about 1.2 million closed permanently. Job creation isn’t one big wave. It’s millions of people starting, failing, trying again and occasionally breaking through.
The uncomfortable stat: most businesses never hire anyone
Here’s the number the slogan skips. In the same SBA report, 82.3 percent of small businesses, or 29,811,495 firms, have no employees at all. Only 17.7 percent, about 6.4 million firms, have paid employees.
I don’t say that to knock solo businesses. Creating your own job is a real win, and plenty of one-person companies are excellent. But if you want to call yourself a job creator, be honest about which level you’re on. Most entrepreneurs are on level one. Getting to level two takes a different set of decisions.
Survival matters too. The SBA report says that from 1994 to 2022, about 49.2 percent of new employer establishments survived five years. A job you create only counts if the business is still standing to pay it.
A real example: Chobani’s first four hires
The clearest job-creator story I know comes from Hamdi Ulukaya, the founder of Chobani. In his TED talk, The anti-CEO playbook, he describes driving to an 85-year-old yogurt plant in upstate New York in January 2005 after getting a flyer in the mail. The plant was closing. There were 55 workers left, and their only job was to take it apart.
He got a loan, then another loan, and by August 2005 he had the keys. The first thing he did, he says, was hire four of the original 55 people: the office manager, the wastewater guy, the maintenance guy and the production manager who had shown him around.
Look at the order there. He didn’t start with a brand campaign. He started by putting four people back to work in a factory everyone else had written off. In the same talk, he says that when Chobani needed more workers, it recruited refugees from nearby Utica, arranging translators and buses, and that 30 percent of the Chobani workforce in that rural area are immigrants and refugees. TED’s speaker note says he introduced profit-sharing for Chobani’s 2,000 employees.
That’s the full arc: a job for himself, then four jobs, then thousands. Most of us won’t build a Chobani. You don’t need to. The same first step applies to a two-person agency or a local service business.
How to go from self-employed to job creator
If you’re on level one and want to reach level two, this is the order I’d work in.
- Make the work repeatable. You can’t hand off what only lives in your head. Write down how the work gets done before you hire anyone to do it.
- Find the bottleneck that pays. Your first hire should free you to do more of what brings in money, or bring in money directly. That’s why a lot of founders argue your first hire should be someone who can sell.
- Prove the revenue can carry a salary. Hiring on hope is how good businesses die. Make sure the numbers support the paycheck for months, not weeks.
- Get the classification right. Contractor or employee is a legal question, not a preference. Understand W-2 vs 1099 rules before you bring anyone on.
- Treat people like they matter. Ulukaya’s whole talk argues business should take care of its employees first. Whether or not you go as far as he did, the people who join early are betting on you. Act like it.
Why this mindset matters even if you never hire
Even if you stay solo forever, thinking like a job creator changes how you work. You stop asking for permission and start asking what the market needs. You build assets instead of waiting for opportunities. And when the economy shifts, you’re the one who can adapt, because your income was never tied to one employer’s decision.
The phrase sounds nice on a poster. It only means something when someone gets a paycheck because you built something. If you’re ready, write down the one role that would free up the most of your time, and figure out what revenue it would take to fill it.
FAQ
What does “entrepreneurs are job creators, not job seekers” mean?
It means entrepreneurs build businesses that create paid work instead of applying for existing jobs. They create their own job first, and become job creators in the full sense when they hire other people.
How many jobs do small businesses create in the US?
According to the SBA Office of Advocacy’s February 2026 report, small businesses created 20.7 million net new jobs from 1995 to 2024, about 61 percent of net new job creation, and employ 62.3 million people.
Are all entrepreneurs job creators?
Not in the hiring sense. The same SBA report says 82.3 percent of US small businesses have no employees. Every entrepreneur creates their own job, but only about 17.7 percent of small businesses employ others.
What is an example of an entrepreneur who created jobs?
Hamdi Ulukaya bought a closing yogurt plant in upstate New York in 2005 and first rehired four of its 55 remaining workers. Chobani later grew to thousands of employees.
How do you go from self-employed to job creator?
Make your work repeatable, hire for the bottleneck that brings in revenue, confirm the business can carry a salary, classify the role correctly as employee or contractor, and treat early hires well.






Entrepreneurs
How Ryan Grambart Turned a Simple Business Idea Into CopperSmith, an Architectural Metalwork Brand

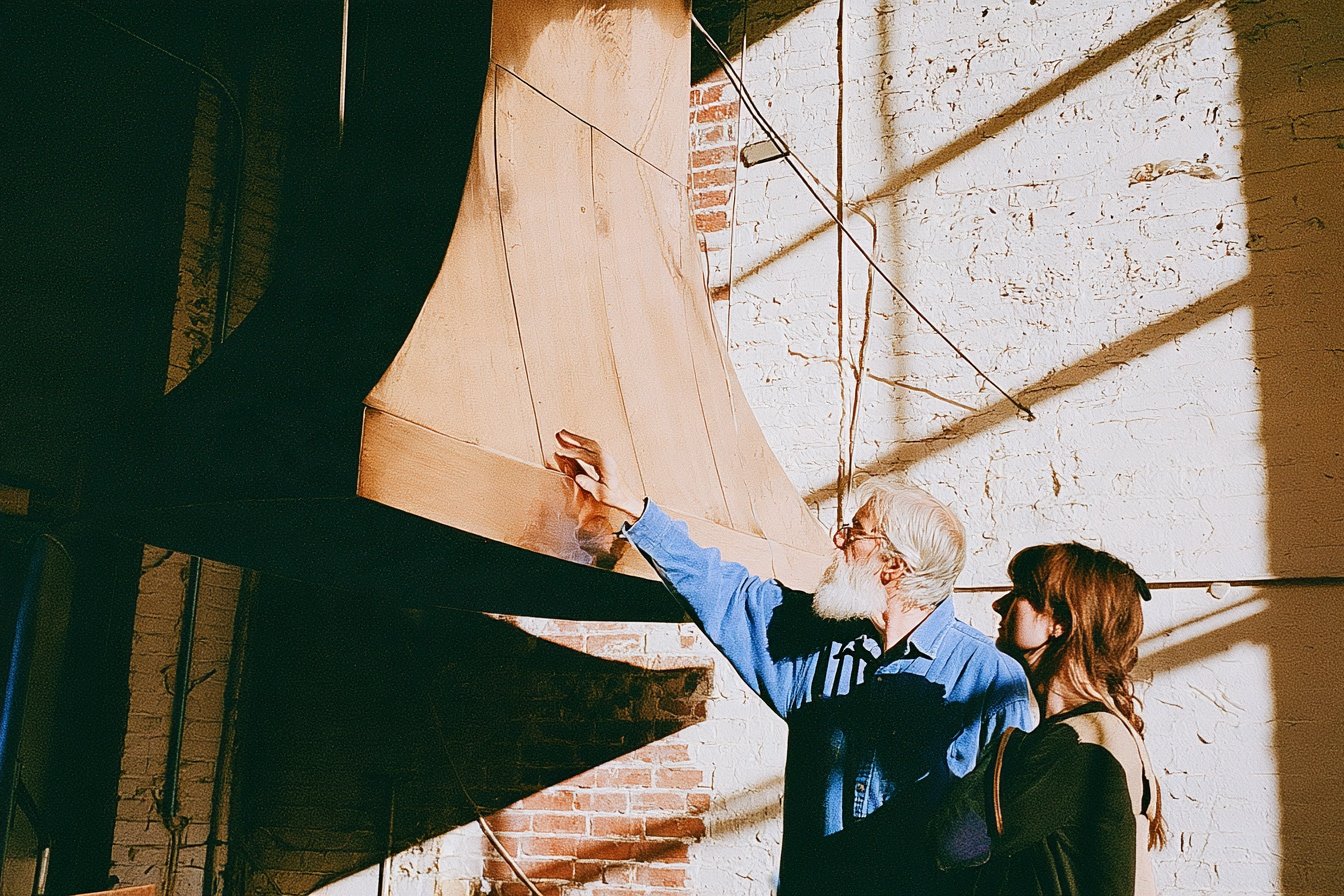
Some of the most successful businesses begin with a straightforward idea and the willingness to pursue opportunities beyond it. For Ryan Grambart, founder of CopperSmith, that idea was installing copper gutters.
What began as a small Minnesota business in 2009 evolved into a company specializing in architectural metalwork for residential and commercial spaces. Grambart’s journey reflects the value of practical experience, entrepreneurial adaptability, and finding new ways to serve an established market.
Starting Small With a Clear Vision
After graduating from Bemidji State University, Grambart invested approximately $5,000 to launch a copper gutter installation business.
He purchased a used van, rented specialized equipment, and advertised his services through Craigslist. With limited resources, he secured projects and built relationships with homeowners and contractors.
The work provided firsthand experience with copper, from its durability and architectural applications to the technical demands of installation. More importantly, it offered direct insight into the construction industry and the expectations of customers investing in specialized products.
His early experience demonstrates that building a business does not always require substantial capital. Industry knowledge, resourcefulness, and a willingness to begin can provide an equally valuable foundation.
Recognizing Opportunities Beyond the Original Business
Through his work in construction, Grambart became familiar with a wider range of architectural copper applications.
Range hoods, sinks, and bathtubs presented opportunities beyond exterior installations, introducing him to products where materials played both functional and aesthetic roles.
These categories also brought new considerations. A kitchen range hood, for example, needed to complement surrounding cabinetry while accommodating ventilation requirements. A bathtub or sink required careful attention to dimensions, material characteristics, and installation.
The potential to apply his experience across these categories helped Grambart envision a business extending beyond installation services.
For entrepreneurs, this expansion shows how knowledge gained in one market can create opportunities in adjacent industries.
Turning Customer Problems Into Business Opportunities
As Grambart explored architectural metalwork, he struggled to source products that met individual project specifications.
Homeowners, designers, and contractors often needed specific dimensions, materials, or finishes, but meeting those requirements could involve complex sourcing and communication.
He identified an opportunity to simplify the purchasing experience through an online platform that made specialized metalwork more accessible.
This concept became central to CopperSmith’s development, connecting customers with configurable architectural products and the guidance needed to move from initial selections to production.
The business addressed a practical market challenge: making products with complex specifications easier to explore and purchase.
Building a Business Around Quality and Craftsmanship
In architectural metalwork, the finished result depends on decisions made well before fabrication begins.
Proportion, structural requirements, material selection, and finishing must be considered together to ensure a product meets its intended application. This means the solutions are tailored to your kitchen.
CopperSmith incorporates design and engineering review into its process, including CAD drawings that let customers review and approve specifications before fabrication.
This attention to detail reduces uncertainty and creates a clearer connection between the original design vision and the finished piece.
For businesses offering specialized products, dependable execution can be a key competitive advantage. Quality is reflected not only in the product itself but also in the consistency of the process behind it.
Entrepreneurs should therefore consider how every stage of their operations influences customer satisfaction. Building a respected brand requires repeatedly delivering on promises, not simply making impressive marketing claims.
Understanding the Value of Personalization
Personalization plays a significant role in architectural design, where individual spaces rarely share identical dimensions, materials, or aesthetic requirements.
CopperSmith offers a range of configurations, finishes, and textures across materials including copper, brass, bronze, zinc, and stainless steel.
Each material brings distinct characteristics. Certain copper and brass finishes develop a natural patina, while sealed finishes are designed to maintain a more consistent appearance.
These differences influence how a product coordinates with surrounding cabinetry, stone, hardware, and other architectural elements.
Offering meaningful choices allows homeowners and design professionals to specify products that reflect their individual projects. The challenge for businesses is ensuring those choices remain clear, practical, and supported by reliable production standards.
Embracing Technology Without Losing Traditional Skills
For industries built around physical materials and specialized production, technology can create new opportunities without replacing established expertise.
CopperSmith’s online platform lets customers explore product options and configurations, making a category traditionally tied to complex specifications more accessible.
Digital tools are complemented by consultations and technical review, allowing customers to receive guidance as their projects develop.
This combination connects the convenience of online purchasing with the knowledge required for architectural applications.
Grambart’s approach illustrates how technology can modernize an established industry while preserving the importance of material understanding and technical execution.
Learning To Adapt As a Business Grows
The transition from a small installation operation to a broader architectural metalwork company introduced new demands.
Expanding product categories required capabilities beyond those of the original service business, including design coordination, engineering, customer support, and production management.
As CopperSmith developed, its operating model evolved to support these functions and serve a wider range of residential and commercial projects.
The progression highlights a challenge familiar to growing businesses: the systems that support an early-stage company may need to change as its offerings and customer base expand.
Successful adaptation requires developing the people, processes, and infrastructure needed for the next stage of growth.
Staying Focused On Long-Term Success
Building a lasting business requires balancing new opportunities with a clear understanding of the value it provides.
For CopperSmith, that value centers on helping customers bring architectural metalwork into their projects with greater clarity around design, materials, and execution.
The company’s expanded offering now spans range hoods, sinks, bathtubs, furniture, fire features, and other architectural applications.
While these products serve different purposes, they reflect a consistent focus on the relationship between aesthetics, functionality, and technical precision.
This continuity provides a foundation for growth while allowing the business to serve different markets and project requirements.
Final Thoughts
Ryan Grambart’s journey from copper gutter installation to founding CopperSmith demonstrates how practical experience can lead to a business far beyond its original scope.
His story highlights the importance of recognizing market opportunities, responding to customer needs, and developing the capabilities required to pursue them.
For aspiring entrepreneurs, the takeaway is straightforward: a successful business does not necessarily begin with an extraordinary idea. Sometimes, it begins with understanding an existing industry well enough to see what could be done differently.
Success in entrepreneurship usually hinges on catching opportunities before they become obvious to everyone else. While grit, sharp instincts, and solid business sense still form the bedrock of any solid company, another trait has quietly taken center stage: knowing exactly when to bet on modern tech.
The top founders aren’t just blindly grabbing every shiny gadget or downloading every app the day it drops. Instead, they stay curious, quietly test emerging tools, and figure out if there’s a real competitive edge hidden inside. For them, being an early adopter isn’t about bragging rights—it’s about reshaping how work gets done.
From generative AI to spatial computing and wearables, modern tools are rewiring how founders communicate, create, research, and scale operations. Those who figure out the mechanics early move noticeably faster while spending far less time stuck in operational quicksand.
Early Adoption Is Really About Learning Early
The real secret to adopting tools early isn’t the software or hardware itself—it’s getting a head start on the learning curve.
By the time a new platform goes mainstream, thousands of businesses rush in simultaneously, scrambling to figure it out. Entrepreneurs who started playing with it months or years prior already know its quirks, strengths, limitations, and realistic use cases. They’ve already built efficient systems while everyone else is still reading the setup manual.
Look at how generative AI unfolded. The teams that jumped in right away quickly learned where AI excelled and, more importantly, where human oversight remained non-negotiable.
Early adopters tend to run every new tool through a quick mental filter:
- Can this win me back hours every week?
- Will this directly elevate my customer’s experience?
- Does this remove friction for my core team?
- Can it help us gather market intelligence faster?
- Does this open up a revenue stream that didn’t exist yesterday?
It was never about collecting tech for the sake of it. It’s about building deep domain familiarity before the rest of the market catches on.
Entrepreneurs Think in Terms of Leverage
High-performing founders are obsessed with leverage.
They want a single hour of effort to yield three hours of results. They build lean teams that can pull off the output of a 50-person department. They construct automated frameworks that keep the business spinning cleanly, even when they step away from their desks.
Technology is the ultimate force multiplier for that mindset.
Smart workflows clear away mind-numbing administrative work. AI accelerates deep research and rough drafting. Modern team hubs make distributed work feel effortless, and sharp analytics replace gut-check guesses with hard data.
Wearable technology represents a huge leap forward in this exact pursuit.
Instead of forcing you to pull out a phone or open a laptop every time you need to record or check something, wearables bring tech directly into your line of sight and sound. That’s a massive shift for active founders who spend their days moving between pitch meetings, site visits, conferences, and travel.
The Rise of Hands-Free Technology
For over a decade, smartphones have held a total monopoly on mobile productivity. But let’s be honest: constantly digging a phone out of your pocket breaks your flow, ruins face-to-face eye contact, and pulls you out of the room.
That explains why smart eyewear is suddenly having a moment.
Modern smart glasses blend classic, everyday frames with high-resolution sensors, direction-focused audio, responsive voice commands, and on-demand AI. For a busy founder, that seamless mix changes daily execution in small, subtle ways.
Picture a founder walking a busy trade show floor who wants to record a quick takeaway without staring into a screen. Or a real estate developer walking a site who can instantly ask an AI assistant for zoning rules while keeping their hands totally free.
Certain products, like AI glasses with a camera from Sunglasshut, highlight how fast wearable tech is transitioning from novelty gadgets to legitimate daily driver gear. Current luxury Meta frames available through SunglassHut pack full media capture, open-ear audio, voice controls, and direct Meta AI interaction directly into classic frames.
Not every business owner needs smart glasses on day one. But the broader lesson is clear: keep a close eye on any tool that closes the gap between having a thought and executing on it.
Capturing Ideas Before They Disappear
Great ideas arrive at inconvenient times.
A casual coffee conversation with a client sparks a entire product pivot. A quick off-hand comment at a keynote unlocks a new marketing angle. A annoying logistical bottleneck during business travel reveals a brand-new SaaS opportunity.
The real challenge isn’t having the idea—it’s capturing it before daily noise washes it away.
Traditional notes apps certainly work, but hands-free tech offers a friction-free alternative. Voice control and effortless media capture let you store context, visual proof, or raw thoughts in real time without stopping what you’re doing.
It doesn’t generate the brilliance for you. It just ensures your best thoughts actually stick around to see the light of day.
Better Technology Doesn’t Replace Better Thinking
There’s a critical line between leveraging modern tech and leaning on it as a crutch.
Smart founders know these systems are built to amplify human intelligence, not substitute for it.
An AI engine can summarize a massive legal document, spot trends, draft emails, and run simulations in seconds. But deciding which strategic path to take still takes seasoned human judgment. A wearable camera records a vital moment, but you still have to know why that moment mattered in the first place.
That’s precisely why thoughtful early adopters treat tech as an ongoing experiment rather than a silver bullet. They test a workflow, run the numbers, track performance, and keep only what truly moves the needle.
Technology Can Create New Customer Experiences
Beyond internal efficiency, early adopters constantly search for new ways technology can elevate how customers experience their brand.
We’ve watched commerce evolve from brick-and-mortar storefronts to early websites, then to custom mobile apps, social shopping, and instant chat platforms. Every single wave rewarded the businesses that adapted their customer journeys first.
Wearable tech is positioning itself as the next frontier for that shift:
- Real estate agents filming natural, immersive walkthroughs without holding bulky gear.
- Fitness creators sharing authentic, first-person training form guides.
- Field technicians and consultants pulling up real-time specs or instant language translation while navigating complex environments.
None of these individual setups are earth-shattering on their own. The actual advantage comes from creatively mapping those capabilities to your specific niche before your competition realizes it’s possible.
Being an Early Adopter Doesn’t Mean Being Reckless
There is a huge difference between being an early adopter and being a impulse buyer chasing shiny objects.
Pragmatic founders are fiercely protective of their time, focus, and capital. They don’t buy into tech hype just because tech Twitter is buzzing about it.
Instead, they run new tools through three simple reality checks:
- Does this solve a problem I’m actively dealing with? Tech shines brightest when it breaks a clear operational bottleneck. If it clearly saves hours or cleans up messy communication, it’s worth investigating.
- Does this meaningfully improve an existing process? Transformation doesn’t always have to be dramatic. Shaving 10% off a daily task compounds into massive operational savings across a full year.
- What can we learn just by testing this? Even if a tool ultimately gets shelved, the process of testing it reveals where software, consumer expectations, and markets are heading next.
That grounded mindset keeps experimentation low-risk and high-reward.
The Competitive Advantage of Curiosity
At its core, successful tech adoption is driven by raw, relentless curiosity.
Founders who stay genuinely curious spot subtle shifts in consumer habits, software capabilities, and market dynamics way before the crowd. They ask “what if?” instead of immediately writing off unfamiliar tech.
That open-mindedness matters, because massive tech shifts almost always look like silly gimmicks at first.
Smartphones were originally written off as unnecessary toys for executives. Cloud computing was distrusted over security fears. Social media was dismissed as a platform for teenager status updates. Today, AI and ambient computing are completely reshaping knowledge work.
The entrepreneurs willing to lean in and experiment today are building the exact muscle memory required to dominate tomorrow.
The Future Belongs to Adaptable Entrepreneurs
Technology will continue to evolve at a blistering, uncomfortable pace. New hardware, smarter AI models, automated platforms, and spatial tools will flood the market every single quarter.
You don’t need to adopt every single tool that crosses your feed.
What you do need is the willingness to look under the hood.
The most effective founders know that technology carries zero intrinsic value on its own—its worth lies entirely in what it empowers you to build, solve, and execute. Early adoption isn’t about bragging about new gear. It’s about cultivating the habit of asking one game-changing question:
“If this actually works, how does it change what we can build?”
That simple question is where real market leaders are made.
Entrepreneurs
What Risks Do Entrepreneurs Create When They Turn Personal Expertise into a Paid Service?


Businesses often begin when clients pay for existing expertise. A marketer becomes a consultant, a fitness enthusiast a coach, or a designer a freelancer. Payment creates duties that informal advice never carried. Clients can lose money, suffer injury, expose data, or challenge ownership.
The first task is to define what is being sold and what could go wrong. Suitable insurance for business should support this assessment, but a policy cannot repair unclear promises, weak records, or work performed outside the entrepreneur’s competence. The safest approach combines clear contracts, sound working methods, suitable insurance, and honest marketing.
Expertise Creates a Contractual Standard
Under the Consumer Rights Act 2015, services supplied to consumers must be performed with reasonable care and skill. This does not guarantee a perfect result. It means the provider should work to the standard expected from a competent person offering that service.
For example, a career coach cannot guarantee that a client will secure a £60,000 role. However, the coach should not rewrite a CV using false qualifications, miss agreed deadlines, or give advice without checking basic facts. Problems often begin when promotional language promises outcomes that the provider cannot control.
Entrepreneurs should state the service scope before starting work. A useful agreement should identify these points:
- The exact deliverables and number of revisions
- Deadlines and information the client must provide
- Fees, payment dates, cancellation terms, and refund rules
- Exclusions and limits on the service
Advice Can Cause Measurable Financial Loss
Professional indemnity insurance covers certain claims arising from negligent professional services or advice. It may help with legal defence costs and compensation, subject to the policy wording, limit, excess, and exclusions.
Consider a marketing consultant who schedules a retailer’s campaign after a sales event. The client claims that wasted advertising spend and lost sales resulted from the mistake. Even when the allegation is disputed, obtaining legal advice can cost money.
Common professional claim triggers can include:
- Incorrect advice, calculations, specifications, or instructions
- Missed deadlines that cause a client financial loss
- Accidental breaches of confidentiality
- Lost documents or corrupted client files
- Claims involving copyright or other intellectual property
Professional indemnity policies commonly respond only to claims made while cover is active. The policy normally needs to be in force when the claim is made, not only when the work occurred. Continuous cover and an appropriate retroactive date therefore matter when changing insurer or stopping trading.
Client Contact Creates Physical and Digital Risks
A knowledge business can still cause physical harm or property damage. A client may trip over equipment during a workshop, or a consultant may damage a computer at the client’s premises. Public liability insurance is designed for claims from members of the public connected with business activities.
Digital work creates another serious operational risk. Coaches, tutors, recruiters, and advisers may store addresses, health details, payment records, or confidential business files. Sending information to the wrong recipient, losing an unencrypted laptop, or suffering a ransomware attack can create a personal data breach. Reportable breaches must normally be reported to the Information Commissioner’s Office within 72 hours of the business becoming aware of them.
Cyber insurance may cover investigation, restoration, notification, and liability costs. Entrepreneurs should still use multifactor authentication, encrypted devices, restricted file access, secure backups, and a written breach response process.
Contracts Must Address Ownership and Responsibility
Intellectual property often causes expensive client disputes. In the UK, an independent creator usually owns the intellectual property in commissioned work unless the contract transfers those rights. Paying for a logo does not automatically settle questions about ownership, modification, resale, or portfolio use.
Contracts should specify whether the client receives ownership or a licence, when rights transfer, and whether materials from others are included. Entrepreneurs must also confirm that fonts, photographs, templates, software, music, and research can legally be used for the intended commercial purpose.
Business Structure Does Not Replace Protection
A sole trader has unlimited liability, meaning business debts are legally personal debts. A limited company is a separate legal entity, but incorporation does not remove every exposure. Directors can still face personal consequences for guarantees, unlawful conduct, regulatory failures, or their own negligent acts.
The trading structure, contract, and insurance policy should work together. Hiring staff introduces another important legal duty. Most UK employers must hold employers’ liability insurance of at least £5 million for employee injury or illness connected with work.
Checks before Accepting Paid Work
Before signing a client, an entrepreneur should:
- Confirm that the work matches their training and experience
- Record the agreed outcome, assumptions, and exclusions
- Check policy limits, excesses, activities, territories, and exclusions
- Avoid guarantees where results depend on outside factors
- Keep dated advice, approvals, revisions, and delivery records
Turning expertise into income can be rewarding, but payment changes the relationship. A dependable service needs more than talent. It requires defined boundaries, evidence of decisions, secure information handling, and insurance matched to the work being performed.

Having breakfast with billionaires isn’t just about the coffee; it’s a front-row seat to a masterclass in wealth creation. When you spend enough time around the top 0.001% of the economy, you quickly realize that their success isn’t just a byproduct of hard work or extreme intelligence. It’s the result of operating on a completely different framework than the rest of the world.
These aren’t secrets reserved for the elite. These are actionable strategies you can apply today to accelerate your own financial trajectory. Here are seven distinct ways billionaires think and act differently to achieve crazy high levels of success.
1. They Don’t Wait for Luck; They Engineer the Odds
Most people view luck as an on/off switch—you either get a lucky break or you don’t. Billionaires view luck as a dimmer switch. They understand that while you cannot control the lucky break itself, you are in complete control of the odds of it happening.
If you sit on your couch doom-scrolling, you have reduced the odds of a lucky encounter to zero. If you go to a networking event, pitch your business to a new investor, or launch a new product, you’ve instantly increased the odds of luck finding you.
Take Richard Branson. He frequently attributes his success to “lucky timing” and “lucky breaks.” But what people overlook is that Branson started over 400 companies and signed hundreds of artists to his record label. Most failed, but a few became wildly successful. He didn’t just get lucky; he put so many irons in the fire that mathematical probability guaranteed one of them would strike hot.
The Takeaway: Are you putting yourself out there enough to get lucky? Increase your pitch volume, product launches, and networking interactions to artificially inflate your odds of a lucky break.
2. They Invent Their Own Currencies
The middle class trades time for dollars, euros, or pounds. It is a very basic, low-level way to view currency. Billionaires create alternative currencies and use them as leverage.
- The Currency of Equity: If a founder sells 10% of their startup for $10 million, the entire company is now valued at $100 million. They can now use their remaining shares as a currency to acquire other businesses or attract top talent, without spending a dime of actual cash.
- The Currency of Reputation: A highly respected billionaire can join an advisory board, and their mere association will double the valuation of that company. They treat their name as currency and trade it for equity.
- The Currency of Distribution: If you have an email list of 600,000 engaged buyers, or 50,000 highly targeted LinkedIn followers, that is a currency. You can use that distribution power to negotiate equity stakes in other businesses.
3. They Reverse-Engineer the Future
Most entrepreneurs forward-engineer the past. They look at what they did yesterday to figure out what to do tomorrow. Billionaires reverse-engineer the future.
They project themselves three years forward and create a vivid, highly detailed picture of their company. They know their exact revenue, profit margins, team size, and intellectual property. Once that vision is locked in, they work backward:
- If this is true in 3 years, where must we be in 2 years?
- If that is true in 2 years, where must we be in 1 year?
- If that is true in 1 year, what must I do this week?
Because they have such a clear vision of the future, they become master storytellers. They can walk into a room, pitch an investor or a top-tier CEO, and say, “This is exactly where we will be in 36 months, and here is the exact role I want you to play.” They don’t care about their past; they only care about assembling the resources to meet their future.
4. They Are Master Enrollers, Not Doers
A great business is simply a collection of exceptional people aligned toward a common goal. Billionaires rarely do the actual “work” themselves because they understand that a single visionary cannot execute a 500-person vision alone.
Their full-time job is identifying, recruiting, enrolling, and aligning top-tier talent. As one billionaire noted, “A thousand good musicians cannot write a single symphony. But Beethoven wrote nine of them.” The difference between good talent and great talent is exponential.
Billionaires are constantly hunting for four types of people to enroll in their vision:
- Distribution Masters: People with massive audiences or traffic.
- Leadership Talent: Elite executives who can drive teams (CFOs, COOs).
- Elite Practitioners: The best-in-class engineers, sales reps, or artists.
- Capital Providers: Angel investors and VCs who can fund the vision.
5. They Harness the Dark Side of Motivation
Millionaires motivate their teams with carrots—vision boards, bonuses, and big goals. Billionaires know how to use the stick. They understand that while human beings are motivated by positive outcomes, they are ferociously driven by negative ones.
Billionaires intentionally create a common enemy to rally their team against.
- Richard Branson made British Airways the enemy.
- Steve Jobs famously made IBM the enemy in 1984.
Whether it is a rival company, an outdated political system, or a local competitor across the street, giving your team a tangible enemy to vanquish unlocks a level of gritty, relentless motivation that positive reinforcement simply cannot touch.
6. They Only Play Games of “Value at Scale”
A private tutor or a nurse provides immense value, but their impact is limited to the physical room they are in. The modern economy does not reward pure value; it only rewards value at scale.
Billionaires build systems that deliver value to millions of people simultaneously. There are four primary levers they use to achieve this scale:
- Intellectual Property: Patents, books, media rights, and franchise manuals.
- Distribution Channels: Owning retail chains, massive email lists, or media platforms.
- Armies of People: Training massive workforces to execute a standardized service globally.
- Software/Code: The ultimate scaler. Code written once can be accessed by billions of people instantly.
If your business relies on complex, bespoke solutions, it will hit a wall. Simple scales; complexity fails.
7. They Build to Exit
We often hear the romanticized stories of founders building their companies from the ground up, but we rarely hear the most important part of the billionaire playbook: The Exit Event.
Almost every ultra-wealthy individual built their fortune through a series of exits. They build a company, sell it, and take the cash.
But an exit provides something far more valuable than just liquidity—it provides time and consolidated learnings. When an entrepreneur sells a business, they clear the deck. They can look back at their 5-year journey, analyze their mistakes, and launch their next venture with capital, free time, and elite experience.
Many entrepreneurs hold onto their first business far too long. Your current business is based on the best thinking you had five years ago. An exit allows you to launch your next empire based on everything you know today.
Daniel Prestley the Aussie entrepreneur nails the top points of what makes the Top 0.1% do to be successful:


The 13-Week Cash Flow Forecast: How to See a Cash Crunch Before It Hits

Entrepreneurs Are Job Creators, Not Job Seekers: Meaning and Examples

How a Solo Founder Can Launch a Mobile App Without Hiring Developers

6 Lessons Entrepreneurs Can Learn From Uber and Airbnb’s Early Days

What Do Investors Look For? A Shark Tank Investor’s Honest Checklist
5 Ways For Startups To Succeed Making Acquisitions

77 Inspirational Quotes That Will Change Your Life

57 Memorable Kobe Bryant Quotes

Motivational Picture Quotes: 52 Images to Inspire a Successful Year
40 Rare Motivational and Inspirational Picture Quotes
3 Prince EA Videos To Change Humanities Path To Greatness
(Video) What Is Success? An Entrepreneurial Story To Inspire You
(Inspirational Video) What If Today You Knew You Were Going To Take Your Last Breath?
How To Make Enough Money From A Blog To Quit Your Job – Kate McKibbin
How Finding Your Passion And Becoming An Entrepreneur Can Lead To Happiness – Chiquita Searle
-

 Did You Know1 year ago
7 Surprising Life Lessons Video Games Taught Me That School Never Did
-
 Life2 years ago
The 5 Stages of a Quarter-Life Crisis & What You Can Do
-
 Success Advice1 year ago
Stephen Covey’s 8 Leadership Habits That Will Change How You Lead Forever
-

 Life1 year ago
How to Stop the War in Your Head and Find Peace
-

 Featured2 years ago
The Psychology of Motivation: How to Keep Moving Forward Every Day
-
 Personal Development2 years ago
The Three-Second Pause That Changes How People Perceive You
-
 Explode Your Social Media1 year ago
Want More Views? Master These 6 YouTube Growth Tactics
-
 Change Your Mindset1 year ago
You Become What You Absorb: How Input Shapes Your Life