Crypto News
A Comprehensive Analysis of the Digital Silver Known as Litecoin
Litecoin is a salient contender within the cryptocurrency ecosystem. Its distinctive attributes, accelerated transaction times, and prospects for heightened adoption set it apart from the broader cohort.

The transformative influence of cryptocurrencies within the realm of finance has been resounding, and amidst this transformative landscape, Litecoin has asserted itself as a significant contender. The cryptocurrency arena, marked by its diversity, offers an array of choices for discerning investors and traders. Amidst this plurality, Litecoin, often dubbed as the ‘silver counterpart to Bitcoin’s gold,’ has consistently garnered attention due to its distinctive attributes, growth potential, and nuanced advantages vis-à-vis its counterparts such as Bitcoin, Ethereum, and even the meme-driven Shiba Inu.
The Pertinence of Litecoin’s Valuation
In the sphere of cryptocurrencies, the dynamics of valuation inevitably occupy a central role. While the prudence of investment decisions demands a panoramic perspective, it is incontrovertible that the valuation of Litecoin is an integral aspect for both traders and investors.
As of the current date, the Litecoin price stands at $82.15, thereby demonstrating its resilience and value proposition within a market characterized by volatility.
However, constraining the evaluation to mere valuation would be an overly narrow approach. A comprehensive understanding of Litecoin necessitates a more profound exploration of its underlying mechanisms and the rationale behind its potential as a promising investment avenue.
Distinctive Attributes of Litecoin
Crafted by Charlie Lee in 2011, Litecoin shares foundational elements with Bitcoin owing to its open-source nature and its reliance on blockchain infrastructure. Yet, it diverges in several pivotal facets, rendering it an asset of discernible significance. A standout feature of Litecoin resides in its accelerated block generation time.
Whereas Bitcoin requires approximately 10 minutes for block mining, Litecoin achieves this feat within a mere 2.5 minutes. This accelerated transaction confirmation timeframe augments network efficiency and propels Litecoin as an eminently practical option for real-world transactions.
Moreover, the capped supply of 84 million Litecoin coins, as opposed to Bitcoin’s limit of 21 million, engenders a sense of scarcity that might inevitably exert influence over its future valuation. The interplay of supply and demand could manifest as a determinative factor in fostering a surge in Litecoin’s value, thereby imbuing it with a distinct allure as a long-term investment.
The truncated transaction fees associated with the Litecoin network further amplify its appeal, particularly within a landscape fraught with concerns of exorbitant fees.
Anticipating the Trajectory: Litecoin’s Prospects
The trajectory of Litecoin appears promising, particularly as the cryptocurrency domain undergoes continuous evolution. While Litecoin might not command the same quantum of media spotlight as Bitcoin or Ethereum, its progressive adoption and burgeoning utility remain irrefutable.
The potential assimilation of the Lightning Network, an auxiliary scaling solution, has the propensity to bolster Litecoin’s scalability, augmenting the feasibility of microtransactions. Furthermore, synergistic alliances with payment processors and commercial entities could solidify its standing as a viable medium of exchange.
A Comparative Appraisal of Litecoin
In the context of evaluating Litecoin as an investment prospect, a comparative analysis vis-à-vis its contemporaries becomes imperative.
Bitcoin, lauded as the digital equivalent of gold, has entrenched itself as a repository of value and a hedge against inflation. In contrast, Ethereum transcends the realm of mere cryptocurrency, operating as a conduit for decentralized applications and facilitating the deployment of smart contracts and decentralized finance (DeFi) projects. The Shiba Inu token, inspired by the viral traction of Dogecoin, pivots heavily on memes and speculative fervor.
Relative to these, Litecoin straddles an intermediary position. Its expedited transaction confirmation time positions it as conducive to day-to-day transactions, akin to conventional currencies. This attribute could proffer Litecoin a strategic edge as the cryptocurrency domain transitions toward mainstream assimilation.
Additionally, Litecoin’s established history coupled with a comparably modest valuation, as contrasted with Bitcoin, might captivate investors seeking opportunities beyond the saturation of the Bitcoin market.
Navigating the Terrain of Volatility
Whilst the cryptocurrency realm brims with potential, it would be remiss not to acknowledge its inherent volatility. Litecoin, akin to its counterparts, remains susceptible to vicissitudes in valuation. It is judicious for investors to undertake meticulous research, diversify their portfolios, and allocate resources commensurate with their risk tolerance.
By doing so, it can become far simpler to ascertain the types of market fluctuations that can be expected, with many traders placing their hope in Litecoin as its growth and development have mimicked the patterns commonly associated with Bitcoin, which is now by far the most valuable (in price) form of cryptocurrency on the market.
If Litecoin lives up to its potential, it could go on to become just as, if not more valuable according to some leading expert opinions, than its predecessor, and considering the entry-level price of the token, this has led to many traders being willing to allocate a small portion of their budget to add this crypto to their wallet for long-term potential.
Litecoin emerges as a salient contender within the cryptocurrency ecosystem. Its distinctive attributes, accelerated transaction times, and prospects for heightened adoption set it apart from the broader cohort. While valuation indeed commands attention from investors and traders, the intrinsic value proposition of Litecoin transcends the present valuation metric. As the landscape of cryptocurrencies continues to evolve, Litecoin’s identity as the ‘silver complement to Bitcoin’s gold’ could potentially appreciate in significance. Nevertheless, prudence dictates meticulous deliberation and due diligence prior to engaging with Litecoin or any other cryptocurrency, mindful of the intricacies inherent to the investment domain.









Bitcoin ETF vs owning bitcoin comes down to convenience or control: a spot bitcoin ETF gives you bitcoin price exposure inside a normal brokerage or retirement account for an annual fee, while owning bitcoin gives you the actual coins and the keys – plus every security and record-keeping job that comes with them. As of early November 2026, most major U.S. spot bitcoin ETFs charge expense ratios between 0.14% and 0.25%. Direct ownership has no annual fund fee, but you pay trading spreads, network fees, and the cost of protecting your keys.
Picture two founders who both decide they want bitcoin exposure this quarter. One opens the same brokerage app that holds her index funds, types a ticker, and is done before her coffee cools. The other orders a hardware wallet, writes a seed phrase on a steel plate, and spends a Saturday learning what a receive address is. Both now “own bitcoin.” Only one of them can send it to anyone on earth at 2 a.m. on a Sunday. Only one of them will never get a call from a confused heir asking where the twelve words are.
Neither founder is wrong. They bought different things. That is the whole point of this comparison.
Rajat Soni, CFA, walks through the trade-offs between holding a bitcoin ETF and holding the coins yourself:
What You Actually Own in Each Case
When you buy a spot bitcoin ETF, you own shares of a fund. The fund owns the bitcoin, and a custodian holds it on the fund’s behalf. You get the price exposure, but you have no private keys and you cannot ask the fund to send coins to your wallet. To leave, you sell shares through your broker.
When you own bitcoin directly, the network recognizes whoever controls the private keys. Hold the keys yourself and nobody else can move those coins. Leave them on an exchange and you have an account balance with that company – you are trusting the platform to honor it.
One detail most comparison pages skip: many spot bitcoin funds, including the iShares Bitcoin Trust, are not registered under the Investment Company Act of 1940, so they do not carry the same regulatory framework as a typical mutual fund or stock ETF. Read the prospectus before you treat it like any other index fund.
Bitcoin ETF vs Owning Bitcoin: Side-by-Side
| Factor | Spot bitcoin ETF | Owning bitcoin directly |
|---|---|---|
| What you hold | Fund shares in a brokerage account | The coins, controlled by private keys (yours or an exchange’s) |
| Ongoing cost | Annual expense ratio, about 0.14%-0.25% for most major funds; one legacy fund charges 1.50% | No annual fund fee; trading fees, spreads, network fees, optional hardware wallet |
| Custody risk | Fund sponsor and its custodian | You (self-custody) or the exchange (custodial account) |
| Trading hours | Stock market hours | 24/7 |
| Can you spend or send it? | No | Yes |
| Tax paperwork | Standard brokerage tax forms | Your own lot-by-lot records, plus any broker forms |
| IRA / Solo 401(k) | Often available wherever your plan allows ETFs | Usually requires a specialized self-directed custodian |
| Inheritance | Transfers like any other security | Needs a documented key recovery plan |
Fees: The Expense Ratio vs the Hidden Costs of Owning Coins
Current fund pages and NerdWallet’s spot bitcoin ETF fee table (data as of November 2, 2026) show the low end at Morgan Stanley Bitcoin Trust (MSBT) at 0.14% and Grayscale Bitcoin Mini Trust (BTC) at 0.15%. Bitwise (BITB) sits at 0.20%, ARK 21Shares (ARKB) at 0.21%, and iShares Bitcoin Trust (IBIT) and Fidelity Wise Origin Bitcoin Fund (FBTC) at 0.25%. The outlier is the original Grayscale Bitcoin Trust (GBTC) at 1.50%. Fees change, so confirm the current number on the sponsor’s site the day you buy.
Here is how that fee actually works. You never get a bill. The fund sells a little bitcoin over time to pay its sponsor, so the amount of bitcoin behind each share slowly shrinks. On $50,000, a 0.25% fee is about $125 a year. Small, but it runs every year you hold.
Owning coins directly skips that annual drag, but it is not free. You pay exchange fees and spreads when you buy, network fees when you move coins, and maybe $100 or more for a hardware wallet. For a buy-and-hold owner, those costs can come out lower over a long horizon. For someone who buys small amounts often on a high-fee app, the ETF can actually be the cheaper route.
Custody: Who Do You Trust With the Keys?
This is the real heart of convenience vs control.
With an ETF, you are trusting a fund sponsor and its custodian – and a large share of U.S. spot bitcoin ETF assets sits with a single custodian, Coinbase. If something went badly wrong there, recovery would likely run through legal processes, not an instant fix. You also rely on your broker and the stock market being open when you want out.
With self-custody, you remove the middlemen and take on the job yourself. Lose the seed phrase, get phished, or leave no instructions for your family, and there is no help desk. For most individual holders, the bigger day-to-day risk is not a fund failing – it is their own sloppy key storage. If you go this route, treat key security like a business process – written, tested, and backed up in more than one secure place.
There is a middle path too: holding coins in a reputable, regulated exchange account. You get the asset and the ability to withdraw later, but you are trusting the platform in the meantime.
Taxes: Same Gains, Different Paperwork
In a taxable account, the big picture is similar either way. Sell for more than you paid and you have a capital gain; hold more than a year and it is generally long-term. The difference is the paperwork.
ETF shares show up on your regular brokerage tax statements, often next to your stock funds. Many spot funds are structured as grantor trusts, so the fund’s small bitcoin sales to cover its fee can create minor reportable items your broker’s tax package includes. Hand that package to your CPA rather than ignoring it.
Owning coins directly makes you the record-keeper. Every sale, swap, and purchase paid in bitcoin is a taxable disposal, and you need dates, costs, and wallet-level records to prove your numbers. If you value a clean tax season more than control, that is a genuine point for the ETF. Either way, a CPA who works with digital assets earns their fee here.
IRA and Solo 401(k) Access
This is where the ETF pulls ahead for a lot of business owners. If you already fund a Solo 401(k) or a SEP IRA through a mainstream brokerage, you can often buy a spot bitcoin ETF inside it the same way you buy any other ETF – subject to your provider and plan rules. Gains then follow the account’s tax treatment instead of your yearly capital gains math.
Holding actual coins in a retirement account is a different project. It usually means a self-directed IRA custodian or a specially structured plan, extra fees, and strict prohibited-transaction rules. You generally cannot keep the keys in your own desk drawer. If you want coins inside a tax-advantaged account, talk to a CPA or ERISA-savvy adviser before you move a dollar.
How I Would Decide
Bitcoin has entered a more mature phase, and that is part of why this wrapper question matters now. Whatever amount you have already decided on, the wrapper decision is separate. Run these questions honestly:
- Do you want to use bitcoin or just own its price? If you never plan to send, spend, or move coins, the ETF does the job.
- Will you protect keys like a business asset? If the honest answer is “probably not,” custody risk at home may be bigger than custody risk at a fund.
- Is the money going into a retirement account? If yes, the ETF is usually the simpler path.
- How much do you care about 24/7 access? Weekend moves happen. ETF holders wait for Monday.
- Who inherits it? A brokerage beneficiary form is easy. A seed phrase with no plan is a family emergency.
- Can you keep clean records? If not, the ETF’s tax statements save you real time.
Some people end up holding both: an ETF in the retirement account for simplicity, and some coins in self-custody because they want the real thing. There is nothing contradictory about that.
Convenience is a feature. Control is a feature. You just cannot have the full version of both in the same wrapper.
This article is education, not investment or tax advice, and nothing here is a recommendation to buy any fund or coin. Bitcoin is volatile in either wrapper. Do your own research and talk to a qualified adviser and CPA about your situation.
Bitcoin ETF vs Owning Bitcoin FAQs
Is a bitcoin ETF the same as owning bitcoin?
No. A spot bitcoin ETF gives you shares of a fund that holds bitcoin through a custodian. You get price exposure but no private keys, and you cannot send or spend the coins. Owning bitcoin directly means you or your exchange controls the keys.
What do spot bitcoin ETFs cost?
As of early November 2026, most major U.S. spot bitcoin ETFs charge about 0.14% to 0.25% a year, while Grayscale’s original GBTC charges 1.50%. The fee is taken from fund assets, slowly reducing the bitcoin behind each share. Confirm current fees before buying.
Can I hold a bitcoin ETF in an IRA or Solo 401(k)?
Often, yes, if your brokerage and plan allow ETFs. You buy it like any other ETF inside the account. Holding actual coins in a retirement account usually requires a specialized self-directed custodian, extra fees, and careful prohibited-transaction planning.
Are bitcoin ETFs taxed differently than bitcoin?
In taxable accounts, both generally produce capital gains or losses when sold. The difference is paperwork: ETFs arrive on standard brokerage tax statements, while direct owners must track dates, costs, and wallets themselves. Ask a CPA about your specifics.
Which is safer, a bitcoin ETF or self-custody?
Each carries different risks. ETFs depend on the fund sponsor, custodian, and market hours. Self-custody removes middlemen but makes you responsible for keys, backups, and inheritance planning. The safer choice is the one you can actually manage well.


Starting a business today involves more than developing a good product or finding the right customers. New companies must also decide how to handle payments, manage expenses and compete in a marketplace where financial technology continues to evolve. With more business activity taking place online, traditional banking methods are no longer the only options available.
Cryptocurrency has become part of this conversation. Although digital currencies were initially associated with individual investors and online trading, businesses are increasingly exploring their practical applications. From accepting international payments to reaching customers who prefer digital assets, cryptocurrency offers opportunities worth examining.
For emerging businesses, however, the decision requires careful planning. Understanding where cryptocurrency can provide genuine value, along with its limitations, is essential before introducing it into everyday operations.
Expanding Payment Options for Customers
One of the most practical reasons for businesses to consider cryptocurrency is the opportunity to offer customers additional payment methods. Consumers already expect flexibility when shopping online, whether they prefer debit cards, digital wallets or other electronic payments.
Cryptocurrency adds another option, particularly for customers who already own digital assets and prefer spending them directly.
For an emerging e-commerce business, accepting selected cryptocurrencies could help accommodate a broader range of payment preferences. A digital design company, online retailer or technology service provider may find that some international customers appreciate having an alternative to conventional payment networks.
However, accepting cryptocurrency does not mean a business must hold it. Certain payment processors can convert digital assets into traditional currency during settlement, reducing exposure to price fluctuations.
The important question is whether customers actually want this option. Businesses should evaluate demand before investing in new payment systems.
Making International Transactions More Accessible
Expanding into international markets can create opportunities for young businesses, but cross-border payments sometimes introduce complications. Currency conversion costs, banking restrictions and processing delays can make transactions less convenient.
Cryptocurrency may offer an alternative way to transfer value between parties in different countries without relying on every intermediary involved in conventional international transfers.
Consider a startup that works with freelance developers overseas. Depending on local regulations and the preferences of both parties, digital assets could provide another way to settle invoices.
Some stablecoins, which are designed to maintain a value relative to an asset such as the US dollar, may be particularly relevant for businesses seeking to limit price volatility. However, their stability depends on factors such as reserves, redemption arrangements and the reliability of their issuers.
Transaction fees, conversion charges and compliance requirements still apply. Before adopting cryptocurrency for international business, companies should compare the complete cost of each payment method rather than assuming blockchain transactions are automatically cheaper.
Exploring New Approaches to Business Finances
Beyond customer payments, cryptocurrency introduces emerging businesses to alternative ways of handling certain financial activities. Digital wallets, blockchain-based transfers and programmable transactions may provide additional flexibility as companies develop their financial operations.
Some business owners may also become interested in digital assets as part of their broader financial strategy. However, accepting cryptocurrency as payment and purchasing it as an investment are two different decisions.
Entrepreneurs who want to invest in crypto should first consider their company’s available cash, short-term expenses and ability to withstand market volatility. Money needed for payroll, inventory or essential operating costs generally should not be exposed to speculative investments.
Cryptocurrency prices can change significantly over short periods, and those movements can affect a business’s financial position. Any investment decision should therefore be separate from the company’s payment-processing strategy and supported by appropriate risk controls.
A business does not need to own cryptocurrency to benefit from blockchain-based payment technology.
Supporting Transparency and Transaction Records
Recordkeeping is another area where blockchain technology may offer advantages. Many cryptocurrency networks maintain public transaction histories, allowing participants to verify that transfers have occurred.
For businesses working with multiple suppliers, contractors or customers, this transparency can support payment reconciliation and transaction tracking.
However, blockchain records do not automatically replace accounting systems. A transaction history may show that digital assets moved between wallets, but it does not necessarily identify the customer, explain the commercial purpose or provide all the information required for financial reporting.
Businesses still need accurate invoices, internal records and appropriate documentation.
Tax obligations deserve particular attention. The Internal Revenue Service (IRS) website explains that businesses receiving digital assets as payment must maintain records of their fair market value in US dollars and report applicable transactions for tax purposes.
These requirements make reliable bookkeeping and professional accounting advice especially important when a business begins handling cryptocurrency.
Reaching New Customers and Digital Markets
Emerging businesses often face a difficult challenge: gaining attention in markets where established competitors already have strong customer relationships.
Offering cryptocurrency payments may help certain companies appeal to consumers who actively participate in digital asset markets. This could be relevant to software businesses, online service providers and retailers serving technology-focused audiences.
It may also help businesses participate in digital environments where blockchain-based transactions are already common.
Still, cryptocurrency acceptance should complement a strong business model rather than become the main selling point. Customers are more likely to return because of product quality, reasonable pricing and dependable service than because a company accepts a particular digital currency.
Businesses should also avoid assuming that enthusiasm for cryptocurrency translates into consistent purchasing demand.
A useful starting point is to survey customers, review competitors’ payment options and test whether adding cryptocurrency improves completed sales.
Understanding the Risks Before Getting Started
Despite its potential benefits, cryptocurrency presents several challenges that emerging businesses cannot afford to overlook.
Market volatility remains one of the most significant concerns. A payment received in cryptocurrency could lose value before the business converts it into traditional currency. Stablecoins may reduce some exposure to market fluctuations, but they introduce other risks involving issuers, reserves and redemption.
Security is another consideration. Digital wallets require careful management of private keys and access credentials. Unlike many conventional payment methods, cryptocurrency transfers are generally difficult or impossible to reverse once confirmed.
Businesses should also consider regulatory requirements, transaction reporting and customer protection. Rules can differ depending on the country, the digital asset involved and the company’s activities.
Before introducing cryptocurrency, an emerging business should:
- Identify which payment problems it intends to solve.
- Compare processing fees, conversion costs and settlement times.
- Choose reputable payment providers with appropriate security measures.
- Establish procedures for accounting, taxes and transaction records.
- Train relevant employees to recognize fraud and protect wallet credentials.
- Begin with limited transactions before expanding adoption.
Taking a gradual approach allows businesses to evaluate whether the technology provides measurable benefits without unnecessarily disrupting existing financial operations.
Choosing the Right Time to Adopt Cryptocurrency
Not every emerging business needs cryptocurrency immediately. A local service company with customers who overwhelmingly prefer conventional payments may see little benefit from introducing digital assets.
On the other hand, an online business serving international customers could find cryptocurrency worth exploring, particularly when existing payment methods are expensive or inconvenient.
The decision should begin with practical business needs rather than market excitement.
Owners can examine how frequently international transactions occur, whether customers request cryptocurrency payments and what financial or administrative challenges the technology might address.
They should also evaluate whether their existing payment providers already offer suitable solutions. In some situations, established banking services may remain simpler and more cost-effective.
Successful adoption means selecting tools that improve operations, not introducing technology simply because it is new.
Final Thoughts
Cryptocurrency offers emerging businesses an additional way to approach payments, international transactions and participation in the digital economy. Its potential advantages include greater payment flexibility, access to certain customer markets and alternative methods for transferring money across borders.
Yet these opportunities come with responsibilities. Price volatility, security threats, regulatory requirements and accounting complications can quickly outweigh the benefits when digital assets are introduced without adequate preparation.
For growing companies, the most sensible approach is to evaluate cryptocurrency as one possible financial tool rather than a necessary part of modern business.
By focusing on genuine customer needs, operating costs and long-term financial stability, entrepreneurs can make informed decisions about whether cryptocurrency has a useful place in their business strategy.

Every perpetual-futures DEX in this comparison lets a trader open positions by connecting a self-custodial wallet instead of submitting an ID, and their headline costs sit close together: Aster charges 0.01% maker and 0.035% taker, while EVEDEX and Hyperliquid both charge 0.015% maker and 0.045% taker (each venue’s own documentation, read 21 September 2026). The choices that actually separate them lie elsewhere — how each screens deposits, how much leverage it permits, and how many asset classes reach one balance. This guide compares EVEDEX, Hyperliquid, dYdX, GMX and Aster on the points that decide which no-KYC venue suits which trader.
Key takeaways
• All five allow trading from a self-custodial wallet with no traditional account KYC; EVEDEX additionally screens every deposit through automated on-chain AML checks (EVEDEX Help Center, verified 14 September 2026).
• Base fees are lowest on Aster (0.01% / 0.035%); EVEDEX and Hyperliquid match at 0.015% / 0.045%; dYdX is 0.02% / 0.05%; GMX charges 0.04–0.06% per side.
• Maximum leverage on majors ranges widely: EVEDEX up to 200x on BTC, ETH and SOL for positions up to $50,000 notional; GMX and Aster up to 100x; Hyperliquid up to 40x on BTC; dYdX up to 20x.
• Asset breadth differs sharply: EVEDEX is a multi asset trading platform with 52 perpetuals across crypto, stocks, commodities, FX and pre-IPO; dYdX is crypto-only; Aster lists 480-plus mostly-crypto markets.
• EVEDEX matches orders off-chain and settles on-chain on Arbitrum (layer 2); Hyperliquid and dYdX run fully on-chain order books on their own chains; GMX quotes an oracle price against liquidity pools.
|
Parameter |
EVEDEX |
Hyperliquid |
dYdX |
GMX |
Aster |
|
Account verification |
No traditional KYC; on-chain AML screening |
Wallet connect; no account verification |
Wallet connect; self-custody |
Wallet connect; self-custody |
Wallet connect; self-custody |
|
Base fees (maker / taker) |
0.015% / 0.045% |
0.015% / 0.045% |
0.02% / 0.05% |
0.04–0.06% per side |
0.01% / 0.035% |
|
Max leverage |
Up to 200x (BTC, ETH, SOL; ≤ $50k notional) |
Up to 40x (BTC) |
Up to 20x (BTC, ETH) |
Up to 100x |
Up to 100x (1001x on select pairs) |
|
Asset classes |
Crypto, US stocks, commodities, FX, pre-IPO (52 perps) |
Crypto, some stocks, pre-IPO (100+) |
Crypto only |
Crypto, commodities, stocks |
Crypto, stocks, commodities (480+) |
|
Settlement |
Off-chain matching, on-chain settlement on Arbitrum (L2) |
On-chain order book, own L1 |
On-chain order book, Cosmos appchain |
Oracle pricing vs liquidity pools (Arbitrum, Avalanche) |
Order book, own L1 + multi-chain |
|
Margin model |
Cross only, USDT |
Cross and isolated, USDC |
Cross only, USDC |
Isolated, multi-collateral |
Cross and isolated |
Fees, leverage, asset classes, settlement and margin: each venue’s own documentation, read 21 September 2026; EVEDEX figures from its documentation and trading terms, verified 14–18 September 2026. Platform parameters change, so these values are fixed to the dates on which they were read.
What “no KYC” actually means here
On all five platforms, “no KYC” means wallet-based access rather than anonymity, and the compliance layer behind that wallet is where they differ. None asks for a passport or a selfie to place a trade; a trader connects a self-custodial wallet and posts margin. That model is the trading version of what self-custody already does for moving Bitcoin without a central login, covered in 5 ways Bitcoin protects your privacy abroad in 2026. EVEDEX takes a middle path on crypto without KYC: it runs no traditional KYC to trade, while every deposit passes automated on-chain AML screening. That screening model is documented in the EVEDEX Help Center (verified 14 September 2026).
The peers describe their own access plainly. Hyperliquid’s documentation states there is no account verification and no withdrawal-approval step, with funds held in the trader’s wallet. dYdX, GMX and Aster likewise document permissionless, self-custodial access: a connected wallet is the account. The practical point for a reader is that wallet-based access is the norm across this category, so the differentiator is not whether verification is skipped but what sits behind it.
Cost: fees and leverage
On raw fees the field is tight, and EVEDEX sits at the low end without being the cheapest. Aster is lowest on paper at 0.01% maker and 0.035% taker (Aster docs, read 21 September 2026). EVEDEX and Hyperliquid share the next step at 0.015% maker and 0.045% taker (EVEDEX Trading Fees, verified 16 September 2026; Hyperliquid docs, read 21 September 2026). dYdX charges 0.02% maker and 0.05% taker at its base tier (dYdX Help Center), and GMX prices differently again — 0.04% or 0.06% to open and the same to close, charged against position size rather than as maker/taker (GMX docs). At EVEDEX’s rate, a round trip on a taker order costs 0.09% of notional; at Aster’s, 0.07%.

Base maker and taker fees across the five perpetual DEXs, from each venue’s documentation (read 21 September 2026).
Leverage is where the platforms part ways, and higher leverage is a shorter fuse rather than a larger edge. EVEDEX lists the highest ceiling — up to 200x on BTC, ETH and SOL for positions up to $50,000 notional (EVEDEX trading terms, verified 16 September 2026) — ahead of GMX and Aster at up to 100x, Hyperliquid at up to 40x on BTC per its margin-tier documentation, and dYdX at up to 20x on majors. Leverage sets how far the market can move against a position before liquidation: at 200x the initial margin is about 0.5% of the position, so a move of roughly half a percent can erase it, while at 20x that cushion is about 5%. Across regulated CFD providers, between 74% and 89% of retail accounts lose money (ESMA) — a reminder that leverage amplifies losses as readily as gains.
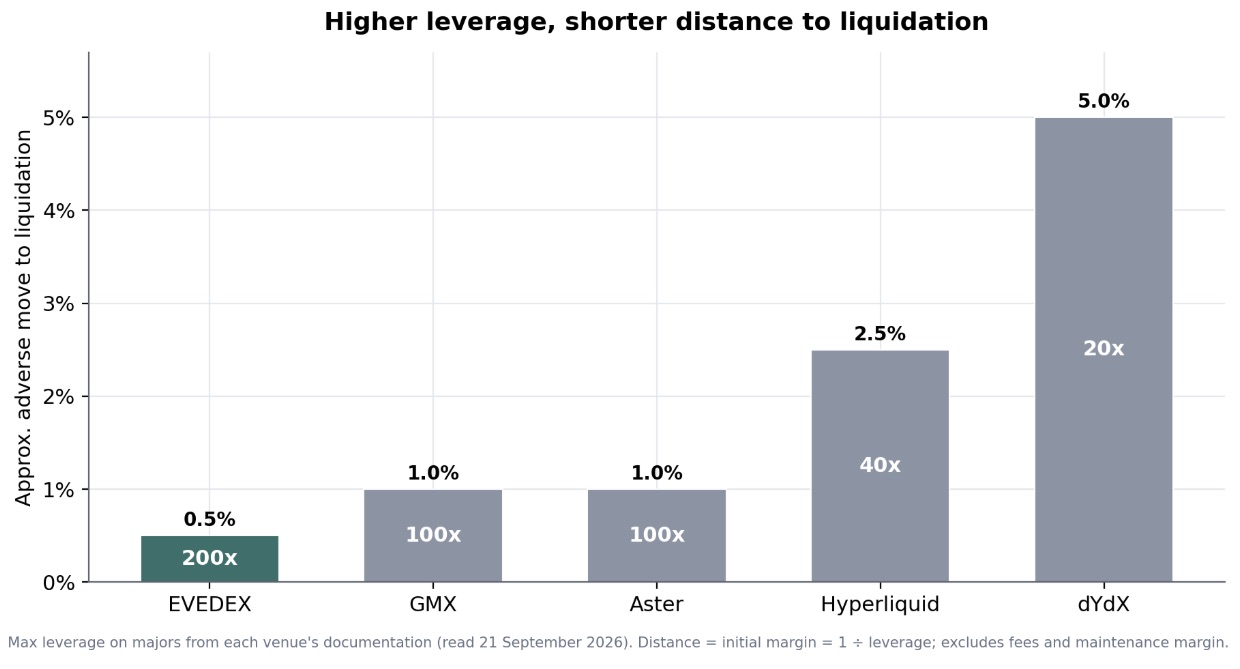
Maximum leverage and the approximate adverse price move to liquidation it implies.
What you can trade, and how it settles
If the goal is more than crypto from one balance, EVEDEX and GMX span the widest set of asset classes. From a single USDT balance, EVEDEX lists 52 perpetuals covering crypto, five US stocks, commodities including gold through a Tether Gold (XAUT) contract, two FX pairs and two pre-IPO markets (EVEDEX trading terms and CoinGecko, verified 16 September 2026). GMX adds commodities and a stock market alongside crypto; Aster lists 480-plus mostly-crypto markets; dYdX stays crypto-only.
Settlement design divides them too. EVEDEX is a hybrid perpetual-futures exchange: orders are matched off-chain in its order book and settled on-chain on Arbitrum (layer 2), which keeps execution fast while final settlement is verifiable on-chain. Hyperliquid and dYdX run fully on-chain order books on their own chains, and GMX quotes an oracle price and fills against pooled liquidity rather than an order book. Each design trades some transparency against some speed, and the right one depends on what a trader values.
Limitations
EVEDEX has clear gaps. It offers cross margin only, so a trader who wants to wall off risk on a single position with isolated margin will not find that here. It runs no spot market — all 52 instruments are perpetuals. Its market count is small beside venues that list several hundred, and its base taker fee of 0.045% is not the lowest in this group. Its 200x ceiling, the highest here, magnifies liquidation risk rather than lowering cost. Traders who want the widest choice of individual crypto markets, or who depend on isolated margin, are better served elsewhere.
Which one fits
For the lowest headline fees on crypto perpetuals, Aster leads this group; for deep BTC and ETH books at moderate leverage, Hyperliquid is a common choice; dYdX suits traders who want a crypto-only, fully on-chain order book. EVEDEX fits a narrower case: a trader who wants crypto, US stocks, commodities, FX and pre-IPO exposure from one USDT cross-margin account, and who values a no-traditional-KYC model paired with on-chain AML screening over the last basis point of fee. Matching the platform to the way a trader actually works matters more than any single number.
A founder will bet the company, learn sales, and still call Bitcoin too risky to hold a small piece of.
The objection is usually one of three. Too risky. Too confusing. Gambling. The first one is the oddest. Starting the business was risky. Leaving the job was risky. You did both because you could see a return if you stayed in the work. A coin is not the business. It is also not a mystery that only a desk can parse. Taxes were confusing. You learned the version you needed. The gambling charge is the one that sticks, and it sticks when there is no rule. A purchase with no size, no time frame, and no plan for an 80% drop is a bet. A purchase with those three is a position. They are not the same afternoon.
The backdrop is why the search exists. A house that used to cost a few years of salary now costs most of a decade. Cash in the bank does not close that gap. Raoul Pal, who used to sell hedge fund research and now runs Real Vision, puts a number on the leak in the conversation below. He argues that once ordinary inflation and the quieter loss of purchasing power are counted, cash gives up something like 11% a year, and the S&P 500’s long run only keeps you level. Bitcoin, in his telling, has compounded well over 100% a year since 2011, and that average already includes three drops of about 80%. Michael Saylor makes the cousin claim from a company treasury. The dollar has lost scarce-asset value for a century, a house carries tax and upkeep, and Bitcoin is the piece you can move without seven banks agreeing.
At a Bitcoin conference, asked what a beginner should actually do, the answers were smaller than the banners. Kevin O’Leary, who sold a company for billions, said get a centralized wallet and a self-custody wallet, put in about $200, and expect to lose it. Not as a joke. As the tuition. You learn who can take it, what you did wrong with the keys, and why a login is not the same as holding it. Then, he said, work with a few coins. Bitcoin. Some Ethereum, because a lot of the rails still use it. Solana if you want to see a faster chain. Move a small amount between the two wallets until the move is boring. Brian Jung, who has spent years on camera in this market, said the same thing from the other side. You will slip. The only useful slip is the one you write down. Saylor’s version, when he was caught in a hallway, was education before size. Do not put money in on a rumor, a whim, or a countdown. Learn how it works the way people had to learn electricity. Then decide.
For beginners who want to get started, one option is to buy Bitcoin with a credit card on Paybis.
Entrepreneurs hear a cruder version from people who are up this week and want a call booked. Ignore the scoreboard. The part that is true is narrower. You are often good at making money and bad at deploying it. A bank balance is not a plan. Bitcoin is scarce in a way a currency is not. There will only be 21 million. It is also a practical rail. If you pay a contractor in another country, a transfer that does not sit in a bank that can freeze the account is not a philosophy. It is a Friday. That use does not require you to trade. It requires you not to lose the keys, which is what the $200 was for.
The framework that keeps the rest from being a casino comes from people who have already been wiped out once. Hold Bitcoin. Trade everything else, if you trade at all. Holding asks you to be right once, over years. Trading asks you to be right on a schedule. Most people watching a clip should do the first and skip the second until they have sat through a full cycle, including the year it felt finished. Keep at least half the crypto pile in Bitcoin at all times. A basket of twenty altcoins is not diversification. In this market it is the same bet, with worse drawdowns. Never put the whole pile in one coin, one launch, or one week you feel clever. Take trading profits back into Bitcoin earlier than the group chat wants. For example, investors holding Ethereum may consider an eth to btc swap when rebalancing their portfolios and moving a portion of their holdings back into Bitcoin. Altcoin narratives, when they run, often die inside a few months. Bitcoin is the thing that has, so far, made a higher floor after each bust.
Have you missed it at 30. The cycle where a dorm-room amount became a house is gone. The one still open is a long hold, sized so a 70% drop does not touch rent, set against cash that can make you poorer without crashing. If you are in the quarter-life stretch, the coin will not fix the calendar. Income still comes first. Getting the money right means knowing what the year cost before you move a surplus. Then the surplus can have a job. A target, a date, and a rule you wrote down while the price was boring.
This is not financial advice – It is not a recommendation to buy, sell, or hold anything. Crypto can go to zero, keys can be lost, and past returns are not a forecast. If you need a decision about your money, talk to someone who is allowed to give you that advice.

Accountant vs Bookkeeper: Who Your One-Person Business Should Hire First

D&O Insurance for Startups: The Policy Investors Quietly Expect Before They Take a Board Seat

What is the purpose of creating a framework for evaluating soft skills training?

Why Creative People Wait Until the Last Minute

What Grant Cardone Taught Me About Getting Out of Scarcity
5 Ways For Startups To Succeed Making Acquisitions

77 Inspirational Quotes That Will Change Your Life
57 Memorable Kobe Bryant Quotes

Motivational Picture Quotes: 52 Images to Inspire a Successful Year
40 Rare Motivational and Inspirational Picture Quotes
3 Prince EA Videos To Change Humanities Path To Greatness
(Video) What Is Success? An Entrepreneurial Story To Inspire You
(Inspirational Video) What If Today You Knew You Were Going To Take Your Last Breath?
How To Make Enough Money From A Blog To Quit Your Job – Kate McKibbin
How Finding Your Passion And Becoming An Entrepreneur Can Lead To Happiness – Chiquita Searle
-

 Did You Know1 year ago
7 Surprising Life Lessons Video Games Taught Me That School Never Did
-
 Life2 years ago
The 5 Stages of a Quarter-Life Crisis & What You Can Do
-
 Success Advice1 year ago
Stephen Covey’s 8 Leadership Habits That Will Change How You Lead Forever
-

 Featured2 years ago
The Psychology of Motivation: How to Keep Moving Forward Every Day
-

 Life1 year ago
How to Stop the War in Your Head and Find Peace
-
 Personal Development2 years ago
The Three-Second Pause That Changes How People Perceive You
-
 Explode Your Social Media1 year ago
Want More Views? Master These 6 YouTube Growth Tactics
-
 Change Your Mindset1 year ago
You Become What You Absorb: How Input Shapes Your Life